

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Automotive Torsional Vibrational Damper Market Poised for a 3.5% CAGR Through 2032

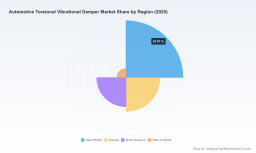
Worldwide Automotive Torsional Vibrational Damper Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting today releases a strategic briefing synthesizing the key findings from our forthcoming Worldwide Automotive Torsional Vibrational Damper (TVD) Market report. Designed as an executive “trailer” for senior leaders, this briefing highlights the structural forces shaping the TVD market through the 2026 planning cycle while deliberately withholding granular segment tables and proprietary breakdowns. Our objective is to equip boardrooms, product chiefs, procurement heads and investors with the high‑confidence directional intelligence they need to prioritize investments and mitigate execution risk in 2026.
Industrial Noise Control System Market
Snapshot: What the headline numbers mean for strategy
The global TVD market returned to growth after pandemic‑era volatility, with a 2025 market base of roughly USD 2.64 billion (base year 2025). Our model projects a steady expansion through the 2026–2032 forecast window at a compound annual growth rate of approximately 3.5%, reaching just over USD 3.36 billion by 2032. These headline dynamics reflect a market that is mature yet responsive to powertrain transitions, regulatory pressure and material/technology substitution — conditions that reward clear strategic choices rather than broad hedging.
Worldwide Metal Diaphragm Compressor Market
Why this briefing matters for 2026 decisions
- Prioritization: Which TVD technologies and sub‑systems should receive R&D and capex focus in the next 12–18 months?
- Sourcing & supplier strategy: When to consolidate suppliers versus when to insource critical capabilities (e.g., viscous damping elements, composite housings, sensor integration).
- Product roadmap alignment: Which powertrain architectures merit dedicated TVD solutions (48V mild‑hybrid, downsized turbo combustion engines, high‑torque commercial platforms)?
- M&A and partnerships: Where are buy vs. build tradeoffs most favorable for accelerating sensorized/hybrid damper capabilities?
Market trajectory and interpretation
The TVD market’s recent trajectory underscores two themes for 2026 planning. First, demand remains sensitive to powertrain mix and regulatory cycles rather than pure vehicle volumes. The proliferation of high‑excitation, downsized turbo engines and mild‑hybrid systems elevates engineering requirements for torsional isolation, creating pockets of above‑market growth. Second, the market is transitioning: material substitution and functional integration are altering product definitions (dampers are increasingly part of multi‑function modules combining pulley, starter/generator interfaces, and sensing). For strategic planners, this means the battle for value is shifting from commodity elastomer components to systems engineering and software‑enabled condition monitoring.
Worldwide Drug Testing Software Market
Technology, materials and product evolution
- Composite integration: Nearly half to majority of new TVD developments now incorporate lightweight composite materials to improve dynamic performance and reduce NVH. This materially changes cost and manufacturing tradeoffs and favors suppliers with thermoset/thermoplastic molding capabilities or strong composites partnerships.
- Sensorization & hybrid dampers: More than 30% of suppliers have introduced or launched hybrid dampers that integrate sensing elements and electronics to support torque management and predictive maintenance. These product variants open recurring software and service revenue streams but require new validation, calibration and cybersecurity competencies.
- Viscous vs. elastomer tradeoffs: Viscous designs continue to be preferred for high‑temperature and high‑load applications, while rubber/elastomer solutions remain competitive where cost and packaging simplicity dominate. Hybrid combinations — viscous cores with elastomer isolators or dual‑stage systems — are emerging as default answers for mixed‑duty requirements.
Regulatory and powertrain forces driving adoption
- Stringent CO2 and fuel efficiency regulations in major markets are accelerating the adoption of downsized, turbocharged engines and mild‑hybrid electrification — both increase torsional excitation and thus demand for engineered dampers.
- The rise of 48‑volt mild‑hybrid architectures (with penetration expected to reach significant levels in the next two to three years in many regions) intensifies demand for integrated belt‑starter/generator isolation units that combine damper, pulley and crank functions.
- Regulatory emphasis on fuel economy and lifecycle emissions also raises the bar for lightweighting and durability; the combined effect is to favor advanced materials and modular, serviceable designs that can be integrated across multiple powertrain variants.
Competitive landscape — how incumbents and specialists are positioning
The market is characterized by a mix of global Tier‑1 integrators, specialist viscous damper houses, and aftermarket system suppliers. Competitive advantage today is built on three vectors: (1) deep system engineering for integrated modules; (2) mastery of materials and manufacturing for lightweight assemblies; and (3) electronics and software expertise for sensorized products.
- Vibracoustic SE (Germany) — Strong in pressed, vulcanized and fluid‑filled damper technologies tailored for light vehicles, and effective in delivering decoupled pulley solutions that match the needs of downsized engines and stop‑start systems.
- Vibratech TVD (United States) — A pioneer in viscous damper technology with a focus on durability in high heat and load use cases; its recent technical documentation highlights dual‑viscous designs to address heat dissipation in premium and high‑torque applications.
- ZF Friedrichshafen AG (Germany) — Brings dual‑mass/damped flywheel expertise to high‑torque and commercial vehicle segments, emphasizing torsional decoupling for heavy‑duty and hybridized applications.
- Continental AG (Germany) — Operates across OEM and aftermarket channels and is advancing integrated modules suitable for 48V systems, as evidenced by recent product introductions combining damper, pulley and crank functions.
- Schaeffler AG (LuK/INA) (Germany) — Focused on crankshaft torsional dampers and pulley decouplers, leveraging broad OEM relationships and powertrain integration know‑how.
- Hasse & Wrede GmbH (Germany) — Specialist viscous damper manufacturer targeting passenger and commercial vehicle engines where viscous damping is preferred for longevity.
- Gates Corporation (United States) — Applies system solution thinking to create belt‑drive linked damper modules for passenger and light commercial segments.
Recent product releases and documentation updates from market players underscore a rapid pace of incremental innovation: examples include new OEM‑grade viscous damper catalogs with dual viscous chamber designs and integrated 48‑volt module launches. These initiatives signal that technical differentiation, rather than price alone, will determine supplier selection for many OEM programs in 2026.
What our full report delivers (practical, operational insights)
PW Consulting’s full market study is built to support transaction and product decisions, not just academic forecasting. Key deliverables include:
- Comprehensive market sizing and a calibrated, bottom‑up demand model across powertrain families and vehicle classes (2020–2032), with sensitivity scenarios for electrification and regulatory outcomes.
- Technology adoption curves and technology roadmaps for elastomer, viscous and hybrid sensorized dampers, including time‑phased cost curves and BOM implications.
- Supplier mapping and capability heatmaps covering manufacturing footprint, testing infrastructure, material competencies and IP positioning.
- Procurement playbooks and cost‑to‑serve frameworks to evaluate make vs. buy decisions and to construct strategic partnerships or captive supply models.
- M&A and partnership shortlists — pragmatic screening criteria and due‑diligence checklists for acquiring sensor/software capabilities or specialty viscous know‑how.
- Regulatory impact assessment and compliance risk matrices that translate CO2/efficiency regulations and 48V adoption timelines into component demand permutations.
- Operational templates: RFP language for integrated damper modules, validation protocols for sensorized units, and aftermarket retrofit commercialization plans.
To maintain independence and commercial confidentiality, the full dataset and granular segment allocations are available exclusively in the complete report and the accompanying data appendix.
Actionable recommendations for 2026 planning
- OEMs: Prioritize integrated 48V module validation with two supply partners — one global integrator and one specialist viscous/hybrid supplier — to balance risk and innovation access.
- Tier‑1 suppliers: Accelerate investment in composites molding and sensor integration; bundle software/service offers with hardware to capture lifecycle value.
- Investors: Target mid‑market specialists that combine viscous expertise with scalable manufacturing or niche sensor IP; valuation premiums will accrue to companies with durable OEM contracts and demonstrable NVH performance data.
- Aftermarket operators: Develop retrofit kits and condition‑monitoring services for existing fleets where viscous or hybrid dampers can extend engine life and reduce warranty exposure.
- Procurement and supply chain leads: Implement dual‑sourcing for key damping sub‑assemblies and secure supply of critical composite precursors and nitrile elastomers to avoid single‑point disruptions.
Conclusion: Readiness over prediction
For 2026 strategic planning, the critical question is not whether the TVD market will grow — our outlook is clear — but whether your organization is structured to capture the new sources of product value that are emerging. Companies that combine systems engineering, materials competency and software/service monetization will outpace peers that treat dampers as commodity components. PW Consulting’s full report provides the empirical foundation and the practical playbooks required to convert directional insight into executable advantage.
Access to the complete dataset, granular segment analysis and our actionable templates is available through PW Consulting’s report portal. For tailored briefings, scenario runs and M&A diligence support aligned to your 2026 priorities, PW Consulting’s sector team is available for confidential engagements.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Torsional Vibrational Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com