

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Food Encapsulating Technology Market to Near USD 20 Billion by 2032, Growing at 8.12% CAGR

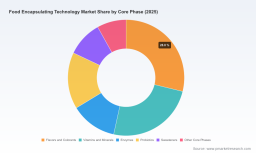
Worldwide Food Encapsulating Technology Market — Strategic Briefing for 2026
PW Consulting presents an executive briefing based on our newly published Worldwide Food Encapsulating Technology Market report (base year 2025). The market reached approximately USD 11.54 billion in 2025 and, with a forecast compound annual growth rate (CAGR) of 8.12% through 2032, is projected to approach USD 19.93 billion by 2032. This briefing distills the report’s core strategic takeaways for corporate decision-makers planning investments, partnerships, and product strategies in 2026 — showcasing analytical rigor while reserving granular segment-level detail for the full report.
Medical Safety Eyewear Market
Why this report matters for 2026 planning
Encapsulation has moved from a specialized formulation technique to a fundamental enabler across food innovation, fortification, and shelf‑life engineering. For 2026, executives must evaluate encapsulation not as a cost center but as a strategic lever that affects product differentiation, regulatory compliance, unit economics, and supply chain risk. Our report synthesizes financial forecasts, technology-readiness assessments, and commercial adoption pathways so that R&D heads, supply‑chain chiefs, and corporate development teams can prioritize investments with measurable ROI horizons.
Active Hydraulic Suspension Market
Market trajectory and key macro drivers
The market’s strong baseline and mid-single-digit to high-single-digit growth dynamics reflect multiple converging forces. Demand for fortified and functional foods (vitamins, minerals, probiotics), expansion of clean‑label formulations, and the need to protect labile actives through processing and distribution are enduring growth engines. Regulatory frameworks that tighten labeling and fortification requirements likewise create recurring demand for robust delivery systems. On the supply side, manufacturing capacity expansions and technology innovations are improving unit economics and enabling broader adoption beyond beverage and dairy into snacks, bakery, and meat applications.
Launch Software Tools Market
- Stability and bioavailability needs: Encapsulation extends shelf life and stabilizes sensitive actives — a direct response to formulators’ need to meet nutrition claims reliably during shelf life and distribution.
- Clean‑label and sustainability pressures: Demand for plant-based carriers and natural wall materials is accelerating R&D into alternatives to traditional gums and animal-derived proteins.
- Scale and cost-efficiency: Capital investments in high-throughput encapsulation capacity are shifting economics to favor broader deployment across mainstream SKUs.
- Food safety and functional claims: Innovations that safely deliver live cultures or bacteriocin-producing strains support both safety enhancements and differentiated functional positioning.
Practical contents of the full PW Consulting report
Our report is structured for immediate operational use by manufacturers, ingredient suppliers, and strategic investors. It includes:
- Validated market sizing (historical 2020–2025, forecast 2026–2032) and scenario models to test downside and upside adoption paths;
- Competitive landscaping with capability maps, manufacturing footprints, and technology readiness scores;
- Technology dossiers covering spray, thermal, mechanical, and emerging bio‑based encapsulation methods, with selection matrices keyed to ingredient classes and processing constraints;
- Commercial playbooks: go-to-market strategies for ingredient suppliers, co-manufacturers, and brand owners including pricing frameworks, margin impact analyses, and contract manufacturing decision guides;
- Supply‑chain risk matrix and raw material outlooks for common wall materials such as polysaccharides and proteins, including substitution pathways and cost-sensitivity analysis;
- Regulatory and labeling matrix mapping encapsulation strategies to compliance pathways across major jurisdictions;
- Deal flow and M&A tracker, plus an IP landscape to inform partnership or acquisition targets;
- Customizable financial models and an executive dashboard for scenario planning.
These deliverables turn market intelligence into executable initiatives: product roadmaps, capacity investment plans, and targeted M&A or alliance strategies.
Competitive landscape — who to watch and why
The industry exhibits a mix of specialty encapsulators, large ingredient conglomerates, and disruptive newcomers. Market concentration is meaningful but not prohibitive — the leading three players account for a notable share of value and the top five amplify that share, leaving room for nimble specialists and regionally focused providers to capture growth.
- Balchem Corporation — Balchem’s portfolio of branded microencapsulation technologies for bakery, confectionery, and meat positions it as a bridge between ingredient innovation and high-throughput manufacturing. Its recent investment in a high-capacity facility signals commitment to scale and faster time-to-market for co-manufacturing partners.
- Cargill — With deep carbohydrate science and global production capabilities, Cargill is a strategic partner for beverage and large-scale fortification programs where cost and supply continuity are critical.
- Kerry Group — Kerry leverages R&D strength in clean-label systems and tailored flavor-nutrient combinations, serving brand owners focused on sensory-driven fortified products.
- Ingredion — Ingredion’s emphasis on polysaccharide-based wall materials addresses formulators seeking starch-based encapsulants compatible with dairy and snack formulations.
- BASF and DSM‑Firmenich — These firms supply advanced delivery chemistries (stability, bioavailability, controlled release) and commonly play in premium nutrition and carotenoid/vitamin segments.
- Flavor houses (Givaudan, IFF, Symrise) — Encapsulation is increasingly embedded in flavor delivery strategies to protect volatile compounds and enable novel sensory releases.
- Specialists and disruptors (FrieslandCampina Kievit, Sensient, TasteTech, Xampla) — These players either serve niche technical requirements or introduce disruptive material science. Notably, plant-protein based microcapsules are emerging as a credible sustainable alternative, validated in peer-reviewed settings.
For buyers and partners, the strategic question is whether to co‑develop with a specialty provider, source from a large incumbent for scale, or invest in internal capability. Our report provides decision trees and partner scorecards to align your choice with strategic outcomes.
Recent industry moves that reshape 2026 choices
- Capacity expansions matter: Announced new production facilities by major encapsulators signal faster fulfillment and lower lead times — a critical factor for brands planning rapid SKUs expansion or regional launches.
- Material science validation: Peer-reviewed demonstrations of plant-protein microcapsules protecting fat‑soluble nutrients validate a sustainable pathway that reduces reliance on traditional wall materials and supports clean‑label claims.
- Regulatory-driven demand: Tighter fortification and labeling regimes accelerate the adoption of encapsulation to ensure claim integrity and to mitigate nutrient degradation during shelf life.
Top strategic implications for 2026
- Prioritize portfolio mapping: Use our ingredient-by-application matrices to rank SKUs that benefit most from encapsulation based on price elasticity, processing stress, and claim criticality.
- Align capex with demand windows: If your roadmap includes multiple fortified SKUs or live-culture products, earlier investment or strategic partnerships with firms expanding capacity will avoid missed launch windows.
- Secure differentiated raw-material supply: Establish dual-sourcing for key wall materials and evaluate plant-protein alternatives to mitigate commodity volatility and appeal to sustainability-conscious consumers.
- Design regulatory-first formulations: Build encapsulation strategies that meet both labeling and safety requirements — particularly for live microbe delivery and novel antimicrobials — to reduce market-entry friction.
- Consider bolt-on acquisitions or JV’s: For ingredient companies seeking rapid capability upgrades, acquiring niche encapsulation specialists or entering targeted JVs can compress time-to-market and lock in IP.
How PW Consulting helps
Our full report not only quantifies market size and growth (historical and forecast) but equips decision-makers with the executable tools required to convert insights into outcomes: supplier shortlists, financial models, go-to-market playbooks, and a prioritized action plan for 12–36 month horizons. We provide scenario-based recommendations calibrated to company size, risk appetite, and strategic intent.
Next steps
This briefing is a strategic “trailer” designed to demonstrate the depth and practical utility of our analysis while preserving the granular segmentation, region- and application-level benchmarks, supplier scorecards, and downloadable financial models available in the full report. For teams preparing investment cases, product launches, or M&A strategies in 2026, the full report delivers the maps and models you will need to move from intent to execution.
Contact PW Consulting to access the complete Worldwide Food Encapsulating Technology Market report and associated advisory services, including tailored workshops and model customizations to accelerate your 2026 decision cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Food Encapsulating Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com