

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Low‑VOC Coating Additives Market Poised to Grow at a 6.42% CAGR During 2026–2032

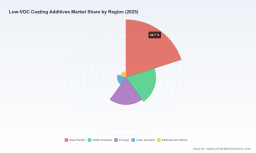
PW Consulting Releases Strategic Brief: Worldwide Low‑VOC Coating Additives Market — Imperatives for 2026 Decision‑Makers
Executive snapshot
PW Consulting’s latest market study, Worldwide Low‑VOC Coating Additives Market (base year 2025; historical 2020–2025; forecast 2026–2032), equips executives with the forward‑looking intelligence required to make high‑stakes product, investment, and regulatory-compliance decisions in 2026. The low‑VOC additives market reached USD 7,208.15 Million in 2025 and, under PW Consulting’s scenario framework, is projected to expand to approximately USD 11,142.59 Million by 2032 — reflecting a compound annual growth rate (CAGR) of 6.42% over the 2026–2032 forecast window. This growth trajectory masks materially different risk‑return profiles across technologies, channels, and geographies; our full report reconciles those differences with primary research, transactional evidence, and proprietary modeling.
Worldwide Underwater Connectors Market
Why this market matters now
-
Regulatory acceleration: Recent and ongoing regulatory shifts (including revised U.S. EPA aerosol standards, California SCAQMD VOC limits, and European harmonization under deco‑paint directives) are compressing time to compliance and creating first‑mover advantages for certified low‑VOC offerings.
Autonomous Underwater Vehicles (AUV) Market -
Sustainability and procurement: Brand owners and large specification buyers increasingly demand low‑VOC formulations that also demonstrate lower carbon intensity or bio‑content; certification and chain‑of‑custody credentials are becoming table stakes in tender processes.
Worldwide Local Marketing Software Market -
Technology convergence: Multifunctional additives (e.g., rheology control combined with reduced VOC coalescing) and advanced waterborne chemistries are reducing the historical tradeoffs between performance and emissions.
-
Consolidation and specialization: The market structure shows concentration at the top of the value chain alongside a healthy mid‑tier of specialty players — a dynamic that shapes M&A, pricing, and supplier selection strategies.
What’s inside the report — practical outputs for executives
PW Consulting’s report is built as a decision toolkit rather than an academic exercise. Highlights of the deliverables:
-
Proprietary market sizing and forward curves (2020–2032), including base‑case, upside, and downside scenarios that stress regulatory and feedstock volatility.
-
Regulatory impact matrix mapping jurisdictional limits, test methods (e.g., ASTM D6886), and compliance timelines to specific product reformulation requirements.
-
Supplier scorecards and binary decision trees for procurement — covering capability fit, certification readiness (ISCC, mass balance), and supply‑risk indicators.
-
Competitive playbooks: go‑to‑market, channel segmentation, OEM vs trade channel strategies, and three ready‑to‑deploy commercialization roadmaps tailored to mid‑cap and large manufacturers.
-
R&D prioritization framework and technology scouting brief to evaluate bio‑based feedstocks, multifunctional additive chemistries, and low‑carbon coalescents.
-
M&A heatmaps and diligence checklists that align target attributes with synergy levers (portfolio tuck‑ins, geographic coverage, capability gaps).
-
Pricing and cost‑curve models that integrate raw‑material inflation, likely pass‑through scenarios, and margin sensitivity by product family.
Each section is supported by appendices containing interview transcripts with formulators and purchasing leads, laboratory evaluation protocols, and data exports that clients may license for internal modeling.
Key strategic implications for 2026
-
Prioritize multifunctionality in product roadmaps. Additives that deliver VOC reduction without sacrificing rheology, open time, or appearance are winning specification battles. Investment in R&D for hybrid chemistries will produce outsized returns in specification‑driven segments.
-
Certify and label proactively. Mass‑balance and chain‑of‑custody certifications (e.g., ISCC PLUS) materially accelerate buyer acceptance, particularly among multinational formulators and retailers. Certification timelines should be built into 2026 product launch calendars.
-
De‑risk feedstock exposure. Strategic supply agreements for bio‑based polyols, biosurfactants, and low‑carbon coalescents reduce reformulation risk and stabilize gross margins during raw‑material shocks.
-
Design targeted M&A: with market concentration reflecting meaningful shares at the top (CR3 ~31.4% and CR5 ~44.8%), selective acquisitions can create scale in premium channels or add specialty capabilities absent from incumbent portfolios.
-
Embed regulatory scenario planning into product launches. Anticipate accelerated adoption curves where regional limit tightening is imminent — and align production footprint decisions accordingly.
Competitive landscape — what incumbent and challenger moves mean
The leading additives suppliers are pursuing complementary strategies that illustrate the two parallel routes to growth in 2026: breadth of portfolio and depth of specialty. A concise assessment of core players covered in the study:
-
BASF SE — Leveraging a broad portfolio to offer turnkey wet‑chemistry solutions across architectural, industrial, and automotive coatings; strong channel reach makes BASF a primary partner for formulators seeking end‑to‑end reformulation support.
-
Evonik Industries AG — Focused on high‑performance and sustainability credentials (e.g., ISCC‑certified TEGO products) to capture premium specifications in waterborne markets; their recent mass‑balanced launches underscore a strategy built on credible sustainability claims.
-
Dow Inc. — Expanding low‑VOC acrylic emulsions demonstrates an integrated play to control both polymer and additive layers, enabling competitive bundled offerings to architectural and industrial coatings customers.
-
Eastman Chemical Company — Strong in specialty coalescents and performance enhancers that smooth the transition to low‑VOC systems for high‑spec industrial and automotive applications.
-
Allnex, AkzoNobel, Arkema, and other specialty resin/additive suppliers — These players are differentiating via application engineering and channel partnerships, particularly in high‑performance and UV‑curable niches.
-
Regional and niche players (Elementis, Huntsman, Seqens, LANXESS, ALTANA/BYK, Nouryon, etc.) — Agile in application support and often the source of localized innovation; their moves shape price and specification dynamics in regional markets.
Recent product and brand initiatives highlight the competitive tempo: LANXESS’s introduction of a next‑generation multifunctional low‑VOC coalescent in April 2026 signals intensified competition in multifunctional chemistries; hubergroup’s new additive brand launched in early 2026 illustrates how mid‑tier players are repositioning to capture global formulators; Dow’s portfolio expansion in March 2026 reinforces a vertical integration trend. These developments collectively indicate that product differentiation, sustainability credentials, and speed‑to‑market are the primary axes of competition this year.
Regulatory and raw‑material dynamics to monitor
-
U.S. EPA changes to aerosol coating standards (including reactivity factors) and California’s continued strict VOC ceilings force earlier reformulation cycles and increase the importance of validated test methods in procurement specifications.
-
European harmonized limits and ASTM test methods (e.g., D6886) create de‑risked pathways for global product launches, but they also elevate compliance costs for small innovators without testing infrastructure.
-
Feedstock transition is both an opportunity and a constraint: vegetable oil‑derived polyols, biosurfactants, and other bio‑based inputs enable lower VOC profiles, but scaling these inputs sustainably requires investment in supply contracts, verification, and back‑integration options.
Actionable recommendations for 2026 planning cycles
-
Run a 12‑month certification fast‑track for one strategic product line to secure specification wins by H2 2026.
-
Model three reformulation scenarios that incorporate both regulatory tightening and two feedstock price shock cases; prioritize projects with lowest time‑to‑market and highest margin protection.
-
Screen target M&A opportunities for capability gaps (e.g., multifunctional additives, certificate‑ready product lines) and for bolt‑on opportunities that reduce customer concentration risk.
-
Invest in application labs in at least two strategic regions to shorten co‑development cycles with formulators and to win private‑label contracts.
How PW Consulting supports active decision‑makers
Our practice couples industry expertise with transaction and technical due‑diligence capabilities. For 2026 engagements we offer:
-
Deep‑dive workshops that convert market scenarios into a prioritized project pipeline for R&D and commercial teams.
-
Targeted M&A origination and diligence, including lab validation protocols and synergy quantification tailored to coatings additives.
-
Regulatory monitoring dashboards and a bespoke cost‑impact model that clients can operate internally.
-
Custom benchmarking against the competitive set and tailored pricing strategies by channel and application.
Next steps — where to find the detailed intelligence
This release highlights the strategic shape of the low‑VOC additives market and the decision levers that matter most in 2026. PW Consulting’s full report contains the granular segmentations, regional demand breakdowns, and company‑level financial and volume estimates that underpin the recommendations summarized here. For boards, corporate development teams, and R&D leaders preparing 2026 investment plans, the full dataset and our proprietary models are indispensable. Visit PW Consulting’s report page to access the complete report and to schedule a tailored briefing with our lead analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Low-VOC Coating Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com