

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Industrial Flexible Hose Market to Reach USD 22,331.23 Million by 2032 at a 5.12% CAGR

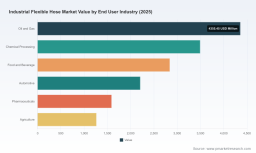
Worldwide Industrial Flexible Hose Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s new Worldwide Industrial Flexible Hose Market report (base year 2025) provides a decision-grade view of an industry entering its next phase of consolidation and product differentiation. The global market reached approximately USD 15,744 Million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 5.12% over the 2026–2032 horizon. Under PW’s baseline scenario, the market is expected to cross the USD 22.3 billion mark by 2032, with the near term (2026) projected to expand to roughly USD 17.07 billion.
New Energy Vehicle Servo Motor Market
For executives making allocation, sourcing, and product strategy choices in 2026, the report is designed to be immediately actionable: it pairs macro trajectory and risk scenarios with supplier benchmarking, product roadmaps, raw-material sensitivity models, and go-to-market playbooks tailored to capital projects and aftermarket channels.
Superconducting Coaxial Cable Market
Why 2026 is a pivotal year
Several converging dynamics make 2026 a watershed for industrial hose manufacturers, OEMs, distributors, and major end-users:
Worldwide Bile Acid Market
- Capital-intensive sectors are re-accelerating. Global oil & gas capex trajectories suggest a meaningful uplift in fluid-transfer and chemical-resistant hose demand tied to upstream and midstream projects.
- Input cost pressure is real and persistent. Natural rubber supply constraints and commodity spikes—illustrated by Q4 2024 rubber price increases and elevated PTFE resin costs—are reshaping cost-to-serve models and pushing manufacturers to revisit procurement, product design, and pricing cadence.
- Regulatory and standards updates are forcing product requalification. Revisions to international hose standards require near-term compliance investments and create an opportunity for quality-differentiated players to capture aftermarket share from legacy suppliers.
- Fragmentation creates playbook opportunities. The market remains fragmented — the top-three and top-five vendors account for single-digit-to-low-double-digit shares — leaving space for both regional champions and global platform players to pursue scale or specialization strategies.
Market dynamics and risk map
PW’s 2026 risk map highlights four vectors that will drive buyer behavior and supplier economics through the forecast period:
- Raw-material volatility — natural rubber prices rose in 2024 due to Southeast Asian supply constraints; fluoropolymer (PTFE) pricing has moved materially higher amid broader semiconductor and industrial demand.
- Labour and manufacturing footprint optimization — manufacturing wages and assembly costs have increased in key markets, prompting reshoring, process automation, and strategic outsourcing decisions.
- Standards and product requalification — recent updates to hydraulic hose standards necessitate re-testing and catalog updates, increasing time-to-market for new hose platforms but improving overall safety and performance benchmarks.
- End-market capital cycles — infrastructure, mining, and petrochemical project pipelines will drive episodic demand; aftermarket and service contracts will smooth revenues for companies that can deliver lifecycle solutions.
Competitive landscape — who’s shaping the market
The competitive field blends global OEM brands with regional specialists. Large diversified players continue to invest in branded hose platforms and distribution networks, while nimble specialists focus on material innovation and high-purity niches. Key dynamics observed across the market include:
- Product-led differentiation: Major manufacturers are accelerating launches of abrasion-resistant thermoplastics, hybrid constructions and PTFE-lined solutions to serve demanding subsea, mining and chemical applications. Recent examples include thermoplastic mining series and higher burst-pressure mining hoses introduced by leading vendors in 2023–2024.
- Trade-show and application marketing: Several firms used industry shows in 2024 to showcase next-generation platforms for subsea and heavy-equipment applications, signaling a near-term commercialization push for hybrid and high-temperature hoses.
- Geographic positioning and channel strategy: Global players leverage branded aftermarket channels and OEM partnerships, while regional manufacturers compete on customization, lead times and project-level support—creating both acquisition targets and partnership opportunities.
Notable manufacturers analyzed in the report (with full company profiles and strategic scorecards) include leading global brands and a selection of regional specialists. Each profile dissects product portfolios, manufacturing footprint, technology roadmaps, channel strategies and recent developments, providing a clear comparator for strategic planning and M&A screening.
What’s inside the PW report — practical tools for 2026
PW Consulting designed this report to be a playbook, not just a narrative. Key deliverables include:
- Market sizing and validated forecast model (2026–2032) with scenario toggles for commodity shock, capex acceleration and regulatory tightening.
- Supplier scorecards that combine technology readiness, margin profile, service capability and geographic reach — enabling rapid shortlist creation for procurement or partnership.
- Raw-material sensitivity and pass-through models that quantify margin erosion and pricing windows under multiple price-path assumptions for rubber, PTFE and thermoplastics.
- Regulatory/compliance matrix mapped to product lines, detailing requalification timelines and cost estimates associated with recent standard updates.
- Go-to-market playbooks for prioritized end-user segments (capital projects vs. aftermarket service), including channel economics, inventory strategies and recommended sales motions for 2026.
- Case studies and five executable growth initiatives — from SKU rationalization and premiumization to digital aftercare (predictive maintenance as a service) — each with estimated payback periods and implementation checkpoints.
Strategic recommendations for 2026
Based on PW’s modelling and supplier analysis, we recommend executives prioritize the following actions in 2026:
- Lock in flexible procurement and hedging mechanisms for rubber and fluoropolymers. Short-duration hedges and diversified supplier panels reduce exposure without sacrificing responsiveness to project wins.
- Invest selectively in hybrid and PTFE-lined product lines where margins justify requalification costs. These product categories are becoming de facto requirements in subsea, chemical and high-purity applications.
- Shift from pure-product selling to lifecycle agreements. Aftermarket services, inspection and replacement programs materially increase customer retention and normalize revenue volatility tied to capex cycles.
- Pursue bolt-on M&A in targeted regional markets to scale distribution and reduce logistics lead times; consider vertical integration for critical raw-material compounding where it materially improves cost-to-serve.
- Prepare for standards-driven portfolio refreshes. Allocate engineering and testing capacity in 2026 to requalify legacy SKUs ahead of tightening industry standards to avoid aftermarket attrition.
Use cases — how different stakeholders should apply the report
- Chief Procurement Officers: use the raw-material sensitivity module to set sourcing KPIs and optimize contract tenors.
- Head of Product/Engineering: leverage the product roadmap and standards matrix to prioritize R&D spend and certification timelines.
- Corporate Development Teams: apply supplier scorecards and M&A screening criteria to identify and underwrite regional consolidation targets.
- Sales and Channel Leaders: deploy the go-to-market playbooks to shift revenue mix toward recurring aftermarket and project-support contracts.
Why PW’s analysis matters for 2026
Our combination of macro forecasting, supplier benchmarking and executable playbooks is calibrated for the 2026 decision cycle. With the market poised to grow from an estimated USD 15.7 billion in 2025 to over USD 22.3 billion by 2032 under PW’s baseline, the window to secure scale, protect margins, and capture aftermarket economics is now. The industry’s low top-player concentration underscores that both consolidation and targeted specialization can deliver outsized returns — but timing and execution will determine winners.
Next steps
The full Worldwide Industrial Flexible Hose Market report contains the segment-level demand analysis, regional demand curves, and the detailed vendor scorecards that underpin the recommendations summarized above. PW Consulting has intentionally withheld granular segment tables and region/application split figures from this briefing to preserve the strategic value of the full dataset.
For access to the complete dataset, forecasting model, and bespoke briefing sessions for executive teams, visit PW Consulting’s market research portal or contact our Industrial Materials practice. Our team is available to run a tailored workshop for procurement, product, or corporate development groups to translate the report’s findings into a 90‑day action plan for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Flexible Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com