

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Medications for Cutaneous Mastocytosis Market Poised for Steady Expansion — 5.15% CAGR Projected (2026–2032)

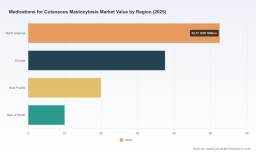
Worldwide Medications for Cutaneous Mastocytosis Market — Strategic Intelligence Briefing (PW Consulting)
The management of cutaneous mastocytosis has entered a new phase of clinical and commercial complexity. Our latest market study — base year 2025, historical period 2020–2025 and forecast window 2026–2032 — synthesizes epidemiology, therapeutic innovation, regulatory change, reimbursement dynamics and supply-chain realities into an integrated decision-support toolkit for 2026. The global market for medications targeting cutaneous mastocytosis transitioned from an estimated USD 89.24 Million in 2020 to USD 120.0 Million in 2025 and is projected to reach approximately USD 170.57 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.15% across the forecast period. This briefing explains how that macro trajectory translates into concrete strategic choices and why the full report is essential for execution in 2026.
Hydraulic Tamping Machines Market
Why this report matters for 2026 strategic decisions
- Actionable forecasting calibrated to real-world inflection points: the 5.15% CAGR masks critical inflection events — new targeted approvals, evolving guideline recommendations and payer responses — that will materially affect launch windows, demand elasticity and formulary access.
- Bridges clinical innovation and commercial reality: with targeted therapies for systemic mastocytosis already demonstrating meaningful improvements in cutaneous manifestations, companies must re-examine treatment positioning, labeling strategies and post‑market evidence plans for dermatology and allergy stakeholders.
- Prioritizes resource allocation under constrained budgets: the report provides scenario-based ROI models that help pharma and biotech prioritize indications, geographies and channel investments in a market that is growing but remains niche and sensitive to payer scrutiny.
- Risk‑adjusted go‑to‑market playbooks: from manufacturing contingencies to KOL engagement and payer dossier sequencing, the research converts market sizing into executable launch and lifecycle-management roadmaps.
What the full report delivers — practical, executable intelligence
Beyond headline market sizing, the PW Consulting study offers a modular suite of deliverables designed for cross‑functional use in 2026: commercial leaders, clinical development teams, BD&L and supply‑chain executives will all find operational guidance. Key report components include:
Worldwide Indoor Location Application Platforms Market
- Market architecture and demand model: end-to-end patient flow analysis, treatment pathway mapping, and a calibrated forecast model (2026–2032) with sensitivity scenarios reflecting regulatory, reimbursement and competitive shocks.
- Unmet need and clinical segmentation framework: evidence-driven typology of patient subgroups, symptom burden profiles and likely uptake curves for symptomatic versus targeted systemic therapies that impact cutaneous manifestations.
- Comprehensive competitive intelligence: company profiles, product positioning, pipeline read‑throughs and an assessment of market concentration dynamics that quantify incumbent strength and whitespace opportunity.
- Go‑to‑market and pricing playbooks: payer‑targeted value messages, HTA evidence requirements, expected list versus net price dynamics, and tiering strategies for hospital, specialty clinic and homecare channels.
- Regulatory and guideline impact analysis: scenario planning based on recent approvals and guideline updates, with recommended regulatory and label-extension pathways for novel molecules and repurposed agents.
- Supply‑chain and manufacturing risk register: identification of critical API and excipient vulnerabilities, mitigation strategies for capacity constraints, and contracting approaches for generic suppliers.
- M&A and partnership screening: valuation frameworks and trigger events that make early-stage assets or manufacturing partnerships attractive in the 2026 landscape.
- Evidence generation roadmap: pragmatic RWE and pharmaco‑epidemiology study designs to support reimbursement submissions, with proposed endpoints and timelines calibrated to anticipated payer windows.
Competitive landscape — what executives need to know now
The therapeutic ecosystem for mastocytosis is best described as moderately concentrated, with a handful of specialized players holding significant positions while a broader cohort supplies symptomatic and generic therapies. Our concentration metrics indicate a market where leading firms collectively command meaningful share but do not preclude new entrants or niche innovators from attaining relevance.
Digital Pathology Image Analysis Software for Clinical Market
- Blueprint Medicines (now operating within Sanofi): the development and commercialization of avapritinib (AYVAKIT) — a selective KIT D816V inhibitor — has shifted the strategic calculus. Avapritinib’s approvals for indolent and advanced systemic mastocytosis and its demonstrated improvements in cutaneous involvement make it an anchor product for any portfolio considering disease‑modifying strategies. Blueprint/Sanofi’s expertise in translating targeted systemic benefit into dermatologic outcomes is a model for others seeking label expansion or cross‑specialty adoption.
- Novartis: with midostaurin (Rydapt) established for advanced systemic mastocytosis, Novartis remains a critical reference for multikinase inhibitor utility and for how systemic therapies influence symptomatic management in cutaneous cases. Their broad product mix and commercialization infrastructure provide a template for payer negotiations and multidisciplinary care pathways.
- Large generic/primary care suppliers (e.g., Viatris, Teva): generics manufacturers that supply cromolyn sodium and antihistamine formulations underpin the symptomatic care backbone. Their production capabilities, pricing pressure and reimbursement relationships sustain the standard‑of‑care environment and will be important counterweights to premium-priced targeted therapies.
Recent developments and regulatory context shaping 2026
- Regulatory catalysts: the market continues to feel the ripple effects of targeted approvals — notably avapritinib’s regulatory milestone in 2023 and the established approvals for midostaurin — which have altered guideline discussions and clinician prescribing behavior where cutaneous manifestations overlap with systemic disease.
- Clinical and guideline evolution: updated national and specialty guidelines released through 2025 underscore a shift toward earlier recognition of systemic involvement and symptom-directed algorithmic care for non‑advanced disease, affecting where and how medications are deployed.
- Reimbursement realities: symptomatic agents (H1/H2 antihistamines and mast cell stabilizers) maintain established reimbursement pathways in major markets, but emerging targeted agents face payer scrutiny that will hinge largely on real-world effectiveness and budget‑impact narratives.
- Supply chain constraints: availability of specialized APIs and certain excipients remains a practical constraint for manufacturers, elevating the strategic importance of on‑shore capacity, dual sourcing and inventory strategies for companies planning scaled launches.
Strategic implications and recommended actions for 2026
For executives making resourcing, portfolio or M&A decisions in 2026, the following priorities should guide near‑term action:
- Reposition pipelines to reflect cross‑disciplinary value: companies developing systemic targeted therapies should build dermatology evidence packages early to demonstrate cutaneous benefit and to support broader market access conversations.
- Invest in payer‑centric RWE fast: time‑bound observational studies that quantify symptom relief, reduced healthcare utilization and QoL gains are decisive for net price negotiations and inclusion in specialty formularies.
- Mitigate manufacturing risk now: secure API contracts, evaluate secondary manufacturing partners and build inventory buffers for niche but high‑value launch scenarios.
- Calibrate launch sequencing to guideline windows: align regulatory filings, KOL engagement, and reimbursement dossiers to anticipated guideline updates and clinician education cycles to maximize uptake.
- Consider bolt‑on acquisitions and partnerships: target assets that fill complementary symptomatic or formulation gaps, or that strengthen supply‑chain resilience and regional market access.
Data transparency and what we intentionally withhold here
In keeping with our “preview” approach, this release illustrates the depth and practical orientation of the analysis without disclosing granular segmentation data that are central to competitive planning. The full report contains detailed breakdowns by region, drug class and treatment setting, along with mapped share estimates, channel economics and unit‑price modeling. These segmentation tables and source datasets are available through the report portal and are critical for constructing market-entry and pricing models.
How PW Consulting supports implementation
PW Consulting offers tailored execution support tied to the report’s findings. Typical engagements for 2026 include rapid-launch readiness audits, payer dossier co‑development, RWE study design and delivery, supply‑chain contingency planning, M&A target due diligence and bespoke market-access simulations. Our teams combine clinical, commercial and regulatory expertise to translate the report’s insights into deliverables that can be actioned within 90–180 days.
Next steps — access the full intelligence
For commercial leaders, clinical development heads and corporate strategy teams preparing 2026 budgets and roadmaps, the full Worldwide Medications for Cutaneous Mastocytosis Market report is the difference between hypothesis and executable plan. The report consolidates the data, scenarios and tactical playbooks you need to make high‑confidence decisions in a market growing toward USD 170.57 Million by 2032 at a 5.15% CAGR. To obtain the detailed segmentation tables, company models, and our recommended 18‑month implementation timeline, visit the PW Consulting report page or contact our industry practice for a briefing and licensing options.
PW Consulting — translating specialized market insight into strategic action for rare‑disease portfolios navigating the next wave of clinical and commercial change.
For detailed analysis of this topic, please visit the official page: Worldwide Medications for Cutaneous Mastocytosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com