

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Luxury Car Coachbuilding Market to Grow at 9.15% CAGR (2026–2032), Rising from USD 1,150 Million in 2025 to USD 2,122.6 Million by 2032

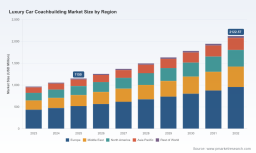
Worldwide Luxury Car Coachbuilding Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting's latest market study on Worldwide Luxury Car Coachbuilding provides a rigorous, forward-looking intelligence package designed to guide executives, investors, and product strategists as they set priorities for 2026. The market has moved from USD 965.8 Million in 2023 to USD 1,150.0 Million in 2025 and — driven by electrification, material innovation and renewed client appetite for hyper-personalization — is forecast to exceed USD 2,122.6 Million by 2032. Our modelling shows this evolution will be powered by a robust compound annual growth rate of 9.15% over the 2026–2032 forecast window.
Worldwide Drone Data Management Market
Why this study matters to 2026 strategy
Coachbuilding is no longer a niche artisan sideline. OEMs, luxury marques and independent ateliers are treating bespoke bodywork, limited coachbuilt series and re-body projects as strategic levers for margin expansion, client loyalty and brand halo. That transition creates an unusually rich set of near-term choices for companies deciding where to place capital, how to structure partnerships, and when to scale production capabilities. Our study translates high-level market momentum into practical decisions for 2026 planning cycles:
Worldwide GPS Anti-Jamming Market
- Quantified top-line trajectory and market concentration metrics that clarify which parts of the value chain warrant direct investment or selective partnership.
- Operational guidance on manufacturing and materials choices that balance traditional handcraft with higher-volume, repeatable processes.
- Commercial playbooks that show how to monetize ultra-luxury scarcity—limited runs, invite-only programs and multi-year client journeys—without undermining brand exclusivity.
What the report delivers (practical contents)
The report was compiled with a mixed-methods approach: primary interviews with coachbuilders, OEM strategy executives and raw-material suppliers; bottom-up project accounting of recent coachbuild commissions; and scenario-based financial modelling. Key deliverables include:
Worldwide Vector Graphics Software Market
- Executive summary with decision-ready implications for OEM C-suite, private equity and independent coachbuilders.
- Market sizing and demand modelling: historical view (2020–2025) and forecast scenarios (2026–2032) under base, upside and regulatory-tightening assumptions.
- Go-to-market playbooks: product-platform decisions, client-segmentation approaches, configurable pricing templates and limited-series production economics.
- Manufacturing and materials annex: strategic choices between traditional hand-formed aluminium workflows and modern composite/carbon-fibre processes, tooling strategies, and supplier qualification checklists.
- Commercial partnerships and M&A framework: diligence templates, valuation sensitivities and partnership archetypes tailored to coachbuilding deals.
- Risk and compliance module: emissions-driven constraints, homologation issues for re-bodied vehicles and supply-chain resilience measures.
- Case studies and project dossiers: anonymized P&Ls and timelines from notable coachbuilt programs to illustrate typical margin profiles and capex rhythms.
Market structure and competitive dynamics
The coachbuilding market combines a heavy vintage of artisanal skill with a rapidly professionalizing commercial layer. Concentration is meaningful — the report’s competitive analysis shows that the top three players capture roughly 62.4% of market value, while the top five approach about 81.15% — indicating a dual landscape of dominant brand-led coachbuilders and a fragmented long tail of specialist studios and tuners.
Key archetypes profiled in the study include:
- Legacy luxury manufacturers extending in-house coachbuild divisions to reconquer high-net-worth customers demanding one-off programs and curated client experiences.
- Independent Italian and British ateliers specializing in handcrafted aluminium and composite coachwork with bespoke engineering services.
- High-performance rebody houses and tuners focusing on carbon-fibre widebodies and full-conversion projects where engineering and speed-to-market matter.
The report contains robust company profiles and a competitive map covering the leading names in the sector, including Rolls-Royce Motor Cars (Goodwood), Bentley Mulliner (Crewe), Pininfarina (Turin), Carrozzeria Touring Superleggera (Milan), Zagato, Aston Martin’s Q Division, Ferrari’s Special Projects, Mansory, Brabus, Ares Design, Pagani, Koenigsegg and several specialist studios. For each, we evaluate capability clusters (design, engineering, materials expertise), production capacity, client-program mechanics and likely strategic moves through 2028.
Recent developments that shape 2026 decisions
Our research highlights an accelerating push from legacy OEMs into curated coachbuild offerings. Notable among 2026 developments is the launch of a new invite-only Coachbuild Collection by a major marque, coupled with the reveal of a limited-run coachbuilt EV developed in collaboration with select clients. These moves crystallize two important strategic takeaways:
- Bespoke EV programs will be a differentiator for brands that can marry bespoke craftsmanship with credible electrified platforms.
- Client experience programs — multi-year relationships, concierge commissioning and post-delivery lifestyle services — are becoming as important as the vehicle itself for value capture.
Material and manufacturing trends (implications, not tabulation)
Material choice is a strategic decision with commercial, regulatory and talent implications. The industry remains rooted in hand-formed aluminium for many coachbuilding traditions, but composites — particularly high-performance carbon solutions — are increasingly adopted where lightweighting and sculptural freedom deliver competitive advantage for limited-series and performance-oriented builds. The report provides a decision matrix that maps material choices to price points, lead times, supplier pools and compliance pathways without disclosing proprietary segment-level shares.
Five priority actions for 2026
Based on the data and scenario work, PW Consulting recommends five prioritized actions for executives preparing 2026 plans:
- Define your coachbuilding ambition: Decide whether coachbuilding is a margin lever, brand halo program or client-lock strategy. This decision should determine capital intensity, factory footprint and partnership model.
- Invest selectively in materials capability: Build in-house composites competence or secure preferred-supplier agreements to guarantee capacity for limited series and high-complexity projects.
- Create a staged EV coachbuilding playbook: Align bespoke programs to electrified platforms early to avoid late-stage integration costs and to position coachbuilt EVs as premium halo products.
- Design client-experience economics: Formalize subscription-like or multi-year concierge programs that convert single-vehicle commissions into recurring-revenue relationships.
- Use the concentration dynamics: If you are a challenger, leverage agility and lean engineering to capture niche commissions; if you are an incumbent, consider bolt-on acquisitions to round out materials or program-management capability.
How the report supports M&A, JV and investment decisions
For investors and corporate development teams, the study provides market-sizing by vintage, scenario-based revenue multiples, and integration risk matrices. Our bottom-up modelling shows likely payback windows for greenfield coachbuilding lines, acquisition price bands for target attritions, and sensitivity to raw-material price swings and regulatory tightening — all calibrated to inform term-sheets and integration plans in 2026.
Accessing the full intelligence
This commentary is designed as a strategic preview: it demonstrates the depth of our analysis and the practical outputs you can expect, while preserving the proprietary segmentation, client-level casework and downloadable financial models that make the study actionable. PW Consulting’s full report includes granular segmentation, regional and application breakdowns, supplier scorecards and downloadable Excel models for bespoke scenario testing. Those detailed datasets and playbooks are available via the PW Consulting report page.
For 2026 planning cycles, PW Consulting’s Worldwide Luxury Car Coachbuilding Market study is positioned to be a reference tool for executive decision-making — combining precise top-line forecasts, competitive mapping and execution-ready guidance to help firms convert bespoke craftsmanship into sustainable commercial advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Luxury Car Coachbuilding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com