

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Piriformis Syndrome Market to Reach USD 320.96 Million by 2032

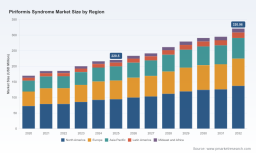
Worldwide Piriformis Syndrome Market — Strategic Insights and 2026 Playbook
Executive summary
PW Consulting’s latest market intelligence brief on the Worldwide Piriformis Syndrome Market—anchored on a 2025 base year and a 2026–2032 forecast horizon—equips executives, investors, clinical leaders, and portfolio strategists with the evidence and frameworks required to make decisive moves in 2026. The market has expanded steadily through the early 2020s, growing from a measured base in 2020 to a more mature position in 2025, and our projections show continued expansion through 2032 at a compound annual growth rate (CAGR) of 5.51% (USD, revenue in Million). By 2032 the market reaches a materially larger scale than in 2025, validating both investment and innovation opportunities across therapeutics, interventional procedures, devices, and care delivery models.
Ground Fault Circuit Interrupter (GFCI) Products Market
Why the 2026 decision window matters
-
Convergence of clinical innovation and reimbursement clarity: 2024–2026 has seen several pivotal clinical publications, device promotions, and payer-guidance updates that together change the economics and clinical decision-making matrix for piriformis care.
Worldwide Continuous Rotary Extrusion Equipment Market -
Shifting modality mix: Minimally invasive and device-enabled modalities are transitioning from niche to scaled options alongside established conservative and pharmacologic care pathways—creating attractive adjacency plays for device makers, pharma companies, and specialty clinics.
Worldwide Speed Gate Market -
Market structure conducive to differentiation: Market concentration metrics show a moderately fragmented environment—enough room for leading incumbents to defend positions while also allowing new entrants to capture meaningful share with differentiated clinical and reimbursement strategies.
What our report delivers — practical intelligence for 2026
-
Comprehensive market sizing and 2026–2032 forecasts built from 2020–2025 historicals: Our models reconcile epidemiology, clinical utilization, procedure adoption curves, and payer dynamics to produce revenue forecasts denominated in USD (Million).
-
Actionable scenario frameworks: Three investment-grade scenarios (Conservative, Base, and Accelerated Adoption) delineate revenue, margin, and risk tradeoffs tied to clinical trial outcomes, payer coverage decisions, and device uptake rates.
-
Payer and coding playbook: A step-by-step guide to engage payers and navigate billing pathways (including recent Centers for Medicare & Medicaid Services guidance and local coverage considerations) to accelerate reimbursement and limit time-to-revenue.
-
Clinical evidence matrix: An indexed repository of randomized trials, registry data, and real-world evidence mapped to each treatment modality—enabling product teams to prioritize evidence generation and label expansion strategies.
-
Go-to-market roadmaps for three archetypes—innovator device, branded pharmaceutical, and digital therapeutics—covering channel strategy, pricing and contracting, key opinion leader (KOL) activation, and service bundling.
-
M&A and partnership scoring tool: A reproducible framework for screening targets and structuring deals that unlock clinical pipeline synergies, accelerate market access, or extend geographic reach.
Competitive landscape — who is shaping the market
The competitive field spans specialized surgical innovators, global pharmaceutical houses, device manufacturers, and emerging digital-health players. Several companies and developments define the near-term strategic terrain:
-
Deuk Spine Institute (United States) — A clinical innovator promoting a patented, minimally invasive release procedure marketed as a permanent solution performed through a small outpatient incision. The safety messaging and real-world procedural volume are positioned to influence surgeon adoption and referral pathways, particularly for refractory cases.
-
Allergan (AbbVie) (United States) — Continues to leverage its onabotulinumtoxinA portfolio as an adjunct therapy for muscle spasm and nerve compression scenarios. Established clinician familiarity and label adjacency make toxin-based strategies a durable component of therapeutic mixes.
-
King Brand Healthcare Products (United States) — Provides specialized cold/heat therapy wraps and targeted recovery products, demonstrating that durable, non-pharma adjuncts can capture clinician and patient mindshare when supported by focused marketing and distribution in musculoskeletal specialty settings.
-
Large pharmas and generics (Bayer, Novartis, Sanofi, Teva, Endo) — These firms supply the pharmacologic backbone (NSAIDs, muscle relaxants, analgesics, generics) for conservative care. Their scale in manufacturing and distribution is a key barrier for newer entrants seeking to capture share in commoditized drug segments.
-
Device and digital entrants (Omron, Hinge Health and others) — The rising presence of wearable TENS devices and digital therapeutic platforms signals an expanding, lower-friction pathway to patient engagement and longitudinal outcome tracking—critical for payers seeking cost-effective alternatives to high-cost interventions.
Recent public developments have immediate strategic implications: clinical trial publications comparing injection vs. shockwave therapies, promotional activity around patented surgical releases, and continued listing updates for comparative therapy trials all affect adoption timelines and evidence thresholds for payers and providers.
Regulatory, coding, and reimbursement dynamics
-
Billing and coding guidance from CMS clarifies the clinical rationale for image-guided versus landmark-based injections, which reshapes procedure cost structures and provider workflows.
-
Medicare Local Coverage Determinations have signaled that botulinum toxins can be considered reasonable for certain refractory indications—creating a defined pathway for off-label but evidence-supported use that can materially affect commercial strategies for toxin manufacturers and proceduralists.
-
FDA approvals across multiple botulinum toxin products establish an evidentiary foundation that vendors can reference in payer conversations, although specific coverage still hinges on local decision-makers and published outcomes.
Strategic implications — a recommended 2026 playbook
-
Prioritize evidence generation tied to payer endpoints. Payers are increasingly demanding outcomes-based proof. Allocate early R&D spend to trials that capture functional outcomes, reductions in downstream imaging or opioid use, and real-world durability.
-
Engage coding and reimbursement teams early. Establish precedents with regional payer bodies and secure pathway documentation (LCDs, CPT positioning) to shorten time-to-revenue for interventional and surgical offerings.
-
Form channel partnerships to accelerate adoption. Device and digital innovators should pursue alliances with specialized clinics and outpatient surgical centers, while pharma companies can leverage hospital networks and pharmacy channels to maximize penetration.
-
Bundle services to differentiate. Integrated offerings—combining procedural solutions with post-procedure digital rehab or device-enabled recovery—create a defensible commercial proposition and offer measurable outcomes for payers and employers.
-
Target selective geographies and provider segments in phased rollouts. Use the report’s scenario models to align resource allocation with expected adoption curves and reimbursement milestones rather than attempting uniform global launches.
-
Prepare contingency plans for variable uptake. Map sensitivities in your financial models to clinical evidence setbacks, coding delays, or competitive patent enforcement to maintain strategic flexibility.
Risk assessment and scenario triggers
Three principal risk vectors should inform 2026 prioritization:
-
Clinical risk — negative or inconclusive comparative studies could delay adoption of new interventional approaches; conversely, positive randomized data accelerate payer acceptance.
-
Reimbursement risk — variance in regional coverage decisions and coding interpretations can create asymmetric rollouts; firms that secure favorable local coverage earliest gain first-mover advantage.
-
Competitive risk — incumbents with broad pharmaceutical portfolios and deep distribution may defend conservative treatment channels; innovators must rely on differentiated clinical value or bundled service economics to penetrate those channels.
How leaders should use this intelligence in 2026
-
Board and investor committees: Use the report’s scenario outputs and M&A scoring to evaluate buy-versus-build decisions and to set capital allocation priorities for 2026.
-
Commercial and market access teams: Deploy the payer playbook and coding guidance to shorten negotiation cycles and to define pilot geographies for rapid-proof cases.
-
R&D and clinical affairs: Align trial design with payer-valued endpoints from the outset, and incorporate pragmatic, real-world evidence collection into product launches.
Limitations and next steps
Consistent with the “trailer” approach, this release highlights strategic direction, key drivers, and recommended actions while intentionally omitting segmented revenue breakdowns and detailed region-by-region figures to preserve the full analytical value for subscribers. The full report contains granular segmentation, provider and channel-level revenue models, and downloadable financial workbooks that support internal decision modeling.
Conclusion
For 2026, the Worldwide Piriformis Syndrome Market presents a balanced landscape of growth and differentiation. A disciplined focus on evidence, payer engagement, and integrated offering design will allow companies to convert the market’s steady CAGR into durable revenue streams and clinical leadership. PW Consulting’s full report provides the granular data and executable playbooks needed to navigate the next 18–36 months with conviction.
To access the full dataset, segment analytics, and downloadable scenario models, please consult the official report release on PW Consulting’s distribution channels.
For detailed analysis of this topic, please visit the official page: Worldwide Piriformis Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com