

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 5.29% CAGR for Worldwide Cold‑Formed Steel Frame Market Through 2032

Worldwide Cold-Formed Steel Frame Market — Strategic Outlook for 2026 Decision-Makers
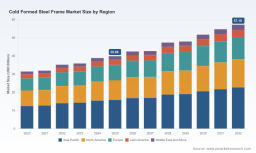
As organizations prepare planning cycles and capital allocations for 2026, cold-formed steel (CFS) framing has moved from niche specification to core building-system consideration across commercial, residential, and industrial construction. PW Consulting’s new Worldwide Cold Formed Steel Frame Market report (base year 2025, historical 2020–2025, forecast 2026–2032) equips senior executives, product strategists, procurement leads and private equity investors with the market intelligence required to convert 2026 uncertainty into competitive advantage. Our bottom-line: the global market continues to expand at a steady pace (compound annual growth rate of 5.29% through the forecast window) and is projected to increase from an estimated USD 39.86 Billion in 2025 to approximately USD 57.19 Billion by 2032 — a trajectory with clear winners and losers depending on strategic choices made this year.
Current Limiting Power Fuses Market
Why 2026 is a Strategic Inflection Point
-
Regulatory alignment and technical standards are tightening. Industry bodies released major updates that materially affect design compliance, specification language and competitive differentiation. Notably, the Steel Framing Industry Association released its 2025.1 Technical Guide aligning cold-formed steel practice with the 2024 International Building Code and recent state codes; while the Steel Deck Institute updated the ANSI/SDI AISI S100 specification in 2024. These changes influence product validation timelines, certification costs, and time-to-market for new system introductions.
Worldwide Car Sensors Market -
Input-cost volatility is higher. Hot-rolled coil (HRC) prices — the primary feedstock for CFS — have moved decisively upward in early 2026, pressuring margins, changing procurement windows and favoring vertically integrated or hedged supply chains. Procurement strategies that ignore short-term price elasticity risk either margin compression or loss of competitiveness in bid markets.
Worldwide Key-Value Stores Market -
Sustainability is now a procurement gate. Buyers increasingly require Environmental Product Declarations (EPDs) and lifecycle data for low‑embodied-carbon claims; suppliers publishing cradle-to-gate EPDs are actively differentiating in tenders and green building programs.
-
Prefabrication, automation and digital design sharpen value propositions. Off-site fabrication, software-enabled detailing, and high-strength steels allow faster program delivery and better material efficiency — attributes that matter most for mid-rise, modular, and data-center projects where schedule and repeatability are priorities.
Practical Strategic Imperatives for 2026
Executives who treat 2026 as a window for capability building — not merely a year to manage cost pressure — will increase market share and long-term margins. Key imperatives we advise clients to prioritize:
-
Procurement & input management: institute hedging and index-linked contracts for coil purchases; develop dual-sourcing strategies across geographies to reduce single-supplier exposure; evaluate vertical integration where capital and volume justify it.
-
Product & compliance playbook: fast-track certification against new code editions; invest in standardized EPDs and test data packages to shorten bid cycles; offer pre-certified system solutions for critical project types.
-
Factory & digital transformation: deploy roll-forming automation, design-to-fabrication workflows and BIM-level integrations to reduce labor content and accelerate project handover for repeatable project segments.
-
Commercial & go-to-market: build bundled value propositions (engineering + supply + installation) for mid-rise and modular customers; introduce performance-based warranties tied to lifecycle carbon benefits for large public and institutional buyers.
-
M&A and portfolio optimization: target tuck-ins that expand regional fabrication footprint or add differentiated sustainability credentials; deploy bolt-on acquisitions to close capability gaps in digital design and prefabrication.
What PW Consulting’s Report Delivers — Operational & Actionable
The report was designed to be directly usable in boardrooms and corporate planning sessions. Highlights of the deliverables include (select list):
-
Market model (historical 2020–2025; base year 2025) and three forward scenarios (baseline, downside, upside) for 2026–2032 that isolate demand drivers, elasticity to construction activity, and sensitivity to coil price swings.
-
TAM/SAM/SOM framework and go-to-market playbooks by application and product family (note: detailed regional and application share tables are intentionally withheld from this release and available in the full report).
-
Cost & margin benchmarking with bill-of-materials estimates, roll-forming throughput productivity metrics, and route-to-market margin waterfalls for OEMs, roll-formers, and prefabricators.
-
Regulatory and standards matrix highlighting timelines and compliance requirements resulting from the SFIA 2025.1 update and the SDI AISI S100-2024 revision — critical for product roadmaps and certification prioritization.
-
Sustainability playbook including an EPD implementation checklist, supplier engagement templates, and carbon-intensity benchmarking for cradle‑to‑gate comparisons.
-
Company-level profiles, capability maps and a proprietary vantage dataset of commercial wins and project archetypes; model-ready Excel deliverables enable bespoke scenario testing for investment committees.
Competitive Landscape — Who Matters and Why
The CFS framing ecosystem spans global steel majors, specialized roll-formers, system integrators and niche innovators. Overall market concentration remains low — CR3 and CR5 metrics indicate a fragmented industry — which keeps competitive dynamics intensely local and innovation-driven. Strategic positioning falls into three archetypes:
-
Upstream steel producers and coil suppliers: companies such as Nucor Corporation (Charlotte, NC), ArcelorMittal (Luxembourg), Tata Steel (Mumbai), SSAB (Stockholm) and BlueScope (Melbourne) supply critical input materials. Their scale, logistics footprint, and pricing discipline materially affect downstream cost structures and availability.
-
Roll-formers and system manufacturers: ClarkDietrich Building Systems and CEMCO (California Expanded Metal Products) are examples of large, code-focused North American manufacturers supplying studs, tracks and integrated systems. Metsec (voestalpine) and Hadley Group serve European and global markets with precision roll-forming capability. These firms win through product breadth, code compliance and distributor networks.
-
Specialists, innovators and integrators: FRAMECAD (New Zealand) brings software-enabled rapid construction systems; MarinoWARE and MRI Steel Framing emphasize low-embodied-carbon systems and EPD transparency; The Steel Network and Eisen Group are notable for connectors, prefabrication and project-level integration. These players obtain higher margins where speed, sustainability or project integration matter.
For executives, the strategic takeaway is clear: upstream relationships and supply assurance are table stakes, but differentiated growth is won through system-level integration, sustainability credentials and digital-enabled prefabrication. The full report profiles each key company and maps capabilities to project archetypes — information essential for competitor benchmarking and M&A screening.
Recent Developments to Watch in 2026
-
Standards & industry recognition — SFIA’s 2025.1 Technical Guide and SDI’s AISI S100-2024 update are reshaping design practice and procurement checklists; SFIA’s 2025 awards signaled which suppliers lead on code-compliant, high-profile projects.
-
Market & trade activity — trade shows and sector events remain key intelligence venues: major exhibitors will use BUILD26 and regional expos to demonstrate full-system compliance and prefabrication capabilities.
-
Raw material pricing — HRC price levels and recent year-over-year increases have immediate procurement and bidding implications. Leaders are locking long-term contracts or adding pass-through mechanisms into customer pricing.
-
Sustainability acceleration — suppliers publishing verified EPDs (notably select MarinoWARE and MRI product lines) are beginning to secure public-sector and high-performance commercial volume.
How to Use This Intelligence in 90 Days
-
Procurement: run a 60–90 day supplier stress test using our sensitivity tables to determine how contract terms perform if HRC prices move ±15%.
-
Product: prioritize certification and EPD publication for your top three product lines; reduce bid cycle time by pre‑assembling test and certification dossiers.
-
Commercial: pilot two bundled offers (supply + prefabrication + installation warranty) targeted at high-volume mid-rise or modular contractors to evaluate price elasticity and margin uplift.
PW Consulting’s Worldwide Cold Formed Steel Frame Market report is intentionally rich in operational detail while preserving strategic confidentiality for premium subscribers. If your 2026 planning requires robust market sizing, scenario-based financial models, competitor revenue estimates, regional and application splits, and supplier benchmarking, the full report and supporting Excel models are available on our website. Our team is also scheduling a limited number of bespoke briefings in Q3 2026 to walk executive teams through tailored implications for procurement, product roadmaps and M&A pipelines.
Contact PW Consulting to schedule a briefing and obtain access to the full dataset, or visit our report page for purchase and licensing options. Use this year to convert standards change, input volatility and sustainability requirements into a durable commercial advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Formed Steel Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com