

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting 2025 Report Predicts Worldwide Metal Fabrication Outsourcing Market to Expand at a 5.29% CAGR Through 2026–2032

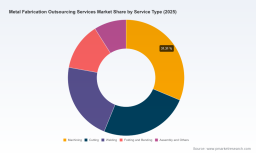
Worldwide Metal Fabrication Outsourcing Services Market — Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present an executive synthesis of our latest market study: Worldwide Metal Fabrication Outsourcing Services Market (Base year: 2025; Historical: 2020–2025; Forecast: 2026–2032). This briefing distills the strategic takeaways that should shape executive decision-making in 2026 — procurement, operations, corporate development, and capital allocation — while preserving the granular segmentation and vendor-level data for subscribers who require direct access to the complete intelligence set.
Worldwide Classroom Messaging Software Market
State of the Market: A disciplined growth story
The global market for metal fabrication outsourcing services reached approximately USD 84.1 billion in our base year (2025) and is projected to grow at a compound annual growth rate of roughly 5.3% through our forecast window. By 2032, the market is expected to exceed USD 120.6 billion (USD, revenue unit: Million), underscoring steady demand driven by infrastructure renewal, industrial modernization, and capital expenditure cycles across heavy equipment, construction, energy, and defense sectors.
5-leg IV Stand Market
Two structural features define the landscape: first, the market remains fragmented — with the top three and top five suppliers accounting for low double-digit shares — creating persistent opportunities for regional specialists, niche capability providers, and digital marketplace entrants; second, macroeconomic and input-price volatility is reshaping sourcing strategies, investment timing, and contract design more than ever.
Worldwide Java Programming Training Market
Why this report matters to decision-makers in 2026
- Risk-informed sourcing: The study combines forward-looking price sensitivity scenarios with procurement playbooks so sourcing managers can quantify exposure to steel and alloy cycles, freight cost shocks, and labor availability constraints before locking multi-year supply agreements.
- Capex allocation with ROI rigor: We provide ROI and TCO models for onshore vs. nearshore vs. offshore fabrication strategies, and for automation investments (robotic welding, laser cutting, and digital inspection). These models allow operations and finance teams to stress-test investments against alternative labor and commodity futures.
- M&A and partnership playbooks: Corporate development teams will find prioritized capability targets, integration risk matrices, and earnout structures tailored to the sector’s consolidation dynamics — critical for buyers seeking bolt-on scale or suppliers seeking geographic expansion.
- Commercial and pricing intelligence: The report maps prevailing commercial models (fixed-price, cost-plus, unit-rate), identifies levers for margin improvement, and lays out negotiation strategies for long-lead items and surge capacity arrangements.
Practical contents you can deploy immediately
- Proprietary market-sizing and forecast model (Excel) at global and macro-segment levels, ready for sensitivity analysis.
- Supplier playbooks and scorecards that translate capability assessments into RFP templates and vendor due-diligence checklists.
- Automation and reshoring calculators that quantify payback periods under varying labor-cost and steel-price scenarios.
- Regulatory impact summaries and investment heat maps showing where energy-transition and digitalization policy shifts materially change supplier economics.
- Scenario narratives (near-term cyclical, structural reshoring, and accelerated electrification) with recommended strategic responses for buyers and providers.
Competitive dynamics — how leading players are positioning
The supplier landscape blends global engineering conglomerates, regional heavy fabricators, digital marketplaces, and specialized rapid-turn providers. A high-level synthesis of observed strategic postures:
- Integrated heavy-equipment and OEM suppliers (examples include established global machinery and equipment manufacturers) continue to leverage scale, in-house metals capability, and captive demand to offer bundled supply and aftermarket propositions. Their strategic advantage lies in integrated product-engineering depth and the ability to internalize complex welding and casting work streams.
- Dedicated metal processors and foundries are differentiating through capacity for large-scale structural components, compliance with industrial certification regimes, and deep relationships in infrastructure and construction sectors. Scale and reliability are their primary commercial currency.
- Precision and rapid-turn firms (digital-first players focused on low-volume, high-mix production) are competing on speed, digital quoting, and short lead times — capturing prototyping and early-stage production work from OEMs that prioritize time-to-market.
- Marketplace platforms are aggregating global supplier capacity and providing on-demand access to diverse capabilities, compressing lead times and increasing price transparency — a disintermediation risk for small, undifferentiated job shops.
- Regional specialists remain vital in localized supply chains where logistics, regulatory compliance, and supplier proximity are decisive.
Notably, fragmentation persists: market concentration is low, with the top suppliers representing single-digit to low-double-digit shares. That structural fragmentation will sustain acquisition activity as buyers pursue scale, capability fills, and geographic coverage.
Company spotlight — strategic implications from observed activity
- Mayville Engineering Company, Inc. (MEC) — Recent capability expansion through acquisition and investments in light-gauge sheet metal and prototyping signals a strategy to climb the value chain: moving from commodity fabrication into engineering-led enclosure and component work for electronics and industrial OEMs. For acquirers, MEC’s playbook underscores the importance of combining design services with fabrication to capture higher margin work.
- O'Neal Manufacturing Services — Focused on heavy fabrication and structural components, their offerings show how scale in heavy machining and value-added assembly creates stickiness with construction, mining, and industrial machinery customers. Buyers looking for low-risk partners should prioritize suppliers with demonstrable heavy-structure throughput.
- BTD Manufacturing Inc. and regional specialists — Precision sheet-metal and stamping specialists continue to exploit niches in agriculture and recreational vehicle markets where bespoke part families and short-changeover expertise matter.
- ThyssenKrupp, Nucor, Liebherr, XCMG, Caterpillar — These incumbents illustrate two parallel strategies: (a) integration across upstream steel/metal capabilities to secure material flow and cost predictability, and (b) investing in heavy fabrication lines to service captive and external markets. For strategic buyers, the message is clear: vertical integration can be a meaningful competitive moat but requires capital intensity and tight operational execution.
- Protolabs and Xometry — Digital providers are reshaping customer expectations on lead times and quoting transparency. Their competitive advantages are automated quoting engines, distributed supplier networks, and digital order-tracking — capabilities that traditional fabricators must either replicate or partner with to win prototyping and small-batch work.
Sector dynamics that will determine winners and losers in 2026
Four converging forces will be decisive this year:
- Input-price volatility: Recent observations show steel benchmark values and iron-ore trajectories shifting in ways that are likely to compress supplier margins unless commercial terms and hedging practices are updated. Firms that have embedded dynamic indexation clauses or have diversified upstream intake will be better positioned.
- Labor scarcity and automation adoption: Ongoing skilled labor shortages are accelerating investments in robotic welding, automated cutting, and digital quality assurance. Suppliers that execute effective human-plus-automation models will capture labor arbitrage while maintaining quality and throughput.
- Supply-chain realignment: Reshoring and supplier diversification driven by geopolitical risk and tariff volatility are prompting buyers to rebalance sourcing mixes. This will favor regional fabricators with proven compliance and logistics capabilities, and create opportunities for specialist partners to win reindustrialization work.
- Regulatory and energy-transition pressures: Policy emphasis on decarbonization and industrial digitalization is shifting capital toward prefabrication, modular construction, and energy-efficient process upgrades. Firms that can certify low-carbon supply chains and provide digital twins of fabrication processes are advantaged in public procurement and large institutional projects.
How to use the full report — immediate next steps for executives
- Procurement leads: Use our price-sensitivity and contract-play models to rework supplier agreements before the next budgeting cycle. Prioritize clauses that allow pass-throughs or shared-savings on volatile commodities and freight.
- Operations heads: Run the automation ROI calculator across candidate plants to determine upgrade sequencing. Combine results with our labor-availability dashboard to define capital priorities.
- M&A teams: Leverage our target-screening matrix and integration risk assessment to prioritize bolt-on acquisitions that plug capability gaps or provide geographic coverage with low integration friction.
- Investors: Apply our scenario-based valuation overlays for private and public targets to test downside exposure to steel-price shocks and upside from digital commercialization.
Call to action — where to find the rest
This briefing surfaces the strategic contours that PW Consulting has distilled for 2026 decision cycles. The complete report contains the full suite of segment-level forecasts, vendor market shares, and downloadable analytical tools (market-sizing model, supplier scorecards, RFP templates, and scenario simulators) that operational teams and C-suite leaders will need to convert insight into action. To review the detailed regional and application splits, vendor-level financials, and the interactive models, please refer to the PW Consulting market portal and contact our research desk for subscription access.
In an environment defined by steady organic growth, input volatility, and rising automation, organizations that pair pragmatic sourcing reforms with selective strategic investments in capabilities will capture the disproportionate returns. PW Consulting’s study is designed as a practical, executable roadmap for those choices in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Fabrication Outsourcing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com