

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Drill Stabilizer Market to Reach USD 1,342.9 Million by 2032, Growing at a 5.35% CAGR (2026–2032)

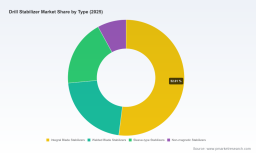
Worldwide Drill Stabilizer Market: Strategic Imperatives for 2026 — Executive Briefing
As PW Consulting releases its authoritative market research on the Worldwide Drill Stabilizer Market, this briefing summarizes the report’s strategic value for executive decision-makers planning for 2026. Our analysis synthesizes five years of historical performance (2020–2025), a rigorous baseline year (2025), and a forward-looking forecast through 2032. The market demonstrated steady expansion through 2025 and, under our base-case projection, is expected to grow at a compound annual growth rate (CAGR) of 5.35% over the forecast window — a trajectory that shapes capital allocation, sourcing strategies, and product development roadmaps in the immediate planning cycle.
Benchtop Vickers Hardness Testers Market
Market snapshot: what the headline numbers mean for 2026
PW Consulting’s topline estimates show the market expanding from a mid‑hundreds million USD footprint in 2020 to a larger baseline by 2025, with our base year capturing the sector’s recovery dynamics and inventory rationalizations after a period of volatility. Our forecast anticipates continuing expansion through 2032, reflecting steady demand in drilling activities, incremental adoption of engineered stabilizer designs, and a renewed emphasis on bottom hole assembly (BHA) optimization across both onshore and offshore programs.
Apron Lighting for Airport Market
- Historical trend recognition (2020–2025): the sector rebounded from pandemic‑era disruptions into a phase of capacity restocking and rental fleet optimization.
- Base year (2025): a pivotal planning reference for 2026 budgets, procurement cycles, and supplier negotiations.
- Forecast implication (2026–2032): the projected mid‑single digit CAGR implies consistent, addressable growth — large enough to justify targeted investment but modest enough to demand disciplined capital allocation and margin protection.
Why this research matters to 2026 corporate strategies
For drill stabilizer manufacturers, rental fleet operators, service companies, and drilling contractors, 2026 will be a year of tactical execution informed by three strategic priorities: operational resilience, product differentiation, and capital efficiency.
Worldwide Veterinary Capital Equipment Market
- Operational resilience: heightened raw material volatility and concentrated supplier relationships will require strengthened procurement playbooks, alternative sourcing, and hedging mechanisms to protect margins.
- Product differentiation: incremental performance gains from materials engineering (e.g., alloy selection and hardfacing processes) and design (integral vs. welded vs. sleeve types, non‑magnetic options) create clear pathways for higher‑margin product tiers.
- Capital efficiency: rental and rebuild strategies will remain central. Firms that optimize fleet utilization and lifecycle refurbishment programs will realize better returns than peers reliant solely on new‑build sales.
Report scope: practical tools for boardrooms and operating teams
The full PW Consulting report is structured to translate industry intelligence into executable plans. Key deliverables included are:
- Proprietary demand model with historical calibration and scenario variants for 2026 budgeting (base, upside, downside).
- Supplier and cost‑build analysis capturing material inputs, manufacturing steps, and margin pools — enabling rapid gross‑margin stress tests under different raw material and labor cost assumptions.
- Competitive benchmarking: supplier scorecards that measure technical capabilities, certification status, fleet scale, and aftermarket service coverage.
- Go‑to‑market blueprints and channel playbooks for OEMs, rebuilders, and rental operators, including pricing levers and commercial structuring options tailored to common contract types in the industry.
- Risk register and mitigation matrix focused on supply chain fragilities (including high‑strength alloy sourcing), regulatory compliance requirements, and demand shocks for 2026 planning horizons.
Segmentation and product strategy (high level)
Our segmentation analysis distinguishes product classes and end‑use contexts without revealing client‑restricted granularity. The market comprises several technical archetypes — integral blade designs, welded blade constructions, sleeve‑type and non‑magnetic variants — each addressing different drilling profiles and BHA objectives. Applications span conventional onshore programs through complex directional and offshore wells.
For 2026, strategic choices hinge on matching product design to customer procurement economics: high‑performance integral designs command premium positioning on complex wells; sleeve and welded options play into cost‑sensitive or heavy‑rotation scenarios where rebuildability is a core advantage. The full report provides the precise segmentation tables and unit economics for buyers and suppliers who require transaction‑level detail.
Competitive landscape: positioning the leaders
The market remains moderately concentrated: our concentration metrics indicate that the top three and top five firms account for a material share of market value — a level that supports coexistence of international specialists and regional manufacturers. Against this backdrop, several firm archetypes are prominent:
- Integrated service providers with in‑house manufacturing and large rental fleets. These players leverage custom‑engineered stabilizers and deployment scale to win complex drilling programs.
- Specialist manufacturers focused on precision metallurgy and API‑compliant tooling, often competing on certification, hardfacing options, and rapid OEM qualification cycles.
- Regional producers and rebuilders that compete on lead times, localized service capabilities, and cost leadership for high‑rotation applications.
Representative firms profiled in the report include Stabil Drill (USA) — notable for custom engineering and a large rental footprint; Drilling Tools International (USA) — with a broad portfolio spanning integral and sleeve types; and several China‑based manufacturers (Vigor Drilling, Landrill, Saigao Group, Welong, Tianhe) that emphasize cost competitiveness, API compliance, and export scale. Gulf States Drilling Supply (USA, Florida) exemplifies the re‑builder model with a focus on durability and aftermarket service. Each profile includes publicly verifiable corporate data, strategic strengths and weaknesses, and recommended engagement strategies for partners and buyers considering alliances, procurement, or M&A.
Industry dynamics and supply‑side pressures
Two structural dynamics will shape 2026 outcomes:
- Raw material and manufacturing inputs: high‑strength alloy steels (commonly specified in supplier technical sheets) and blade hardfacing materials are central to product performance. Price and availability swings in steel markets — including shifts in structural steel and coil pricing, and regional scrap cost variability — materially influence unit economics. Manufacturers with secured long‑term supply or vertical integration will enjoy a competitive cost base.
- Regulatory and technical standards: API standards for rotary connections and material specifications remain the baseline for procurement. Compliance is a gating factor for participation in major tenders and deepwater programs, and is integrated into the report’s supplier assessment framework.
Operationally, the stabilizer’s role in the BHA — in trajectory control, vibration damping, and overall drilling efficiency — continues to be a key driver of adoption. Our field case studies demonstrate how incremental stabilizer improvements can translate to measurable reductions in non‑productive time and total drilling cost per well, a critical economic lever in 2026 contracting environments.
Strategic playbook for 2026
For executives crafting plans next year, PW Consulting recommends a prioritized set of actions:
- Validate supplier contracts against near‑term raw material scenarios; secure conditional commitments or variable pricing clauses to protect gross margins.
- Invest selectively in higher‑value stabilizer designs tied to directional drilling growth; pair product R&D with pilot field deployments to shorten commercialization cycles.
- Lean into refurbishment and rental optimization: extend useful life through standardized rebuild protocols and tighter lifecycle management to improve capital turns.
- Pursue strategic partnerships with manufacturers that combine API compliance and proven hardfacing processes, especially for customers operating in high‑wear environments.
- Use scenario planning to stress‑test investment cases against both demand shocks and supply disruptions; incorporate a contingency budget for expedited freight and material substitution in procurement models.
Recent market signals and what they indicate
Market participants continue to publish product updates and selection guidance that reflect both technical evolution and buyer education. Examples in 2025–2026 include updated product catalogs and technical overviews from specialist suppliers, highlighting the role of engineered stabilizers in borehole management. These public signals corroborate our field interviews that design innovation and supplier transparency are becoming primary commercial differentiators.
Next steps: how to use the full PW Consulting report
The public briefing here surfaces the strategic implications and our core conclusions, but the full PW Consulting report contains the transaction‑grade intelligence that procurement teams, corporate strategy groups, and private investors will need for 2026 decision‑making:
- Detailed segmentation tables and unit‑level forecasts by product class and application (available in the subscriber dataset).
- Supplier scorecards with API certification status, production capacity estimates, and suggested engagement models.
- Scenario financials and sensitivity matrices suitable for board review and investment committee use.
Contact PW Consulting to access the full dataset, model files, and an executive briefing tailored to your organization’s exposure to the drill stabilizer value chain. The report is designed as a strategic toolkit: enough depth to inform 2026 capital and procurement choices, and structured to preserve commercially sensitive segmentation detail for authorized users.
For detailed analysis of this topic, please visit the official page: Worldwide Drill Stabilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com