

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Oil Hose Market to Grow at a 4.8% CAGR, Report Shows

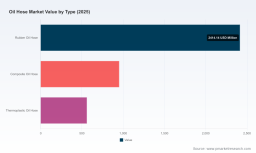
Worldwide Oil Hose Market 2026: Strategic Playbook for Resilient Growth
Executive summary
PW Consulting’s new market study, published with a 2025 base year and a 2026–2032 forecast window, delivers an operationally oriented view of the Worldwide Oil Hose market. Our bottom‑up model — denominated in USD (Million) — shows the market expanding from approximately 3.93 billion USD in 2025 to roughly 5.45 billion USD by 2032, implying a compound annual growth rate (CAGR) of 4.8% across the forecast horizon. The profile from 2020 through 2025 captures the pandemic trough and subsequent recovery, while the 2026 near‑term dynamics reveal transient softness before a steadier upswing through 2032.
Fixed Flow Anesthesia System Market
Why this report matters for 2026 decisions
Senior executives and strategy teams face three intertwined strategic challenges in 2026: (1) margin pressure from raw‑material volatility, (2) evolving specification and compliance demands from offshore and bunkering customers, and (3) an industry structure characterized by global majors coexisting with highly capable regional specialists. This report translates those macro realities into executable options: capital allocation priorities, go‑to‑market pivots, supply‑chain hedges, and targeted M&A screens. We intentionally surface the strategic contours and validated hypotheses here while reserving granular sub‑segment tables and supplier scorecards for the full report — designed to be used in boardroom decisions and investor diligence.
Worldwide Industrial Plastic Pallet Market
Market dynamics and inflection points
-
Demand fundamentals — The market is underpinned by persistent needs in exploration & production, marine bunkering, transportation, and industrial fluid transfer. Safety, abrasion and chemical resistance, and standards alignment (including common industry standards for fuel and mineral oil delivery) remain primary purchase drivers for end users.
Worldwide Orchard Tractor Market -
Raw‑material volatility — Input cost trajectories are a near‑term operational risk. Recent commodity signals include a substantial YoY spike in synthetic rubber indices and recurring upward pressure on nitrile compounds. These movements are amplifying unit cost volatility and require manufacturers to adopt tighter pass‑through mechanisms, dynamic pricing, or longer‑term supply contracts to protect margin.
-
Technical and regulatory complexity — End‑market customers increasingly demand certified hoses that meet internationally recognized standards for chemical resistance and fueling operations. Compliance is now a de‑facto market access requirement in many offshore and aviation refuelling contexts, raising the bar for testing capabilities and product documentation.
-
Structural character — Competitive intensity is mixed: several multinational engineering and component businesses provide broad portfolios and global distribution, while nimble regional manufacturers capture niche and large‑bore applications. Aggregate concentration metrics indicate meaningful room for consolidation and margin improvement through scale and specialization.
Competitive landscape — strategic implications
The competitive set spans large diversified industrials with integrated distribution networks and focused hose specialists with deep technical IP. Key players include established multinational suppliers that emphasize global availability, product breadth and aftermarket services; European and North American firms that invest in certification and testing; and specialized manufacturers that own unique capabilities in thermoplastic reinforcement, large‑bore hand‑built rubber, or dedicated oil‑field hose lines.
-
Global industrial OEMs and component conglomerates: These firms leverage scale to serve OEMs and marine end users, compete on warranty and reliability, and push into aftermarket services and digital condition monitoring. Their strategic playbooks emphasize vertical integration, long‑term OEM contracts, and geographic footprint optimization.
-
Specialist hose manufacturers: These players differentiate on bespoke engineering (e.g., large ID, high pressure, or specialty liners), rapid customization, and localized service. They are natural acquisition targets for larger players seeking to fill technical gaps or gain regional access.
-
Regional and low‑cost suppliers: Price sensitivity in commodity hoses supports a two‑tier market. Cost leadership helps win volume in lower‑spec segments, but standards‑driven contracting and end‑user risk aversion limit penetration in high‑spec offshore and aviation flows.
For buyers and investors, three tactical observations follow: (1) scale and distribution still matter for large capital projects and bunkering networks; (2) certification capabilities materially increase competitive advantage for offshore/refuelling contracts; and (3) proprietary thermoplastic and composite solutions offer the best margin expansion opportunities if supported by testing and long‑term supply relationships.
What’s inside the PW Consulting report — practical, actionable content
The full study is structured to support decision cycles across procurement, product management, corporate development and operations. Highlights include:
-
Validated market sizing and a year‑by‑year revenue model from 2020 through 2032 (USD, Million) with scenario overlays to stress‑test assumptions.
-
Unit‑cost and margin sensitivity analysis driven by raw‑material price scenarios and supply disruptions, including quantified impacts from recent rubber and nitrile price shocks.
-
Regulatory and standards matrix linking product families to certification pathways and test requirements — a practical checklist for R&D and quality teams.
-
Supplier benchmarking and capability maps (technology, certifications, manufacturing footprint), presented as a decision tool for sourcing and M&A prioritization.
-
Commercial playbooks for aftermarket monetization, OEM partnerships, and project tendering — including KPI templates and channel margin models.
-
An M&A screen and valuation toolkit focused on bolt‑on targets that accelerate entry into high‑margin niches or add strategically located manufacturing capacity.
We purposefully do not reproduce segment‑level revenue shares or sensitive supplier scores in this release — those are contained in the report’s appendices and interactive data dashboards that accompany the full deliverable.
Prioritized recommendations for 2026 planning
-
Hedge input‑cost exposure: Establish multi‑year supply agreements or index‑linked pricing for key elastomers and polymers. Short‑term hedges and supplier development programs will protect margins while preserving flexibility for product improvement.
-
Invest in certification capacity: Allocate CAPEX to in‑house testing and certification labs or co‑invest with accredited partners. Faster certification cycles reduce time‑to‑market for high‑value offshore and refuelling contracts.
-
Prioritize composites and thermoplastic R&D where weight, chemical resistance and lifetime cost advantage are clear. Target product roadmaps that replace low‑margin rubber SKUs in high‑spec applications.
-
Lean into aftermarket services: Extend product life through inspection programs, predictive maintenance services and digital condition monitoring; these generate recurring revenue and differentiate suppliers beyond price.
-
Execute selective consolidation: Use disciplined M&A to acquire specialized technologies (e.g., large‑bore hand‑built capacity or reinforced thermoplastic capabilities) and to achieve regional scale in fragmented markets.
-
Localize critical capacity: Near‑market manufacturing reduces lead times and exposure to freight dislocations — essential when prize contracts demand short delivery windows and documented provenance.
-
Embed pass‑through clauses and dynamic pricing: Protect margins against commodity spikes while maintaining customer relationships through transparent mechanisms.
How PW Consulting’s data and tools accelerate implementation
Beyond strategic recommendations, the report provides executable artifacts: downloadable Excel models, procurement negotiation templates, a prioritized M&A target list with preliminary valuation ranges, and a certification cost calculator to inform CapEx decisions. We pair quantitative forecasts with practitioner playbooks — not just what’s changing, but how to operationalize the change across procurement, engineering and commercial teams.
Conclusion and next steps
The oil hose market in 2026 is a classic mix of cyclical demand and structural evolution — mid‑single‑digit CAGR through 2032, pockets of premiumization driven by standards and specification, and a competitive landscape that rewards both scale and engineering differentiation. PW Consulting’s study is intended as the working dossier for leaders who must make informed, time‑sensitive decisions this year.
To examine the full dataset, sub‑segment tables, supplier scorecards and the tactical playbooks referenced here, please consult the Worldwide Oil Hose Market report page on the PW Consulting website. The complete package is designed to be used directly in strategy workshops, procurement negotiations and M&A diligence.
For detailed analysis of this topic, please visit the official page: Worldwide Oil Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com