

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Optoelectronic Market to Grow at 13.85% CAGR, Reach USD 15,495.7 Million by 2032

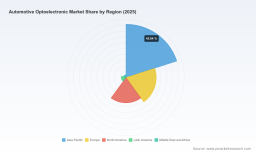
Worldwide Automotive Optoelectronic Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s latest market study, Worldwide Automotive Optoelectronic Market, delivers a focused, actionable viewpoint designed to inform strategic decisions in 2026 and beyond. The optoelectronics stack — encompassing LEDs, laser diodes, image sensors, infrared emitters/detectors, VCSELs, and optical interconnects — is now a core determinant of vehicle differentiation, safety certification, and manufacturing footprint. This preview surfaces the high‑level trajectories, competitive dynamics, regulatory inflections, and practical levers that senior executives, product strategists, and corporate development teams must factor into capital allocation and partnership choices this year.
Worldwide Channel Marketing Management Software Market
Market trajectory at a glance
After a recovery phase in the early 2020s, the automotive optoelectronic market is at an inflection point. PW Consulting’s modeling shows a market value of approximately USD 6.25 billion in the base year (2025). With an underlying compound annual growth rate (CAGR) of 13.85% through the 2026–2032 forecast horizon, the market ramps materially — crossing into multibillion‑dollar scale as advanced driver assistance systems (ADAS), LiDAR, matrix lighting, and increasingly software‑defined vision architectures penetrate mainstream vehicle segments. By 2032 the sector approaches the higher end of the forecast envelope as camera‑based safety mandates, adaptive lighting, and in‑vehicle optical networks mature.
Retail Soft Tags Market
Why 2026 is a strategic inflection year
-
Regulatory deadlines and standards harmonization are converging. Legislated camera mandates in major markets and more granular ASIL requirements are compressing product development cycles and elevating compliance costs.
Worldwide Cloud Financial Close Solutions Market -
Component roadmaps are shifting from single‑function devices to integrated optical subsystems — creating a premium for suppliers that combine semiconductor capability with optics, packaging, and system‑level validation.
-
Geopolitical incentives and industrial policy are changing capital allocation. Subsidies and national‑level fabrication programs are reshaping where capacity will be built and which partners are viable for resilience‑focused supply strategies.
Key growth drivers and technology priorities
-
Safety and autonomy: Camera and time‑of‑flight sensors for automated braking and situational awareness remain the largest structural demand drivers. System redundancy and higher resolution at vehicle‑level sensing are driving migration to stacked and global‑shutter architectures.
-
Lighting as software: Matrix beam headlights and pixelated laser or LED arrays (recently showcased by market leaders) are transforming lighting from a commodity to a safety and UX differentiator — creating opportunities for higher ASPs and new supplier relationships.
-
LiDAR and VCSELs: Short‑ and mid‑range LiDAR adoption, combined with VCSEL arrays for cabin sensing and gesture control, is expanding the component set required in contemporary vehicle platforms.
-
Data transport and optics in the vehicle: Optical couplers, fiber connectors, and low‑latency photonic links are entering deeper into vehicle network architectures as bandwidth demands rise.
Competitive landscape — who matters and why
The market displays a moderately concentrated structure: the top three suppliers account for under half of the market, while the top five capture a majority share — a configuration that rewards both technological differentiation and scale in manufacturing. Against this backdrop, a handful of established semiconductor and optoelectronic companies lead by capability, product breadth, or channel access. High‑level competitive themes we identify are:
-
Integrated optoelectronics leaders (example profiles): Companies that combine high‑power LEDs, VCSELs, photodiodes and associated drive electronics are best positioned to supply full headlamp and sensor modules. Recent product introductions in multi‑pixel matrix laser lighting and adaptive LED platforms illustrate how these vendors are moving up the value chain.
-
Image‑sensor specialists: Vendors with automotive‑qualified stacked CMOS sensors and global‑shutter devices are capturing the ADAS camera upgrade cycle. New launches of QVGA global‑shutter devices and “hyperlux” series sensors are evidence of intensified competition on low‑light performance and motion robustness.
-
Lighting component innovators: Companies focusing on high‑efficiency blue/UV lasers and high‑lumen LEDs remain essential for forward lighting and LiDAR source development; trade shows and product showcases have surfaced multiple platform‑level advances preserving their relevance.
-
Connectors and passive optics suppliers: Firms offering fiber optic connectors and vehicle‑grade optical couplers benefit from the slow but steady adoption of photonic interconnects inside vehicle electronic architectures.
PW Consulting’s full vendor profiles evaluate R&D pipelines, qualification timelines (ASIL/ISO 26262 readiness), manufacturing footprint, and supply‑chain exposure. These scorecards are central to procurement and M&A playbooks in 2026.
Regulatory, geopolitical and supply risks that will shift sourcing decisions
-
Regulatory acceleration: Camera‑based safety regulations in major markets have already forced OEM roadmaps toward multiple, certified camera sensors per vehicle. Compliance timelines emphasize validated supply partnerships and documentation practices.
-
ASIL and functional safety: ISO 26262 certification levels impose product design and testing disciplines that increase time‑to‑market for novel optical assemblies. Suppliers without clearly defined ASIL pathways face adoption barriers.
-
Industrial policy and subsidies: National semiconductor initiatives are altering the calculus for where to invest capacity and with whom to partner. Incentive packages for domestic fabrication change the long‑term cost curves for optical semiconductor production.
-
Systemic supply shocks: Recent fab disruptions and regional natural events revealed single‑point risks in key camera and sensor fabs — underscoring the need for dual‑sourcing, inventory strategy, and contingency capacity planning.
-
Raw material and substrate dynamics: Recent stabilization in GaN‑on‑Si pricing after past volatility has eased near‑term margin pressure, but capacity expansions and epiwafer allocation remain watchpoints for capital planners.
Practical content in PW Consulting’s report — what you can deploy immediately
This study is designed as an operational toolkit for executives, not an academic exercise. Key deliverables include:
-
Top‑down demand model with scenario layers — baseline, accelerated ADAS adoption, and substitution cases — to stress test revenue and capacity plans.
-
Supplier scorecards and qualification roadmaps mapping ASIL readiness, automotive grade device availability, and expected time to production‑release for critical optoelectronic families.
-
Go‑to‑market playbooks for OEMs and Tier‑1s explaining partnership archetypes: ODM/Co‑development, licensed optics platforms, and captive‑manufacturing approaches.
-
Technology adoption curves and pricing sensitivity matrices to quantify the revenue and margin impact of moving to matrix lighting, VCSEL cabin sensing, or solid‑state LiDAR sources.
-
Supply‑chain resilience templates: multi‑sourcing strategies, inventory buffers, and near‑shoring decision frameworks calibrated to incentive programs and potential disruption scenarios.
-
M&A and JV heatmaps identifying capability gaps and target profiles that will accelerate platform access or secure critical wafer capacity.
-
Comprehensive appendix with regulatory timelines, test‑protocol checklists for ISO 26262 evidence, and a prioritized list of certification labs and integration partners.
Strategic implications and recommended action items for 2026
-
Prioritize validated suppliers with ASIL pathways. Allocation of engineering resources to vet supplier certification trajectories reduces late‑stage integration risk.
-
Design for dual‑sourcing in critical optical semiconductors. Short‑term investments in qualifying second sources and inventory policies are cost‑effective insurance against regional supply shocks.
-
Invest selectively in vertically integrated modules. Where differentiation is realized (e.g., adaptive lighting or sensor fusion housings), capture more margin by specifying or co‑developing optics + electronics subsystems.
-
Monitor policy windows for localization incentives. Use government subsidy timelines to inform greenfield investments or JV negotiations for wafer/packaging capacity.
-
Align product roadmaps with adoption scenarios. Use PW Consulting’s demand scenarios to set R&D spend cadence and feature‑release sequencing — particularly for camera resolution, global‑shutter adoption, and LiDAR range classes.
-
Prepare M&A playbooks. In 2026, consolidation opportunities will favor acquirers that can integrate optical IP with software stacks and system validation capabilities.
Next steps — where to find the full intelligence
This release intentionally foregrounds strategic conclusions while omitting granular segment‑level tables and geographic splits to preserve the report’s role as a commercial intelligence product. PW Consulting’s full Worldwide Automotive Optoelectronic Market report contains the detailed breakdowns you will need to operationalize the recommendations above: supplier market shares and scorecards, regional demand curves, component‑level forecasts, price and ASP sensitivity, and downloadable financial models ready for scenario analysis.
For purchasing access, bespoke briefings, or to commission a tailored supply‑chain risk assessment aligned to your product roadmap, contact PW Consulting through our Worldwide Automotive Optoelectronic Market report page. Our analysts stand ready to walk through the dataset, validate your internal assumptions, and map a prescriptive action plan for 2026 execution.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Optoelectronic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com