

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Subsea Flowlines Market to Grow from USD 4.8B in 2025 to USD 6.98B by 2032 at a 5.5% CAGR — Latin America and Carbon Steel Lead the Surge

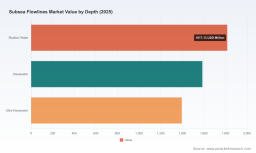
Worldwide Subsea Flowlines Market: A Strategic Brief for 2026 Decision-Makers
As offshore portfolios reassert themselves in corporate growth plans, subsea flowlines sit at the intersection of engineering complexity, procurement risk and commercial opportunity. PW Consulting’s new Worldwide Subsea Flowlines Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) delivers the market intelligence that executive teams, project sponsors and procurement leaders will rely on when making binding capital and sourcing decisions in 2026.
Ion-sliced Lithium Niobate Thin Film (LNTF) Market
Why this report matters now
-
Measured momentum: the subsea flowlines market demonstrated steady recovery through 2020–2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.5% over the 2026–2032 forecast window, reflecting an expanding pipeline of deepwater and tie‑back projects.
Worldwide Cross Linked Sodium Carboxymethyl Cellulose Market -
Scale and timing: with the total market size expanding noticeably from the 2025 baseline into the late 2020s, the next 18 months will determine whether companies can lock in cost‑effective supply and execution windows for projects sanctioned in 2026–2027.
Diamond Polishing Wheels Market -
Decision leverage: the report converts macro momentum into operational levers — supplier scorecards, procurement playbooks, risk matrices and scenario models — enabling near-term choices that protect margins and accelerate time-to-first-oil.
Core deliverables: what you get in the report
-
Comprehensive market sizing and trend analysis: historical and forecast market trajectories with year-by-year totals (USD Million), enabling board-level forecasting and investor communications.
-
Practical procurement tools: downloadable cost models, lead‑time heat maps, and contract archetypes (EPCI, supply-only, alliance frameworks) tailored to flowline projects.
-
Technical and commercial scorecards: supplier capabilities mapped across manufacturing, flexible and rigid technologies, flow assurance expertise, and SURF integration capacity.
-
Implementation playbooks: project-stage checklists (FEED → procurement → installation → commissioning) and risk controls for thermal management, corrosion mitigation and tie‑back execution.
-
Scenario and sensitivity modules: stress‑test models that quantify exposure to raw material price swings, regulatory tightening and alternative technology adoption (electrically heat‑traced flowlines (EHTF), pipe‑in‑pipe systems, clad/CRA solutions).
-
Regulatory and standards impact analysis: pragmatic implications of EN ISO 13628‑1:2025 for design, testing and documentation across oil, gas and low‑carbon subsea applications.
What the numbers tell us (strategic implications)
-
Reliable growth underpins investment: a mid-single-digit CAGR through 2032 signals a market attractive to both integrated SURF contractors and specialised component suppliers. Project sponsors should therefore assume sustained competitive tension for fabrication capacity and installation windows.
-
Concentration matters: the market shows moderate concentration among a small set of leading SURF and flowline integrators. This structure benefits large-scale buyers that can assemble multi-vendor consortiums, but it also increases the bargaining power of tier‑one suppliers on complex scope and long lead items.
-
Technology is a differentiator: thermal management (EHTF and insulated PiP solutions), CRA/clad pipes for aggressive chemistries, and flexible pipe innovations are shifting cost and risk from the installation phase into design and supply chains—creating new commercial negotiation points.
Competitive landscape — how the leading players are positioning for 2026
-
Integrated SURF and EPCI leaders (e.g., TechnipFMC, Subsea 7, Saipem) continue to compete on scale and turnkey delivery capability. Their strategic advantage derives from end‑to‑end execution, permitting single‑contract responsibility on complex deepwater tie‑backs and pre‑salt developments.
-
System specialists (e.g., Baker Hughes / OneSubsea, Aker Solutions) focus on productised subsea systems, modular flowline technologies and flow assurance integration—positioning themselves to capture premium SP/SSP scopes where standardisation reduces execution risk.
-
Connection and service innovators (e.g., Oceaneering) leverage niche technologies—metal‑to‑metal connectors, specialized clamps and tie‑in systems—to reduce offshore intervention time and support higher availability targets for brownfield tie‑ins.
-
Pipe and materials suppliers (e.g., Tenaris, Vallourec, ITP Interpipe) compete on metallurgy, supply reliability and thermal/insulation capabilities. Demand for clad/CRA and insulated PiP solutions is increasing the strategic value of upstream pipe inventory and long‑lead scheduling discipline.
-
Electrical and umbilical providers (e.g., Prysmian, Nexans) are moving closer to flowline ecosystems as electrification and integrated heat/ power systems become standard for longer tie‑backs.
-
Specialist subsystems (e.g., Dril‑Quip) provide critical interfaces between wells and flowlines; their compatibility and certification programs are now crucial selection criteria in FEED and procurement phases.
Recent contract flows and technology initiatives underscore these dynamics: multi‑billion dollar SURF awards and large flexible pipe contracts in deepwater basins are reallocating fabrication capacity and driving accelerated adoption of next‑generation thermal management techniques. Collaborative industry projects around post‑lay cable installation and other innovations are reducing installed‑cost metrics and carbon footprints—an increasingly salient procurement objective.
Risks and opportunity vectors for 2026
-
Supply chain squeeze: long lead times for specialised coated or clad pipes, premium connections and flexible pipe assemblies will create near‑term execution risk for projects sanctioned in 2026 unless buyers secure long‑lead PO terms and flexible award structures.
-
Regulatory overlay: updates to EN ISO 13628‑1 require early inclusion of standards compliance in FEED packages; late design changes to meet the new standard can materially impact marginal economics.
-
Technology‑driven differentiation: the commercial case for EHTF and PiP solutions is clearing for longer tie‑backs and CO₂/H₂S exposure—operators that pilot these options now can extend the economics of satellite developments.
-
Consolidation and alliances: the market’s moderate concentration encourages both partnership models (to access fabrication/install capacity) and opportunistic M&A by players seeking to capture higher value‑chain margins.
Actionable guidance — eight practical moves for 2026
-
Run a supply‑chain stress test: use scenario models to quantify exposure to long lead‑times, key supplier concentration and material shortages, and develop contingency sourcing strategies.
-
Prioritise early procurement of long‑lead items: secure pipe, flexible systems and premium connections within FEED windows to de‑risk schedule slippages and cost escalation.
-
Adopt modular standards where possible: standardised, repeatable flowline systems reduce engineering hours and enable faster integration with SURF contracts.
-
Negotiate hybrid contracting strategies: balance single‑point EPCI with specialist supply contracts to blend risk transfer with competitive pricing for commodity components.
-
Invest in flow‑assurance capability: digital twins and thermal/flow models are no longer optional for longer tie‑backs—buyers should mandate these in EPC and supplier bids.
-
Lock in compliance roadmaps: include EN ISO 13628‑1 acceptance criteria in purchase orders and FAT plans to avoid scope creep at commissioning.
-
Monitor raw‑material and clad pipe markets: evaluate inventory financing options or JIT supply agreements to manage price volatility in corrosion‑resistant and clad pipe segments.
-
Use competitive intelligence in negotiation: leverage supplier scorecards and recent contract precedents to benchmark bids and shorten approval cycles.
How PW Consulting’s report turns insight into advantage
Our analysis bridges the gap between headline numbers and executable plans. The report combines robust market modelling (annualized totals from 2020 through 2032 in USD Million), company-level capability analysis, technology adoption roadmaps and a set of tools designed for immediate operational deployment. We deliberately present enough depth to inform strategy while reserving full subsegment splits, granular regional allocations and supplier scorecards for the complete publication and accompanying data pack.
For procurement leads, the report is a playbook; for strategy teams, it is a scenario factory; for M&A groups, it is a map to bargaining leverage. If your 2026 capital and sourcing decisions will touch deepwater tie‑backs, pre‑salt developments, or the growing inventory of marginal field redeployments, this analysis is designed to reduce execution risk and sharpen negotiations.
Next steps
-
Access the full report and downloadable models on PW Consulting’s Worldwide Subsea Flowlines Market page to obtain the regional and application breakdowns, vendor scorecards and the interactive supply‑chain stress tester.
-
Contact our SURF team for a tailored briefing workshop: we can run your portfolio through the scenario modules and deliver decision-ready recommendations within 72 hours.
In an environment where technical complexity, regulatory change and supplier capacity converge, the right market intelligence converts options into executed value. PW Consulting’s report equips 2026 decision‑makers with the analytics and playbooks required to act with confidence—while preserving the detailed subsegment intelligence that empowers competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Subsea Flowlines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com