

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Lennox‑Gastaut Syndrome Drug Market Poised to Grow at a 4.52% CAGR

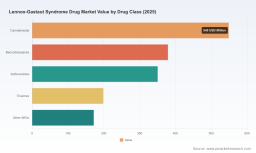
Worldwide Lennox-Gastaut Syndrome Drug Market — Strategic Insights for 2026 Decision‑Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Lennox‑Gastaut Syndrome (LGS) drug market provides a focused, decision‑ready intelligence package for executives planning actions in 2026. Our base‑year sizing places the global LGS drug market at approximately USD 1,650 million in 2025. Under a base case trajectory we model a compound annual growth rate (CAGR) of 4.52% through the forecast window, producing a materially larger market by 2032. The study combines granular commercial models, regulatory and payer scenario analysis, and competitor playbooks to translate epidemiology and therapeutic dynamics into executable commercial strategies. This release highlights the report’s strategic value while deliberately withholding confidential sub‑segment level outputs to encourage direct access to the full deliverable.
Worldwide Airport Management System Market
Why this report matters in 2026
-
Market clarity in a mixed innovation environment: LGS is a small, clinically complex rare epilepsy indication where high‑value branded therapies coexist with entrenched generics and off‑label use. Our study decodes how that coexistence affects pricing power, formulary access and real‑world utilization.
Worldwide Apparel Design Software Market -
Evidence driven access planning: Payer scrutiny and budget pressure are reshaping launch sequencing and reimbursement terms. The report synthesizes regulatory approvals, RWE trends and payer levers to help teams prioritize evidence generation that materially improves coverage outcomes.
Worldwide Lined Pipes Market -
Competitive scenario testing: With measurable concentration among leading suppliers (our concentration analysis shows a top‑three concentration consistent with a moderately concentrated specialty market and a top‑five concentration that reinforces incumbent advantages), boards and BD teams can better assess realistic growth pathways—organic, partnership, or acquisition.
-
Operational risk mitigation: Supply chain constraints for plant‑derived or tightly controlled APIs, and monitoring requirements for safety‑constrained drugs, create distinct manufacturing and distribution risks. Our operational playbook identifies where to invest to reduce commercial disruption.
What the full report contains (practical components)
-
Comprehensive market model (base year 2025) and scenario forecasts through 2032, including sensitivity runs for incidence, treatment mix and price erosion.
-
Regulatory and reimbursement matrix mapping FDA approvals, label nuances, boxed‑warning implications and payer cost‑effectiveness thresholds relevant to LGS products.
-
Competitor dossiers and switch‑case playbooks for leading brands and entrants, plus a prioritized M&A/licensing target list informed by clinical fit, commercial synergies and manufacturing gaps.
-
Practical launch and lifecycle templates: key evidence milestones, RWE protocols, pricing submission timelines, and sample contracting language for specialty pharmacy carve‑outs.
-
Market access simulation tools that let users test price, rebate and utilization management levers against payer‑level uptake assumptions.
-
Channel and distribution diagnostics to determine optimal mix between hospital specialty, retail specialty and digital/specialty pharmacy pathways.
Competitive landscape: executive takeaways
LGS therapeutics today are characterized by a mix of established neurology franchises, targeted orphan‑drug innovators and several generics players. Leading companies—including Jazz Pharmaceuticals (Epidiolex cannabidiol), UCB (Fintepla fenfluramine), Lundbeck/Erisai/others (clobazam and rufinamide origins), and larger neurology incumbents with broad antiseizure portfolios—define the front lines of competition. Several dynamics are critical for 2026 planning:
-
Branded innovation drives premium pricing but invites rapid reimbursement scrutiny. High‑value entrants are already subject to durable payer evidence requirements; manufacturers must plan RWE and pharmacoeconomic programs that begin at launch to protect list price and net realized revenue.
-
Generic competition is real and accelerating. Recent and anticipated approvals of generic formulations for legacy agents (for example in early 2026 and beyond) increase downward pressure on unit prices and shift physician prescribing toward lower‑cost options unless differentiation is maintained via formulation, delivery system, or supportive services.
-
Safety‑based segmentation matters. Agents with serious safety profiles (e.g., drugs that require frequent lab monitoring or carry boxed warnings) will remain clinically important but restricted in use—creating opportunity for safer, differentiated therapies and for diagnostics or monitoring services that facilitate use.
-
Commercial concentration suggests scale matters. The top few manufacturers collectively account for a majority of market value, reinforcing the advantage of scale in contracting, specialty distribution and post‑market evidence generation.
Recent industry developments and implications
-
Generic approvals in early 2026 (notably for certain lamotrigine formulations) validate the near‑term margin pressure theme—revenue models and launch timetables must include contingencies for both rapid generic entry and multi‑year net price erosion curves.
-
Real‑world studies on newer entrants (for example persistence and discontinuation patterns following commercial uptake of fenfluramine) are shifting clinical and payer perceptions; manufacturers should anticipate RWE findings and build interpretive narratives that strengthen formulary positioning.
-
New analyses leveraging genetic and biomarker data from LGS trial populations are expanding the potential addressable sets for some agents. Biotechnology and diagnostics teams will find adjacent opportunities to co‑develop companion tools that add differentiation and justify premium positioning.
-
Resource complexity for plant‑derived or scheduled substances persists (e.g., highly purified cannabinoids). Security, compliance, and vertical integration decisions materially affect cost of goods and launch timing.
Strategic recommendations for 2026 (practical priorities)
-
Prioritize early payer engagement with a payer evidence roadmap that ties to specific coverage milestones and specialty pharmacy pathway contracts.
-
Accelerate real‑world evidence programs that address persistence, safety in broader clinical practice, and comparative effectiveness versus both branded competitors and generics.
-
Differentiate via services: adherence support, remote monitoring, and lab‑linkage programs can convert clinical advantages into payer‑valued value propositions.
-
Design launch sequences regionally—focusing early resources where net pricing and specialty pharmacy capacity maximize return on investment (our report’s scenario tool models multiple geographies and payer archetypes).
-
Hedge supply‑chain risk for complex APIs through dual‑sourcing, contract manufacturing partnerships, or secured raw‑material contracts.
-
Evaluate targeted acquisitions or licensing deals to obtain differentiated formulations or diagnostic linkages rather than volume‑only plays that suffer margin contraction under generic pressure.
-
Implement aggressive lifecycle strategies for legacy brands: reformulations, pediatric indications, and bundled care programs can extend premium positioning beyond the narrow exclusivity window.
-
Monitor regulatory and label developments closely—safety labeling and FDA guidance can materially reallocate utilization between agents; contingency planning is essential.
How PW Consulting’s study converts insight into action
Clients purchasing the full report receive not only our forecast and landscape analysis but also executable commercial blueprints: payer communication templates, RWE study protocols aligned with anticipated payer questions, and an interactive financial model that quantifies the ROI of specific investments (e.g., a field force expansion, a robust RWE program, or a supply‑chain dual‑sourcing strategy). We map out decision trees for four distinct strategic archetypes—incumbent defender, premium innovator, specialty generics consolidator, and service‑enabled disruptor—each with recommended KPIs and milestone gates for 2026.
Closing: the strategic value of timing
2026 represents a pivotal year for stakeholders in the LGS drug market. The combination of sustained market growth at an underlying CAGR near 4.5%, accelerating generic competition, evolving payer expectations for evidence, and ongoing clinical differentiation creates both risk and opportunity. Companies that move early—aligning clinical development with payer evidence, investing selectively in differentiated formulations and services, and shoring up operational resilience—will secure outsized share and margin outcomes.
PW Consulting’s Worldwide Lennox‑Gastaut Syndrome Drug Market report is designed to be the single source of truth that supports those decisive actions. For teams preparing board presentations, M&A diligence, or 2026 commercial plans, the full report delivers the proprietary scenarios, templates, and models needed to move from strategy to execution. Access to the complete study and supporting tools is available through PW Consulting’s market intelligence portal.
For detailed analysis of this topic, please visit the official page: Worldwide Lennox-Gastaut Syndrome Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com