

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Medical Microscopic Hemostatic Clip Market Set to Grow at 7.2% CAGR — 2026–2032 Forecast

Worldwide Medical Microscopic Hemostatic Clip Market — Strategic Briefing for 2026 Decision-Makers
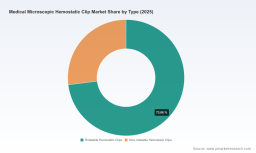
PW Consulting’s latest market research report on the Worldwide Medical Microscopic Hemostatic Clip Market synthesizes five years of historical observations (2020–2025) and provides a seven-year forecast (2026–2032) built for executives who must make high-consequence choices in 2026. The market has expanded from roughly USD 410 million in 2020 to about USD 580 million in 2025 and is projected to approach USD 944 million by 2032, reflecting a 7.2% compound annual growth rate over the 2026–2032 forecast window. These headline metrics frame a market that is both attractive and contested: the three-largest suppliers account for a meaningful majority of sales, and the five-largest players concentrate nearly four-fifths of market value—conditions that materially affect go-to-market tactics, R&D investment sizing, and M&A calculus.
Spinal Surgery Navigation System Market
Why this study matters for 2026 planning
- Evidence-based prioritization: The report translates macro growth into tactical implications for product development, clinical evidence, and commercialization timing—so teams can prioritize features and geographies most likely to deliver near-term ROI.
- Risk-managed investment sizing: We provide scenario-driven revenue paths that allow CFOs and corporate development teams to size capex and evaluate payback under alternative adoption curves and reimbursement regimes.
- Commercial playbooks: The study includes executable channel, pricing, and tender-engagement frameworks tailored to the nuanced behavior of hospital procurement and outpatient endoscopy clinics.
Market dynamics: drivers, constraints, and inflection points
- Demand drivers: Growth is driven by a rising volume of endoscopic and minimally invasive procedures, increasing outpatient care migration, and clinical preference shifts toward devices that reduce procedure time and facilitate same-day discharge.
- Technology-led differentiation: Innovation vectors—automatic preloaded appliers, 360° rotatable clips, and repositionable designs—are materially changing clinician workflows and creating premium product tiers that command differentiated pricing.
- Regulatory and reimbursement context: Titanium microclips are regulated as Class II implantable devices under U.S. rules (product code FZP) with associated GMP and labeling obligations. Reimbursement pathways are shifting in favor of outpatient adoption—an example being a HCPCS code introduced for defect closure procedures in outpatient settings. These two forces together shorten commercialization timelines for compliant devices while raising the bar on clinical and economic evidence.
- Supply and materials: Microclips are produced from Grade 1 titanium—annealed for malleability, MRI compatible, and biologically inert—creating a supply chain dependency that must be managed at design and sourcing stages.
- Market structure: Concentration metrics indicate that a small set of established manufacturers dominate value, which affects bargaining dynamics with large hospital systems and distributor networks.
What’s inside the report (practical, actionable contents)
- Integrated market-sizing model (2020–2032) with scenario analyses and sensitivity levers you can manipulate for internal business cases.
- Commercial roadmaps that translate innovation attributes (e.g., rotatability, repositionability, single‑use vs reusable appliers) into time-to-revenue and price premium estimates.
- Regulatory playbook specific to hemostatic microclips: decision trees for 510(k)/CE strategy, labeling and post-market surveillance requirements, and critical path timelines.
- Reimbursement mapping and payer-engagement templates aligned to outpatient migration and HCPCS code implications.
- Supplier and procurement risk matrix for titanium sourcing, sterilization streams, and contract manufacturing options.
- Competitive benchmarking with capability maps, product feature matrices, and an M&A target prioritization model tailored to strategic buyers.
- Implementation toolkits: go-to-market checklists, clinical trial design templates for hemostasis endpoints, and an ROI calculator for purchasing committees.
Competitive landscape — what leading firms are doing now
The market is populated by a mix of established surgical-instrument specialists and newer entrants pursuing differentiated clip and delivery-system combinations. Key strategic moves observed through 2025–mid‑2026 highlight both product innovation and consolidation of distribution rights.
Worldwide Solder Mask Market
- Synovis Micro Companies Alliance, Inc. (Baxter) — Synovis has reinforced its microsurgery credentials with titanium microclip families designed for vessel occlusion and the commercial introduction of an automatic, preloaded microclip applier. Regulatory clearance in early 2025 for an automatic applier validates a strategy focused on workflow simplification and clinician efficiency. Expect Synovis to pursue expanded adoption through bundled consumable-applier economics and targeted clinical evidence.
- Olympus and other endoscopy platform vendors — Platform incumbents continue to introduce single-use, rotatable clip systems optimized for GI bleeding and defect closure. These product launches intensify competition at the interface between endoscope OEMs and independent clip suppliers, and they raise the importance of integration and cross-selling strategies.
- Micro-Tech Endoscopy — The acquisition of global distribution rights for a repositionable clip line demonstrates an aggressive channel-expansion play; companies that secure broad distribution early can significantly accelerate adoption in outpatient endoscopy centers and ambulatory surgical centers.
- Specialized instrument manufacturers (e.g., Peter Lazic, S&T Microsurgical Instruments, Scanlan, Kapp, MicroSurgical Technology) — These firms compete on precision, customization, and surgeon loyalty. Their strengths lie in neurosurgical and microsurgical niches where instrument ergonomics and material quality are non-negotiable. Strategic options include co-development with OEMs, premium differentiation, or selective licensing to broaden market reach.
- Amsel Medical Corporation — The commercial presence of mechanical occluders with proprietary technologies indicates an adjacent product strategy—positioning non-metallic or alternative occlusion devices where traditional clips are indicated. This creates a competitive tension that incumbents must address via head‑to‑head evidence or bundle strategies.
Recent deal and product activity — implications for 2026 strategy
- Product launches emphasizing 360° rotation and one-step deployment are proving that incremental ergonomic improvements can unlock meaningful clinical adoption. For manufacturers, the lesson is clear: invest selectively in deployment ergonomics and clinician workflow integration.
- Distribution deals and portfolio acquisitions are accelerating route-to-market expansion. Companies evaluating organic vs inorganic expansion should model time-to-revenue, dilution of margin, and the value of established sales channels.
- Regulatory clearances for automatic appliers create a near-term barrier to entry for challengers without significant regulatory and quality infrastructure—making partnerships with experienced manufacturing and regulatory organizations a practical path to market.
Strategic priorities for 2026 — five actions we recommend
- Focus R&D on deployment and repositionability: Our evidence indicates that devices which materially reduce procedure time and allow repositioning will capture clinician preference and justify premium pricing. Prioritize low-risk enhancements with high operational impact.
- Lock supply continuity for Grade 1 titanium: Secure multi-year contracts with qualified suppliers and validate alternative sources to avoid production interruption and price volatility.
- Design an evidence generation roadmap: Align clinical trials and real-world studies with payer requirements for outpatient reimbursement, emphasizing economics (OR time saved, reduced repeat procedures) and safety endpoints.
- Evaluate channel expansion via selective M&A or distribution partnerships: If your organization lacks scale in endoscopy or ambulatory channels, partnering or acquiring distribution rights can accelerate adoption and improve negotiating leverage with high-volume customers.
- Operationalize regulatory readiness: Given Class II device pathways and stringent post-market obligations, invest in regulatory, quality, and labeling capabilities now to avoid launch delays.
How PW Consulting’s deliverables accelerate execution
We built this report as an operational instrument for 2026: the market models are delivered in editable format so corporate development and product teams can run bespoke scenarios; the regulatory and reimbursement checklists are tailored to submissions and payer dialogues in key markets; and the M&A prioritization framework quantifies strategic fit against integration risk. The result is a single source of truth that reduces time-to-decision and the risk of costly strategic missteps.
Worldwide IoT Routers Market
Next steps — where to go for the full intelligence
This briefing intentionally highlights the strategic contours and the practical choices facing leaders in 2026 while reserving detailed segment-level data and the full competitive scorecards for the comprehensive report. For access to the full dataset, granular segmentation models, and executable templates referenced here, please visit PW Consulting’s report page for the Worldwide Medical Microscopic Hemostatic Clip Market.
PW Consulting stands ready to support executive teams with rapid workshops to translate the report’s findings into a 90‑day execution plan, M&A target screening, or an evidence-generation blueprint tailored to your product portfolio.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Microscopic Hemostatic Clip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com