

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 1-Decanol Market Set to Rise from USD 280.8 Million in 2025 to USD 436.36 Million by 2032 at 6.5% CAGR

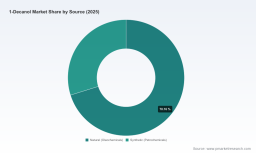
Worldwide 1-Decanol Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new Worldwide 1-Decanol Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) provides a practice-oriented intelligence package targeted at commercial, procurement, and corporate strategy teams preparing for 2026 and beyond. The market demonstrated robust recovery and structural growth over the past five years — rising from a modest industrial base in 2020 to an estimated global market size of USD 280.8 Million in 2025. Our forecast models project continued expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 6.5%, with the market expected to reach roughly USD 436 Million by 2032 under the base-case scenario.
Smart Cloud Transformer Market
This release is a “trailer” of the full report: we showcase the depth and actionable orientation of our analysis while intentionally withholding certain granular segmentation tables and price-by-region series that are included in the full dataset. The aim is to build confidence in our methodology and to direct decision-makers to the full report for detailed, model-ready data and downloadable matrices.
Worldwide Email Testing Software Market
Why 1-Decanol matters to corporate 2026 playbooks
- Cross-sector exposure: 1-Decanol sits at the intersection of surfactants, plasticizers, lubricants, and specialty personal-care chemistries. Changes in demand patterns for any of these downstream sectors pattern into 1-decanol procurement, pricing, and product development strategies.
- Procurement-risk management: Raw-material volatility is non-trivial. In Q4 2025 coconut oil — a key feedstock for natural 1-decanol — experienced a material price uptick, and lauric acid pricing remained elevated in early 2026. Our sensitivity modules quantify the margin squeeze for natural versus synthetic supply chains across multiple feedstock-price scenarios.
- Regulatory externalities: New and evolving regulatory constraints are an immediate operational input for 2026 planning. Notable developments include updated EU REACH exposure scenario requirements for surfactant uses and U.S. trade measures that have reshaped competitive positioning. In addition, updated state-level labeling frameworks in the U.S. have implications for formulations and claims management in consumer-facing portfolios.
- Concentration and channel dynamics: The global supplier base shows meaningful concentration, with the top producers controlling a material share of the market. This concentration, combined with recent capacity moves among specialist oleochemicals players, implies that targeted commercial actions (long-term offtake contracts, dual-sourcing strategies, and regional hedging) will be critical to control input cost exposure and secure supply continuity in 2026.
Report contents — what practitioners will find inside
- Comprehensive market-size time series (2020–2025) and forward-looking model (2026–2032) with scenario toggles (price, demand shock, regulatory stress-testing).
- Supply-side atlas and capacity map, including feedstock pathways (oleochemical versus synthetic routes), plant-level risk scoring, and near-term announced expansions.
- Procurement playbook: hedging and contracting templates, cost-to-serve models, and short-/mid-term raw-material substitution matrices.
- Competitive benchmarking and acquisition screen — profile dossiers for the leading producers, technology advantages, margin analysis, and strategic positioning by route-to-market.
- Regulatory and toxicology watchlist with compliance timelines, labeling implications for consumer formats, and recommended mitigation steps for formulation teams.
- Value-capture frameworks for specialty grades: pricing levers, testing protocols for high-purity grades, and commercialization checklists for pharma or cosmetic applications.
- Detailed appendix with source-level data, assumptions, and an interactive Excel model enabling users to run custom scenarios for 2026 board reviews.
Market dynamics and near-term catalysts (operational perspective)
Our baseline 6.5% CAGR for 2026–2032 incorporates a mix of demand-pull from personal care and industrial cleaning, incremental substitution in lubricant additives, and sporadic capacity additions. However, the path to that base-case is asymmetric — short-term shocks and policy shifts can amplify volatility.
Blood Donor Couch Market
- Feedstock pressure: Supply constraints in key coconut-oil producing geographies pushed feedstock prices materially in late 2025; similarly, lauric-acid costs remain a critical input for hydrogenation routes. Buyers should assume a higher probability of single-digit to mid-teens percentage swings in input costs over a 12-month horizon and structure contracts accordingly.
- Trade and tariff environment: Recent increases in trade measures on certain fatty-alcohol imports have altered landed-cost profiles for many buyers. Market participants should re-evaluate sourcing footprints and landed-cost models during 2026 procurement cycles.
- Regulatory compliance: EU REACH and regional labeling updates require timely submission of exposure and safety data for some common uses of 1-decanol. Non-compliance risk can lead to time-to-market delays for reformulated consumer SKUs; our regulatory playbook offers a stepwise compliance timeline and cost estimation template.
- Sustainability certification and market access: Voluntary certification pathways and sustainable mass-balance schemes are becoming table stakes for suppliers seeking preferred status with European and North American customers. Certification is frequently rewarded with longer-term contracts and access to specialty channels.
Competitive landscape — what the supply map tells us
The market is served by a mix of multinational chemical houses, integrated oleochemical groups, and specialized synthetic producers. PW Consulting’s competitive scoring synthesizes commercial footprint, technology mix (oleochemical vs. synthetic routes), sustainability credentials, and recent investment activity.
- BASF SE (Ludwigshafen, Germany): An integrated global chemicals platform; 1-decanol is positioned within a broader fatty-alcohol and surfactant portfolio. Strengths include scale, diversified end-markets, and global logistics capabilities.
- Evonik Industries AG (Essen, Germany): Focuses on specialty applications including cosmetics and high-value detergents. Recent sustainable-credentials progress has strengthened access to premium European buyers.
- KLK Oleo (Malaysia): An oleochemical player with an Asia-Pacific footprint. Announced capacity expansions illustrate a strategic bet on regional demand growth and closer-to-feedstock integration.
- Musim Mas Group (Singapore): Active in mid-cut fatty alcohols and has brought forward higher-purity variants aimed at pharmaceutical excipient opportunities — a strategic move up the value chain.
- PT Sinar Mas Oleochemical (Indonesia) and Godrej Industries (India): Regional champions focused on export markets and large-volume commodity streams; competitive on cost and regional logistics.
- Eco Services Operations, LLC (Houston, USA — formerly Sasol): A provider of synthetic 1-decanol aimed at high-purity industrial applications where consistent, petrochemical-derived feedstock is preferred.
Market concentration is meaningful: the combined share held by the market’s top three and top five players is sufficient to influence spot availability and negotiation dynamics. This structure creates strategic opportunities for mid-tier firms to capture share through specialty grades, service differentiation, and regional partnerships.
Strategic implications and recommended actions for 2026
- Revise sourcing strategies now: Move from annual spot procurement to a layered sourcing model that combines short-term flexibility with secured mid-term volumes (12–24 months). Consider index-linked contracts with built-in feedstock pass-through clauses to reduce margin erosion.
- Prioritize regulatory hardening: If your product formulations involve surfactant or consumer-contact applications, allocate resources to meet EU REACH submission windows and state-level labeling requirements. Non-compliance could delay launches or restrict distribution in key markets.
- Invest in premium-grade development: The premiumization route (high-purity, pharma/cosmetic-ready grades) has a higher margin profile and is less price-sensitive. Our product-playbook lays out testing specs, certification requirements, and commercialization milestones.
- Consider M&A and partnership screens: Given the market’s concentration, bolt-on acquisitions in niche-technology or regional-logistics capabilities can accelerate market access. Our acquisition screener ranks targets by integration complexity and expected payback under multiple price scenarios.
- Stress-test P&L for feedstock shocks: Use our scenario model to test P&L sensitivity under concurrent feedstock price spikes and tariff changes. This should inform capital allocation and contingency inventory policies for 2026.
Methodology snapshot
PW Consulting’s base-case blends top-down demand drivers (downstream polymer, surfactant and lubricant markets), bottom-up capacity and plant utilization data, and price-elasticity calibrated against historical moves between 2020–2025. All models are available as interactive worksheets in the full report. We triangulate proprietary shipment data, customs statistics, and primary interviews with producers and formulators to validate our assumptions.
Recent developments we factor into 2026 outlook
- Capacity expansion announcements from Asian oleochemical producers and launches of high-purity grades have been incorporated into near-term supply projections.
- Certification and sustainability initiatives in 2024–2025 have altered tender dynamics in Europe and North America; suppliers with mass-balance or recognized certification are gaining structural advantages.
- Trade-policy shifts and regional feedstock cost moves in late 2025 and early 2026 have raised the floor for landed costs in several importing markets, prompting buyers to reassess total-cost equations.
Accessing the full intelligence
This preview articulates the strategic contours of the 1-decanol market and highlights immediate decision levers for 2026. The full Worldwide 1-Decanol Market report contains the complete dataset, downloadable Excel models, supplier scorecards, and region/application-level demand matrices required for execution. PW Consulting clients and corporate subscribers can access the report and our market simulator through the PW Research portal.
For procurement teams, R&D leads, and C-suite strategists planning 2026 objectives, this report is a practical tool to convert market signals into defensible procurement contracts, targeted product investments, and risk-mitigating commercial arrangements.
For detailed analysis of this topic, please visit the official page: Worldwide 1-Decanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com