

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Tasigna Market Set to Contract at -11.45% CAGR During 2026–2032

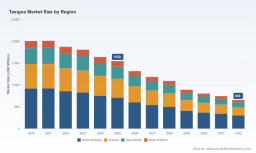
Worldwide Tasigna (nilotinib) Market — Strategic Outlook for 2026: Navigating Rapid Contraction, Concentration, and Commercial Reinvention
Executive summary
PW Consulting’s newest Worldwide Tasigna Market report frames the next three-year decision window (2026) against an unmistakable structural shift. The global market for Tasigna (nilotinib capsules) has been in measurable decline since 2020, and our model projects a continued contraction through 2032. After peaking in the early 2020s, total market revenues fell to approximately USD 1,550 million in 2025, and our base-case projection shows a trajectory to roughly USD 660 million by 2032 — a compound annual decline of about 11.45% across the 2026–2032 forecast horizon. At the same time, the market remains highly concentrated (CR3 ~92.4%; CR5 ~96.15%), creating a paradox: a shrinking pie dominated by a small set of incumbents and new generic entrants.
Intra-Array Submarine Cable Market
Why this matters for 2026 corporate decisions
- Acceleration of generic erosion and pricing pressure is not hypothetical — it is now the primary determinant of revenue and strategic posture for stakeholders across originator, generic, and specialty pharmacy channels.
- High concentration means moves by a single large player (e.g., originator lifecycle decisions, pricing changes, or additional authorized generics) will cascade rapidly through payer formularies and procurement processes.
- Clinical, regulatory and reimbursement constraints — including boxed safety warnings and evolving Medicare Part D payment structures — will intersect with commercial tactics to shape access and adherence outcomes.
Market trajectory and core dynamics (what the numbers tell us)
Our consolidated top-line model marries product-level sales data with regulatory event timing and competitive entry scenarios. The pattern is clear: post-patent generic launches and shifting payer reimbursement have materially reduced unit price realization and volume growth trajectories. The result is a steady downward revision of the total addressable market from 2020 through 2025 and a forecasted steeper decline across 2026–2032.
Generator for Nuclear Power Market
Key inflection events documented in our analysis include the expiry of foundational intellectual property that enabled authorized and independent generic launches, and the subsequent market response from both the originator and generic manufacturers. For example, the first approved generic versions gained entry in late 2022, and the originator subsequently reported a substantial year-over-year revenue decline in 2023 — illustrative of the near-immediate financial impact of generic competition on branded pricing and uptake.
Worldwide Heavy Duty Diesel Engine Oils Market
Competitive dynamics: concentrated market, fast-moving tactics
The Tasigna market structure remains distinctive: a small number of companies capture the bulk of sales, even as generics expand their presence. Novartis AG continues to be the principal originator and commercial steward of the branded product, facing both price compression and strategic choices about resource allocation, lifecycle management, and supportive services. Generic entrants have already altered the commercial playing field with rapid launches and distributor-focused strategies.
From a strategic standpoint, this produces several observable behaviors:
- Originator emphasis on value-added services (patient support, monitoring programs) rather than price defense alone;
- Generic players prioritizing distribution scale, formulary placement tactics, and contracting agility to maximize volume share;
- Payers responding with formularies and utilization management rules calibrated to quickly adopt lower-cost options under Medicare Part D and other reimbursement mechanisms.
Regulatory and clinical constraints shaping commercial options
Regulatory and clinical safety considerations materially affect how Tasigna is prescribed, reimbursed, and marketed. The product carries notable safety warnings that require clinician monitoring and informed consent, which in turn affects switching dynamics and patient persistence when cheaper generics are introduced. Additionally, the post-patent regulatory landscape — including Orange Book entries and generic approvals — has already reshaped competitive entry timelines. Payer mechanics such as Medicare Part D’s payment rules further accelerate price discovery and substitution once generics are established.
Strategic imperatives for decision-makers in 2026
Whether you are an originator, generic manufacturer, specialty distributor, payer, or investor, PW Consulting’s analysis yields clear, actionable imperatives for the 2026 planning cycle:
- Reassess portfolio prioritization: For originators, this means quantifying marginal returns on continued investment in branded promotion versus redeploying commercial resources to adjacent assets or pipeline projects. For generics, it means refining supply-chain scale and contract terms to sustain low-margin, high-volume plays.
- Differentiate beyond price: Build and price bundled services (adherence support, digital monitoring, REMS-compliant programs) that are not easily replicated by low-cost generics and that preserve clinic-level preference for branded products where clinically justified.
- Refine payer engagement strategies: Use real-world evidence and total-cost-of-care modeling to negotiate access terms that mitigate immediate price erosion while aligning with payers’ long-term budget objectives.
- Prepare for accelerated tender and contracting cycles: Optimize manufacturing and logistics to meet the procurement cadence of large buyers and group purchasing organizations, where speed-to-market wins volume.
- Scenario plan for extreme downside: Given the projected negative CAGR, companies should stress-test balance sheets and model divestiture, licensing, or manufacturing optimization options as part of near-term contingency planning.
What the PW Consulting report delivers (practical, executable content)
This publication is designed as an operational playbook for 2026 decisions. It contains:
- A transparent, auditable market model (USD million) with historical performance (2020–2025) and granular forward scenarios to 2032, enabling users to toggle assumptions around generic uptake, pricing deflation, and population dynamics;
- Competitive heat maps and concentration analysis that identify where strategic moves by major players will have outsized impact;
- Reimbursement and policy impact matrices — including Medicare Part D implications — that convert regulatory changes into financial outcomes;
- Commercial playbooks for originators and generics (go-to-market, formulary strategies, patient services, pricing tactics) with execution timelines calibrated to 2026 planning cycles;
- Operational risk and supply resilience frameworks to manage manufacturing scale-downs, API sourcing risks, and inventory strategies in a declining market;
- Deal and portfolio diagnostics that support M&A, licensing, and divestiture decisions with an emphasis on maximizing value capture in a commoditizing environment;
- Templates for payer negotiations, RWE generation, and medical–commercial alignment that translate strategic priorities into measurable KPIs.
To preserve the strategic value of the full dataset and to respect commercial confidentiality, this press release intentionally withholds the detailed segmentation tables (regional splits, dosage strengths, and indication-level breakout). These segment-level outputs are available exclusively in the full report and accompanying dataset.
Use cases: how different stakeholders should apply the intelligence in 2026
- Pharma executives: Use our scenario model to decide whether to pursue aggressive lifecycle investments or to reallocate capital toward higher-return assets.
- Generic manufacturers: Leverage the distribution and contracting playbooks to optimize launch sequencing and maximize formulary access.
- Payers and PBMs: Apply our cost-impact matrices to design utilization management that balances access, safety, and short-term savings.
- Private equity and investors: Inform valuation models and divestiture timing with our downside scenarios and concentration metrics.
Competitive snapshot and recent developments (brief, material events)
Noteworthy market events captured in our timeline include the approval and launch of the first generic versions in late 2022, following patent expirations in early 2023. The originator reported a significant revenue contraction in the immediate post-generic period — a concrete example of how quickly branded revenue declines when generics achieve scale. These events are combined with evolving reimbursement mechanisms and persistent clinical safety constraints to create an environment where commercial agility and payer engagement determine winners and losers.
How PW Consulting’s output supports 2026 boardroom decisions
Boards and senior management teams need a compact set of decision-ready deliverables in 2026; this report supplies them. Deliverables include:
- Management-level slide decks translating market scenarios into budget and resource allocation options;
- Operational checklists for supply-chain consolidation, inventory drawdown, and cost-to-serve recalibration;
- Negotiation scripts and evidence packs for payer discussions that emphasize total-cost impacts and patient safety metrics;
- Exit and partnership frameworks for value-maximizing transactions if portfolio rationalization is the chosen path.
Next steps and where to get the full dataset
This press release is intentionally a strategic preview designed to surface the report’s major findings and practical implications while preserving the proprietary value of our full segmentation and modeling. Organizations preparing budgets and strategic plans for 2026 should access the full report and interactive model to: (a) run bespoke scenarios against your commercial assumptions, (b) extract region- and indication-specific forecasts for resource allocation, and (c) deploy our payer and commercial templates immediately.
Closing
The Tasigna market in 2026 is not simply smaller; it is structurally different. Shrinking topline projections, combined with high market concentration and decisive regulatory and reimbursement pressures, mean that strategic clarity and operational discipline will determine long-term viability. PW Consulting’s Worldwide Tasigna Market report equips executives with the scenario tools, commercial playbooks, and negotiation-ready evidence they need to make those calls with confidence. For access to the full dataset, segmentation tables, and interactive forecasting model, please consult the PW Consulting report page or contact our advisory team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Tasigna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com