

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Buruli Ulcer Treatment Market Poised for Steady Expansion at 4.8% CAGR Through 2032

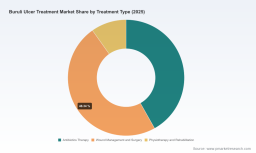
PW Consulting Releases Strategic Brief: Worldwide Buruli Ulcer Treatment Market — Essential Intelligence for 2026 Decision-Makers
PW Consulting’s latest market research report on the Worldwide Buruli Ulcer Treatment Market furnishes leaders in pharmaceuticals, global health procurement, non-profit funding, and clinical service delivery with the targeted intelligence required to shape high-confidence decisions in 2026. Built on a rigorous base year of 2025 and an extended forecast window through 2032, the study combines audited historical performance (2020–2025), forward-looking scenario analysis, and practical playbooks for market entry, partnership formation, and supply-chain resilience.
Video Consultation Computer Trolley Market
Why this report matters for 2026
-
Clear, investable market trajectory: The market expanded from a documented base in 2020 to an estimated USD 78.45 Million in 2025 and is projected to grow to approximately USD 108.92 Million by 2032, representing a compound annual growth rate (CAGR) of about 4.8% through the forecast period. For organizations planning resource allocations, manufacturing scale-up, or procurement contracts in 2026, these macro parameters provide a reliable envelope for demand planning and budgetary prioritization.
Worldwide Miniature Power Supply Market -
Actionable competitive context: Market concentration is neither a fragmented long tail nor a closed oligopoly. Our concentration metrics indicate a market where a handful of established suppliers control a meaningful share of supply—creating both opportunities for scale partners and clear levers for new entrants to pursue differentiated value propositions.
Worldwide Rock Sugar Market -
Policy and purchasing clarity: Recent WHO guidance has crystallized first-line treatment expectations and programmatic procurement behavior, which in turn drives predictable demand for specific antibiotic regimens and associated wound-care services. The implications are immediate for 2026 procurement cycles, donor program planning, and manufacturers seeking WHO prequalification pathways.
Key findings: distilled for strategic use
-
Steady, risk-mitigated growth. After a period of modest fluctuations in the early 2020s, the market exhibits steady expansion underpinned by sustained programmatic treatment (community and facility-based), ongoing surveillance activities in endemic countries, and incremental uptake of integrated wound management. The forecasted mid-single-digit CAGR reflects a market with low speculative upside but high predictability—ideal for conservative capacity investments and long-term supply contracts.
-
Supply-side dynamics favor prequalified generics. The treatment ecosystem remains anchored to well-known antibiotic regimens. WHO prequalification and national program endorsements are decisive procurement filters. As a result, manufacturers with prequalification status or established WHO partnerships enjoy an outsized advantage in tender processes and donor-funded distribution channels.
-
Concentration creates tailored strategies. The market’s concentration profile means that strategic collaboration—whether through co-supply agreements, licensing, or targeted M&A—can quickly alter competitive positioning. For potential entrants, building a route-to-market aligned with existing procurement flows and WHO-led programs is more efficient than attempting to displace entrenched suppliers on volume alone.
-
Procurement and reimbursement continue to be program-driven. In endemic settings, treatment is largely provided through national public health programs supported by international agencies and donors. This creates a procurement landscape dominated by centralized tenders and donor-funded initiatives rather than fragmented private-pay demand.
-
Raw material and manufacturing dependencies persist. Due to limited commercial incentive in this therapeutic area, many active pharmaceutical ingredients (APIs) and finished generics are manufactured by a relatively small number of established producers. That situation elevates supply-chain risk from single-source exposures, quality compliance challenges, and raw-material cost volatility—each of which is explored in the report’s supplier-risk matrix.
Competitive landscape — what you need to know
-
Role of WHO-prequalified suppliers: Companies that have secured WHO prequalification occupy a privileged position within national procurement frameworks. The report profiles leading prequalified partners and outlines pragmatic engagement tactics for manufacturers seeking qualification or buyers negotiating long-term supply agreements.
-
Established generics producers: Prominent global generics manufacturers remain core suppliers of standard regimens. Their strengths include scale manufacturing, established distribution channels into endemic markets, and experience with regulatory dossiers. Our competitive profiles highlight where efficiency gains, cost-leadership, or bundled service offerings could unlock new share.
-
Market openings for differentiated offers: While antibiotics form the backbone of treatment, unmet needs in wound management, surgical support for advanced lesions, and rehabilitation services create niches where clinical-service suppliers, medical-device firms, and specialty wound-care manufacturers can add value and capture premium margins.
Report content — what is inside (practical, non-generic deliverables)
-
Market sizing and validated forecasts (2020–2032): Transparent methodology using programmatic treatment volumes, procurement records, and supplier shipment data. Scenario analysis quantifies upside and downside pathways tied to program scale-up and guideline revisions.
-
Supply-chain and supplier-risk matrix: Granular assessment of API sourcing, manufacturing concentration, regulatory status, and single-source vulnerabilities—ranked by likelihood and potential program impact.
-
Regulatory and policy playbook: Step-by-step guidance for achieving WHO prequalification, aligning dossiers to national tender requirements, and anticipating regulatory shifts that influence 2026 procurements.
-
Commercial and partnership strategy templates: Tender-response checklists, pricing-benchmarking tools, and partner selection criteria for co-supply, licensing, and local-manufacturing arrangements designed for quick adaptation to 2026 cycles.
-
Clinical and programmatic risk mitigations: Operational protocols for managing surgical backlogs, integrating physiotherapy in care pathways, and scaling outreach programs—each tied to cost-per-patient metrics and resource planning models.
-
Country and program intelligence snapshots: Compact, actionable briefs that synthesize procurement behavior, payer models, tender calendars, and implementation partners—designed to inform market-entry pilots and donor funding proposals without requiring country-level field teams.
Implications for 2026 strategies — recommended actions
-
For manufacturers and suppliers: Prioritize WHO engagement and prequalification alignment in Q1–Q2 2026. Secure API supply agreements with built-in redundancies, and explore co-manufacturing or tolling arrangements in regions with higher programmatic demand to reduce lead times and enhance tender competitiveness.
-
For donors and procurement agencies: Use multi-year contracting where feasible to stabilize supplier revenues and incentivize capacity investments. Incorporate performance-based clauses for supply continuity and quality assurance to mitigate single-source risks identified in our supplier-risk matrix.
-
For investors and impact funds: Target opportunities that address non-antibiotic care gaps—wound-care technologies, bundled service providers, and rehabilitation models—where commercial returns can be structured around scarce competition and programmatic funding streams.
-
For NGOs and implementers: Strengthen linkages between clinical care, surveillance, and referral systems. Investing in training for wound management and physiotherapy can materially reduce the burden on surgical services and improve program cost-effectiveness.
Limitations and where to find the full intelligence
This briefing highlights macro-scale findings and strategic implications without disclosing the granular segmentation tables, regional breakdowns, or per-treatment revenue schedules that are included in the full PW Consulting report. Those detailed datasets—covering regional incidence mapping, per-segment revenue forecasts, supplier share by tender, and country-level tender calendars—are intentionally withheld here to preserve the report’s value as a source document and to encourage direct engagement with PW Consulting for bespoke advisory work.
Next steps for stakeholders
-
Procurement teams: Use the report’s tender-response templates and supplier-risk assessments to refine 2026 RFPs and multi-year contracts.
-
Manufacturers: Request the supplier prequalification gap analysis to accelerate dossier commitments and identify co-manufacturing prospects.
-
Investors and donors: Leverage the opportunity-mapping appendix to prioritize investments in wound-care innovation and service delivery pilots that can scale under existing program funding models.
PW Consulting’s Worldwide Buruli Ulcer Treatment Market report combines validated market sizing (base year 2025), an evidence-based forecast to 2032 at a 4.8% CAGR, and practical playbooks tailored for 2026 implementation. For complete segmentation data, country-level insights, and tailored advisory services, please consult the full report on the PW Consulting website or contact our advisory desk to arrange a briefing and licensed data access.
For detailed analysis of this topic, please visit the official page: Worldwide Buruli Ulcer Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com