

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide JAK Inhibitors Market Poised for 14.01% CAGR During 2026–2032

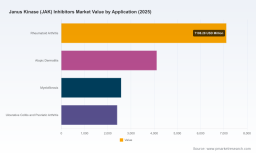
Worldwide Janus Kinase (JAK) Inhibitors Market: Strategic Imperatives for 2026 — PW Consulting Executive Release
PW Consulting’s newest market intelligence release — the Worldwide Janus Kinase (JAK) Inhibitors Market Report (base year 2025, forecast period 2026–2032) — equips life-science leaders with the forward-looking intelligence required to make high-stakes commercial, regulatory, and portfolio-allocation decisions in 2026. Our bottom‑line macro finding: the JAK inhibitors market reached USD 16.2 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 14.01% through 2032, when the market is expected to approach roughly USD 40.6 billion under our central scenario. This release purposefully blends rigorous, reproducible analytics with strategic interpretation, while reserving detailed segment-level tables and financial schedules for subscribers and licensed clients.
Inhalation Drug Delivery System Market
What the Report Provides — Practical, Transaction‑Ready Intelligence
- Proprietary quantitative forecast model (2026–2032) with scenario toggles for regulatory headwinds, generic entry timing, and accelerated clinical success; model delivered in a client-ready spreadsheet and supported by sensitivity matrices.
- Competitive landscape dossiers on the active commercial and clinical players, including portfolio positioning, launch-readiness, patent expiry timelines, and likely tactical responses to biosimilar/generic entry.
- Regulatory risk analysis detailing the long-term implications of safety communications (including boxed warnings), label expansions, and likely shifts in post‑market study commitments that will alter benefit/risk calculus for payers.
- Commercial playbooks for five commercialization archetypes — incumbent large pharma, late-stage challenger, specialty biotech, regional player, and generics/authorized‑generic entrant — each with go-to-market recommendations across pricing, contracting, and field deployment.
- Reimbursement and payer-access roadmaps, identifying practical contracting levers under Medicare Part D, value‑based pricing approaches, and dossier templates tailored for national and institutional payers.
- Supply‑chain and manufacturing risk assessment (API dependency, dual-sourcing contingencies, inventory thresholds) and recommended mitigation steps to protect launch and scale-up timelines.
- Deal and M&A screening criteria built on a concentration analysis of the market’s upper quartile and a curated list of priority in‑licensing and acquisition targets informed by unmet clinical needs and near‑term launch feasibility.
High‑Priority Strategic Takeaways for 2026
- Prioritize safety‑differentiation investments. Since the FDA’s boxed warning in 2021, the market has bifurcated along safety and selectivity narratives. Companies that can credibly demonstrate meaningful reductions in long‑term cardiovascular, thrombotic, or malignancy risks — through controlled trials or robust real‑world evidence (RWE) programs — will unlock premium contracting and expanded label opportunities.
- Prepare for a near‑term generics inflection. Patent expiries in the mid‑2020s materially change the competitive calculus for some established molecules. Firms should model both price erosion and share migration scenarios, and define defence strategies such as novel formulations, co‑pay assistance, or authorized‑generic agreements.
- Embed reimbursement strategy into early clinical planning. The convergence of payers’ demand for comparative effectiveness and CMS coverage policies means that Phase 3 design and post‑launch evidence generation must be optimized to support Part D coverage and high‑value contracting in 2026 and beyond.
- Hedge the supply chain. API constraints observed in 2023–2024 exposed vulnerability across the ecosystem. Tactical recommendations include dual geographic sourcing, qualifying multiple API vendors to regulatory standards, and stress‑testing inventory buffers against scenario shocks.
- Exploit concentrated market structure for targeted M&A. Market concentration metrics indicate that a small number of players command a dominant share of revenues; strategic buyers should evaluate bolt‑on assets that fill therapeutic gaps or extend lifecycle management, while sellers can time exits to capitalize on elevated valuations tied to growth visibility.
- Differentiate via indication strategy and route of administration. Dermatology and gastroenterology indications are presenting adjacent access and formulary pathways different from rheumatology; companies that craft indication‑specific commercial models will secure more durable uptake.
Competitive Landscape — Who Matters and Why
The market remains concentrated: the top three players account for a substantial majority of revenues, and the top five even more so. That concentration creates both defensive moats and transactional opportunities. Our report profiles each leading player with actionable strategic intelligence — a snapshot below highlights the dynamics most relevant to 2026 planning.
Worldwide Non-Native Database Management Systems Market
- Pfizer Inc. (New York, USA) — As the marketer of tofacitinib, Pfizer faces a pivotal transition as legacy product patents approach expiry. Their near‑term strategic choices will center on lifecycle defense, differentiated formulations, and potential authorized‑generic strategies to retain channel presence post‑patent. Recent pediatric label expansions underscore Pfizer’s commitment to line‑extension as a revenue management tool.
- Incyte Corporation (Wilmington, USA) — Incyte’s ruxolitinib (including topical formulations) has broadened into dermatologic niches. Continued execution on incremental approvals and topical assets could cement leadership in specific specialty subsegments where patient and prescriber preferences favor local therapies.
- Eli Lilly and Company (Indianapolis, USA) — Lilly’s baricitinib has moved into additional indications, including pediatric uses, strengthening multi‑indication franchises. Their ability to marry clinical differentiation with scalable commercial models positions them well in competitive tenders and payer negotiations.
- AbbVie Inc. (North Chicago, USA) — AbbVie’s late‑stage and approved launches reflect aggressive label expansion and cross‑indication play. Their integrated strategy spanning clinical development, field force optimization, and payer contracting makes them a formidable commercial competitor in the mid‑to‑near term.
- Gilead Sciences, Inc. (Foster City, USA) — Through partnerships, Gilead has selective market exposure. Their upstream capabilities in development and commercialization partnerships allow flexible market entry strategies without assuming full global launch risk.
- Conatus Pharmaceuticals / Roivant Sciences (San Diego, USA) — Emerging players and specialty biotechs are advancing differentiated mechanisms and combo approaches; their pipeline assets represent high‑upside targets for licensing or acquisition by incumbents seeking novelty beyond the current JAK portfolio.
Regulatory and Reimbursement Dynamics — Risk and Opportunity
Regulators and payers remain a central structural force shaping the JAK inhibitors market. The FDA’s boxed warning (2021) continues to influence labeling, physician prescribing behaviour, and payer coverage policies. At the same time, national coverage determinations and payer willingness to reimburse for specific inflammatory indications create pockets of robust access. Our report synthesizes these dynamics into practical guidance for dossier strategy, post‑launch evidence generation plans, and payer engagement timelines to maximize formulary inclusion starting in 2026.
Worldwide Microlens Arrays Market
Clinical Development and Supply Chain — Timeline Sensitivities
Ongoing Phase 3 programmes and remaining clinical readouts represent both upside catalysts and timeline sensitivities. The report includes a timeline‑aware pipeline tracker and confidence grading for near‑term approvals. Coupled with a supply‑chain stress test that models API disruption scenarios observed in 2023–2024, this work enables commercialization teams to plan inventory and launch sequencing with precision.
How PW Consulting Helps Executives Execute in 2026
- Model licensing and workshops: we deliver the forecast model with a hands‑on workshop to stress‑test clients’ internal assumptions and to calibrate business plans to both conservative and aggressive market scenarios.
- Custom market-entry advisory: for companies pursuing product launches or strategic licensing, we provide bespoke payer dossiers, pricing playbooks, and a prioritized list of local partners and CRO/CDMO options.
- Transaction support: for M&A or licensing, our target screening tool overlays clinical maturity, commercial fit, and acquirer synergies against market concentration and projected value trajectories, accelerating deal certainty.
Conclusion — Why This Report Matters for 2026 Decisions
Entering 2026, the JAK inhibitors market offers substantial growth but is subject to concentrated competitive forces, regulatory scrutiny, and supply‑chain fragility. PW Consulting’s report is designed to convert these complexities into a readable, action‑oriented set of choices: which clinical bets to accelerate, how to defend revenues against generic erosion, where to invest in evidence generation, and which commercial plays maximize return under varied payer regimes.
This brief intentionally showcases the analytical depth and strategic pathways contained in the full report while reserving granular region‑ and indication‑level tables and transaction‑grade financial schedules for the published report package. For executives preparing budgets, negotiating heartland contracts, or evaluating M&A in 2026, accessing the full dataset and model is essential. To request the full report, interactive model, or a briefing with our lead analysts, please visit the PW Consulting market research portal or contact our client services desk to schedule a private walk‑through.
For detailed analysis of this topic, please visit the official page: Worldwide Janus Kinase (JAK) Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com