

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Glaucoma Diagnostics Market Set to Expand at a 5.01% CAGR, New Report Reveals

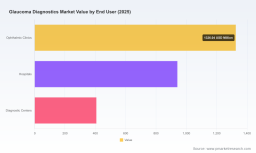
Worldwide Glaucoma Diagnostics Market: Strategic Imperatives for 2026 — PW Consulting Brief
Executive summary
As PW Consulting’s lead industry analyst, I present a concise strategic briefing on the Worldwide Glaucoma Diagnostics Market that is designed to inform executive decisions in 2026. Using a detailed base of historical data (2020–2025) and a transparent forecasting framework (2026–2032), our analysis shows that the market reached approximately USD 2,674.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of about 5.01% into the forecast period. By the end of our horizon, the market trajectory reflects continued demand for precision imaging, remote monitoring, and integrated diagnostic workflows—forces that will reshape product roadmaps, channel strategies, and M&A priorities in the coming 12–18 months.
Worldwide Express and Parcel (CEP) Market
Why this briefing matters for 2026 decision-makers
- Time-sensitive prioritization: 2026 will be the first year many product and commercialization initiatives launched during 2024–2025 reach scale—executives must decide where to double down and where to course-correct.
- Investment and M&A screening: With a mid-single-digit CAGR and a moderately consolidated supplier landscape, acquirers can identify adjacencies (AI, home-monitoring, service-led revenue) that accelerate value creation.
- Regulatory and reimbursement readiness: Several recent product approvals and evolving CPT/Medicare payment dynamics make regulatory strategies and coding optimization critical to capture near-term revenue.
- Operational leverage: Field-service, SaaS analytics, and remote patient monitoring are now differentiators—companies that operationalize these will capture a disproportionate share of incremental value.
What the full report delivers (practical, roll-up-your-sleeves content)
- Transparent market architecture and methodology — our models reconcile historical vendor shipments, published manufacturer revenues, and primary-provider interviews to produce a reproducible top-down and bottom-up sizing by year.
- Scenario-driven forecasts — base, upside and downside scenarios tied to regulatory timelines, reimbursement shifts, and technology adoption curves.
- Competitor scorecards — feature parity matrices across imaging, tonometry, perimetry, and AI-enabled analytics; supplier SWOTs; and go-to-market archetypes for incumbents vs. challengers.
- Commercial playbooks — segmented sales strategies for hospitals, outpatient clinics and diagnostic centers; pricing and tender guidelines; and service agreement templates to protect margin in PDx-heavy deals.
- Regulatory & reimbursement dossier — device classification pathways (including likely 510(k) timelines), key CPT codes and payer levers, plus a map of clinical evidence required to support higher reimbursement bands.
- Executable M&A and partnership pipeline — screen of strategically attractive targets, value levers, and integration risks with financial sensitivity analyses.
- Deliverables — editable financial model (USD Million), executive dashboard visualizations, and an annex of primary interview excerpts for due diligence.
Competitive landscape — who is shaping the market
The market shows moderate concentration: the top three players control a meaningful share of revenue, while the top five increase the share further, underscoring a dual dynamic of strong incumbents and specialized challengers. Incumbent device OEMs remain influential through deep installed bases and clinical partnerships; at the same time, software and connectivity players are eroding barriers to entry.
Worldwide Forestry Trailers Market
- Zeiss (Germany) — A continued focus on OCT systems and progression analytics positions Zeiss as a category leader. Its recent launch of an enhanced OCT platform with upgraded glaucoma analytics highlights the vendor’s strategy to tie hardware sales to recurring analytics and services.
- Heidelberg Engineering (Germany) — With iterative software releases integrating AI-based progression detection, Heidelberg is pursuing a software-led differentiation that increases the lifetime value of installed systems.
- Topcon (Japan) — By combining swept-source OCT hardware with AI-enhanced visual field analyzers and obtaining recent regulatory clearances, Topcon is moving to a unified diagnostic workflow play that shortens clinical decision cycles.
- Nidek and Canon Medical Systems (Japan) — These OEMs maintain a steady cadence of instrument innovation across tonometry and imaging, emphasizing reliability and clinic workflow integration.
- Reichert Technologies and Haag-Streit — Both continue to defend specialty niches—applanation and corneal biomechanics—and are making incremental connectivity and usability gains to maintain relevance in hospital deployments.
- iCare (Finland) and Carelon Medical Technologies (USA) — Representing the “lightweight” device and AI-enabled portable imaging segment, these companies are notable for home-monitoring studies and AI-enabled screening cameras that lower the barrier to frequent patient assessment.
Recent vendor activity makes several strategic points clear: hardware manufacturers are investing in analytics and connectivity; perimetry vendors are introducing AI to accelerate interpretation; tonometer providers are adding wireless and home-capable options; and software-first entrants are targeting fragmentary workflows to stitch together longitudinal patient records.
DALI Dimming Power Supply Market
Regulatory and reimbursement landscape — immediate constraints and enablers
- FDA pathways remain a gating factor: non-contact tonometers fall under Class II and generally require 510(k) clearance, which influences launch sequencing and clinical trial design.
- Reimbursement is granular and procedure-driven: specific CPT codes that capture optic nerve imaging and visual field testing remain key levers. For context, confocal optic nerve procedures and routine visual field testing reimburse at modest fixed rates under Medicare, so commercial models that rely solely on per-test reimbursement face margin pressure without bundled or value-based arrangements.
- Standards and device performance norms continue to matter: ISO and equivalent standards for applanation tonometers and tonometry accuracy guide product acceptance in hospital procurement, and compliance is often a precondition for large tenders.
Strategic implications by capability
- Product roadmap — Prioritize investments in AI analytics that improve clinical sensitivity/specificity and support label expansion. Integrate connectivity and remote monitoring capabilities to enable subscription revenue.
- Regulatory strategy — Map 510(k) and clinical evidence requirements early; where possible, design trials to generate data useful for payers as well as regulators.
- Reimbursement and pricing — Pursue bundles and service agreements that capture value beyond per-procedure fees; demonstrate cost-of-care improvements to justify higher margins.
- Commercial model — Build managed-service offerings for high-value clinical accounts; train sales teams to sell clinical outcomes, not just equipment specs.
- Partnerships & M&A — Target analytics players, home-monitoring device makers, and service-platform companies to accelerate time-to-market for integrated solutions.
High-impact near-term opportunities to prioritize in 2026
- Scale AI-enabled progression modules as a retrofit revenue stream for installed OCT bases—this increases ARPU without heavy capital deployment.
- Commercialize proven home-monitoring devices with bundled remote monitoring services for chronic glaucoma patients; this reduces clinic burden and creates sticky revenue.
- Offer combined imaging + visual-field analysis bundles to outpatient clinics to simplify procurement and accelerate decision-to-purchase cycles.
- Pursue selective partnerships with payers or large hospital systems to pilot value-based reimbursement tied to reduced sight-loss progression.
- Invest in field service and training programs to differentiate on uptime and clinician adoption—service-led differentiation is becoming a decisive procurement factor.
Conclusion — how PW Consulting’s report turns insight into action
The 2026 inflection point requires leaders to translate steady market growth into strategic advantage. Our report provides the executable inputs you need: a validated market size and growth outlook, scenario-tested strategies, vendor playbooks, and a prioritized list of tactical moves that can be executed within a 12–24 month window. We intentionally withhold core subsegment figures in this public briefing to preserve the commercial utility of the full dataset; the complete report contains granular, auditable splits by product, end user and region, together with an interactive model you can license for due diligence, planning and M&A screening.
To access the full Worldwide Glaucoma Diagnostics Market report, including the complete segmentation tables, vendor revenue breakdowns, and the downloadable financial model (USD Million), please visit PW Consulting’s report page or contact our research team to schedule a briefing. Our consultants stand ready to tailor the analysis to your 2026 strategic planning cycle and to support rapid execution of the high-impact opportunities outlined above.
For detailed analysis of this topic, please visit the official page: Worldwide Glaucoma Diagnostics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com