

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Used & Refurbished Telehandler Market Valued at USD 3,185.5 Million in 2025, Set to Reach USD 4,730.04 Million by 2032 on a 5.81% CAGR

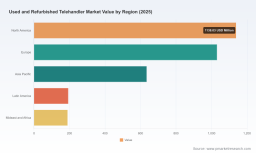
Worldwide Used and Refurbished Telehandler Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting's latest market study on the Worldwide Used and Refurbished Telehandler Market provides a practical, forward-looking playbook for executives, procurement leaders, rental operators, OEM strategists and private investors preparing for 2026. The used and refurbished telehandler sector has moved beyond a marginal resale channel to become a strategic lever for capital efficiency, supply-chain resilience and service-led differentiation. Our report quantifies this evolution and translates it into decision-ready scenarios — while reserving the granular segment-level tables and proprietary pricing curves for subscribers.
Structured Illumination Microscopy Market
Macro trajectory: why 2026 is an inflection year
The market for used and refurbished telehandlers has shown steady, above-inflation expansion through the first half of the decade and remains on a robust multi-year growth path. PW Consulting’s base-year analysis shows the global market at approximately USD 3,185.5 Million in 2025, up from roughly USD 2,405.6 Million in 2020. Our model projects continued expansion across the forecast window, reaching an estimated USD 4,730.0 Million by 2032 — a compound annual growth rate of 5.81% from 2026 onward under the base scenario.
Worldwide Massage Therapy Software Market
For corporate planners in 2026, that trajectory means used/refurbished telehandlers are no longer an afterthought for managing fleet cycles; they are a core asset class with predictable growth, improving liquidity and increasing acceptance across construction, agriculture and industrial end-users. The growth profile supports strategic investments in certified refurbishment programs, telemetry-enabled pre-owned warranties, and scaled rental-to-own offers that convert short-term utilization into repeat service revenues.
AGV & Forklift Battery Market
Primary market dynamics shaping near-term strategy
-
Cost and input pressures: Steel and other raw-material dynamics materially influence refurbishment economics. Mid-2025 pricing for hot-rolled coil stabilized in the low‑to‑mid $800s per short ton in the U.S. Midwest, and tariff adjustments and scrap-metal availability continue to feed into component replacement and structural repairs. Firms that lock in supply or invest in modular repair techniques will sustain margin advantages.
-
Regulatory and safety drivers: Updated OSHA requirements effective in 2025 increase emphasis on operator certification, digital documentation and inspection records for equipment classified within rough-terrain forklift categories. These compliance requirements create demand for certified refurbishment, digital logging systems and training services — all opportunities to monetize trust in the used market.
-
Rental model expansion: Contractors are accelerating a shift from ownership to flexible access. Rental operators and OEM-backed rental fleets are using refurbished telehandlers to balance utilization, reduce upfront capital for customers and create upgrade cycles that feed the certified pre-owned channel.
-
Product and technology upgrades: The ConExpo 2026 cycle underscored advances in smarter controls, enhanced stability systems and telematics integration across telehandler platforms. These features materially affect refurbishment scope — from sensor recalibration to software re-certification — and increase the value of a certified refurbishment stamp for resale and rental customers.
Competitive landscape and strategic implications
The used and refurbished telehandler market is moderately concentrated but remains contestable. PW Consulting’s concentration analysis indicates the top three OEMs collectively hold a meaningful but not dominant share of market influence, with the top five increasing that influence further. This structure creates a two-track competitive environment:
-
OEM-led certified channels: Major manufacturers — including established telehandler specialists and diversified construction-equipment OEMs — are formalizing certified used programs. Examples include the global dealer-backed programs from manufacturers with deep construction and agriculture footprints, which emphasize inspected, refurbished units with warranty and parts support. These programs raise the floor on buyer expectations for traceable refurbishment quality.
-
Independent refurbishers and rental-integrated sellers: Independent specialists and rental fleet operators remain critical to market depth. They compete on turnaround time, geographical reach, and cost flexibility. Synergies between rental models and refurbishment services allow faster asset rotation and better data on lifecycle costs, which informed operators can convert into margin through targeted service contracts.
For executives assessing partnerships or M&A in 2026, the strategic questions are clear: acquire a high-throughput refurbishment center to secure supply and control quality, or partner with OEM-certified dealer networks to access warranty-backed buyers? The right answer will depend on a firm’s capital profile, geographic ambition and access to technical talent for advanced inspections and telematics-enabled pre-sales reconditioning.
Company-level positioning: succinct profiles and observed trends
-
JCB — Longstanding global dealer networks provide scale in moving refurbished inventory across construction and agriculture verticals. Their brand recognition supports price resilience for certified pre-owned units.
-
Caterpillar — A broad Cat Used program, backed by intensive inspection and dealer-level refurbishment, targets heavy-duty applications and institutional buyers seeking turnkey support and parts availability.
-
Manitou Group — Deep experience across MT and MLA series gives Manitou leverage in both construction and agricultural refurb channels, with product families that are frequently traded in used markets.
-
JLG (Oshkosh) — Rental and dealer ties emphasize rotating and compact telehandler availability, particularly in North America, where shortened supply chains increase the role of refurbished units.
-
Specialist European OEMs (Merlo, Dieci, Liebherr, etc.) — These firms differentiate on specialized capabilities (e.g., rotating telehandlers, high-lift performance) and maintain robust refurbishment programs for premium segments.
-
Generalist and agricultural players (CNH / New Holland, Claas, Wacker Neuson, Haulotte, Bobcat) — These companies supply high-volume used inventory into farm and light construction markets, enabling cross-sell into parts and service contracts.
Collectively, these manufacturers and networked resellers define both the supply of refurbishable assets and the standards buyers expect. Our competitive maps in the full report show dealer overlap, certified program footprints, and fleet-aging hot spots by platform family — information that is essential when deciding where to deploy refurbishment capital.
What PW Consulting’s report delivers to your 2026 playbook
We designed the study to be an operational toolkit rather than an academic exercise. Key deliverables include:
-
Proprietary market-sizing and scenario models (base, downside and upside) that translate macro indicators — steel pricing, tariff moves, rental penetration and regulatory compliance costs — into five-year cash-flow and working-capital outcomes for refurbishment centers and rental fleets.
-
Decision matrices for CapEx allocation: build vs partner vs outsource, with break-even horizons at different utilization and margin assumptions.
-
Service and parts economics: roadmaps to margin expansion through certified warranties, telematics-monitored maintenance plans and modular repair processes that reduce turnaround time.
-
Competitive footprint maps and a dealer-refurbisher directory, enabling targeted M&A screening and regional go-to-market planning.
-
Regulatory compliance playbooks: implementation templates to meet enhanced operator-certification and digital-documentation requirements, minimizing downtime and liability risk.
-
Valuation multiples and resale curves for asset-class modeling—used by CFOs to optimize fleet disposal timing and to structure rental contracts with residual-sharing mechanisms.
To preserve marketplace advantage for report subscribers, PW Consulting does not publish granular region/application split tables or unit-level price ladders in this briefing. Those elements are available in the full dataset and interactive dashboards, which contain the actionable numbers procurement teams and investors will use to execute in 2026.
Recommended strategic moves for 2026
-
Prioritize certified-refurb capability: Establish or partner with one certified refurbishment center per major operating region to capture premium resale and warranty revenue streams.
-
Hedge raw-material exposure: Secure supplier contracts for high-strength steel inputs and consider recyclable-material sourcing strategies to reduce cost volatility from tariffs and market swings.
-
Invest in telematics and digital traceability: Buyers place a premium on documented maintenance history. Integrate telematics retrofits into refurbishment scope to lift resale multiples and enable usage-based warranties.
-
Embed compliance into the service offer: Use OSHA-aligned inspection and certification as a value-added service that differentiates refurbished units from commodity used equipment.
-
Design rental-to-refurb pipelines: Coordinate fleet renewal cycles so rental operators feed steady, refurbishable inventory into certified channels — shortening time-to-market and stabilizing margins.
Conclusion — action and where to get the intelligence
As the telehandler lifecycle becomes a strategic tool for capital-intensive buyers and rental operators, 2026 will be the year many organizations choose to formalize refurb strategy — either by investing in internal capabilities or by forging decisive channel partnerships. PW Consulting’s report quantifies the market growth trajectory, maps the competitive field and supplies the analytic frameworks needed to translate market signals into executable plans.
For access to the full dataset, interactive models, regional and application-level breakdowns, dealer matrices and the proprietary valuation curves that underpin our recommendations, request the full Worldwide Used and Refurbished Telehandler Market report from PW Consulting. The detailed intelligence is designed to be operationally prescriptive for the budgets and capital plans you will set in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Used and Refurbished Telehandler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com