

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automatic Weapons Market to Reach USD 14,853.48 Million by 2032 (7.0% CAGR) as North America Leads with USD 3,381.69M

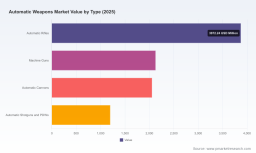
Worldwide Automatic Weapons Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market research into the Worldwide Automatic Weapons Market confirms a clear strategic trajectory: after a period of fluctuation in the early 2020s, the industry has returned to growth momentum. The global market reached an estimated USD 9.25 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 7.0% through our 2026–2032 forecast horizon. For executives weighing capital allocation, capability development, and go-to-market choices in 2026, this report positions those decisions within a robust, but structurally evolving, market reality.
Worldwide Application Transformation Market
Why 2026 is an inflection year
Two converging dynamics make 2026 a pivotal planning year. First, modernization programs across multiple defense organizations — driven by requirements for increased lethality, range, and integration with digital systems — are producing sustained procurement pipelines that favor next‑generation small arms and automatic weapon systems. Second, shifts in supply‑side economics and export control frameworks are raising both risk and opportunity for manufacturers and system integrators.
Worldwide Music Notation Software Market
-
Demand signal: New program milestones and ongoing U.S. and allied modernization initiatives are spawning multi-year acquisition windows for platforms, ammunition, and integrated weapon‑turret systems.
Containerised Solar Solution Market -
Supply signal: Raw material cycles and industrial capacity constraints are compressing supplier margins for key inputs. Procurement teams must price and hedge with greater precision than in prior years.
-
Regulatory signal: Updates to multilateral control lists and national export licensing practice are increasing program complexity and the cost of compliance, particularly for cross-border collaboration and dual‑use component sourcing.
Market trajectory and what it means for strategy
After recovering from mid‑cycle volatility, the market’s near‑term expansion at roughly 7% CAGR supports selective investment in capability upgrades, but not indiscriminate capacity expansion. The topline growth underwrites reinvestment into R&D, digital integration (sensors, fire-control, and soldier systems) and aftermarket services; however, it also highlights the premium on disciplined portfolio management to protect margins as raw‑material and compliance costs rise.
Key dynamics shaping 2026 decisions
-
Supply‑chain economics: Prices for commodity inputs such as hot‑rolled coil steel — a core input for barrels, receivers and related components — remain challenged by global overcapacity. This compresses supplier margins and shifts emphasis to process efficiency, higher‑value alloys, and supplier consolidation strategies.
-
Export and compliance complexity: Updates to international control lists and continuing revisions to national export licensing frameworks mean firms must bake regulatory intelligence into early program planning. Licensing timelines, technical data transfer restrictions, and end‑user vetting will materially affect lead times and contract competitiveness.
-
Technology-driven differentiation: Programs emphasizing extended‑range small arms, improved suppression, and integration with networked targeting systems are creating premium niches. Winning here requires demonstrable systems integration capability and rigorous lethality/accuracy validation under realistic operational conditions.
-
Concentration and competitive dynamics: The industry remains moderately consolidated; the top three global players account for a significant share of industry revenues and the top five increase that concentration further. That concentration creates both barriers for new entrants and M&A opportunities for players seeking scale in production, engineering, or access to program pipelines.
Competitive landscape — what the major players are doing
The market is populated by a blend of legacy platform manufacturers, munition and turret specialists, and integrated defense prime contractors. Several strategic patterns are worthy of attention for 2026:
-
Platform modernization and modularity: Established rifle and machine‑gun manufacturers are advancing modular architectures to capture multi‑service requirements and aftermarket revenue. Recent product launches emphasize suppressor compatibility, modular caliber options, and improved ergonomics aimed at rapid field reconfiguration.
-
Program milestones and procurement wins: Approval and type classification milestones on major defense programs materially change production profiles and supplier bargaining power. Firms that secure such milestones typically transition rapidly into scale production, aftermarket support, and associative supply‑chain lock‑in.
-
Integration into platforms: Larger defense primes are pushing automatic weapons as integrated subsystems — paired with turrets, naval CIWS, and aircraft‑mounted pods — leveraging broader systems contracts to grow share beyond standalone small arms.
-
Regional and niche specialization: Several firms have doubled down on regionally tailored offerings or specialized anti‑material/cannons segments, creating defensible niches that command specialized procurement budgets.
Our company profiles in the full report analyze these strategic moves in depth across leading manufacturers and system integrators, offering direct comparisons of product roadmaps, production footprints, and program exposure.
What PW Consulting’s report provides (practical, actionable content)
This research is built for decision-makers who must translate market intelligence into executable strategy. Key operational tools included in the report are:
-
Top‑down market sizing and growth scenarios calibrated to alternative procurement and commodity cost paths — enabling portfolio stress‑testing under differing macro and policy assumptions.
-
Competitive benchmarking and program exposure matrices that map firm capabilities to major modernization initiatives, highlighting potential supplier bottlenecks and partnership opportunities.
-
Commercial playbooks for prime contractors, subsystem suppliers, and new entrants — covering pricing strategy, offset and industrial participation structuring, and contracting tactics for multi‑year procurement frameworks.
-
Regulatory and compliance toolkit that synthesizes recent control‑list changes and export licensing trends into a practical checklist for program managers and export control officers.
-
Supply‑chain risk maps with mitigation options: hedging approaches for raw‑material price volatility, dual‑source and nearshoring scenarios, and supplier consolidation pathways to reduce lead‑time exposure.
To remain a “trailer” rather than a full disclosure, we are intentionally reserving the granular segment splits, contract‑level forecasts, and downloadable data tables for authorized subscribers and purchasers of the full dataset.
Actionable recommendations for 2026 — C-suite priorities
-
Refocus R&D toward systems integration: Invest where weapon lethality is coupled with sensor and sustainment ecosystems. Demonstrated integration with fire control and soldier systems shortens procurement decision cycles.
-
Prioritize regulatory and export excellence: Build or buy export‑control expertise and integrate it early in program design to protect delivery schedules and avoid costly rework.
-
Optimize supply‑chain posture: Move from price‑only sourcing to value‑based supplier partnerships that secure quality, capacity, and traceability for critical inputs. Consider selective nearshoring for long‑lead components where export controls create single‑supplier risk.
-
Prepare for M&A and alliance plays: Use the market’s moderate concentration to pursue targeted acquisitions that add capacity, certification access, or geographic offset capabilities — particularly where primes seek turnkey offerings for platform integration.
-
Monetize aftermarket and services: With procurement cycles stretching into multi‑year sustainment, firms should build predictable annuity models around training, spares, and upgrades to stabilize margins through commodity cycles.
How to use the full PW Consulting dataset
Senior leaders should treat the full report as a playbook and a modeling engine: use its scenario modules to stress‑test bid pricing, apply its competitive exposure matrix to prioritize business development, and deploy the compliance toolkit to redesign contracting timetables. For procurement and program teams, the report’s contract pipeline tracker and supplier risk maps are designed to be operational tools you can incorporate into quarterly planning cycles.
Closing — why this report matters in 2026
With the market re‑accelerating and a complex overlay of materials, regulatory, and technological change, 2026 will reward organizations that pair focused capability investment with disciplined commercial and compliance practices. PW Consulting’s Worldwide Automatic Weapons Market report combines market-scale modeling (topline growth and forecast horizon), competitive intelligence, regulatory synthesis, and practical playbooks to inform these choices. We provide the strategic view; the granular segment data and transaction-ready models are available through our full subscription offering for teams ready to act.
Contact PW Consulting to request the full report and access the downloadable datasets, scenario models, and commercial playbooks that translate this high‑level briefing into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Weapons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com