

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pancreatic & Biliary Stent Market Hits USD 572.4M in 2025, Eyes 6.45% CAGR to USD 886.6M by 2032

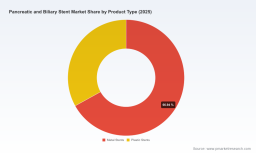
PW Consulting — Strategic Brief: Worldwide Pancreatic and Biliary Stent Market (Executive Preview for 2026 Decisions)
PW Consulting today releases an executive preview of our new report on the Worldwide Pancreatic and Biliary Stent Market. Built on a base year of 2025 with a 2026–2032 forecast horizon, the study combines granular primary research with a transparent market model and scenario analysis. At the aggregate level the market is projected to expand from approximately USD 572.4 Million in 2025 to an estimated USD 886.6 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.45% over the forecast period. These headline numbers provide the directional context for strategic choices in 2026 — but the true value for executives is in the applied analysis, competitive mapping, and executable playbooks contained in the full report.
Obstruction Lights Market
Why this report matters for 2026 strategic decisions
-
Timing matters: recent regulatory clearances and first-in‑country clinical use events mean 2026 is an inflection year for product rollouts and channel strategies. Companies that align regulatory, clinical and reimbursement efforts now will secure first-mover advantages in key treatment settings.
Worldwide Proactive Notification Software Market -
Portfolio prioritization: the market is sufficiently consolidated that focused investment in differentiated materials, delivery systems, or temporary biodegradable solutions can materially change competitive positioning. Our report helps executives prioritize R&D and commercial spend against realistic adoption curves.
Worldwide Headless CMS Software Market -
M&A and partnership windows: high concentration among established OEMs — with three firms collectively capturing a substantial portion of the market and the top five controlling a dominant share — makes targeted bolt-on acquisitions and distribution alliances an efficient route to scale. The report identifies sensible targets and valuation heuristics for 2026 deal-making.
-
Reimbursement and procedure coding will drive economic access. With ERCP procedures and hospital outpatient payment frameworks shaping hospital adoption, a coordinated clinical-economic value story is essential. We map the CPT/APC context and offer negotiation playbooks for 2026 contracting.
Key market dynamics and growth drivers
Macro demand is being driven by an aging population, rising procedural volumes for endoscopic retrograde cholangiopancreatography (ERCP), expanded adoption of minimally invasive management of ductal obstruction, and ongoing clinical interest in temporary versus permanent stent solutions. On the supply side, regulatory pathways and sterility/packaging compliance act as gating factors for new entrants: biliary and pancreatic stents remain regulated as Class II devices under the current FDA framework, requiring 510(k) demonstration of substantial equivalence and adherence to established sterile packaging standards.
Material science continues to shape product strategy. Nitinol-based self‑expanding metal stents (SEMS) are valued for thermal memory and corrosion resistance, while polymeric plastics (polyethylene, polyurethane) remain the workhorse for many plastic stent designs. Biodegradable materials have transitioned from R&D curiosity to commercial reality, opening new trade-offs between temporary drainage convenience and cost/clinical support requirements.
Technology and product trends to watch in 2026
-
Biodegradable stents: The first FDA-cleared biodegradable pancreatic stent has moved from clearance to clinical use, signaling an opening for temporary-device strategies that reduce the need for secondary removal procedures. Expect competition on both material composition and resorption profiles.
-
Delivery systems and enhanced deliverability: Recent regulatory clearances emphasize deliverability and deployment control. Endoscopist workflow impacts adoption; companies that reduce procedural time and complication rates will gain share.
-
Hybrid portfolios: OEMs are balancing plastic stents, SEMS, and biodegradable options to cover acute, palliative, and temporary use cases. Strategic product line design and clear labeling for indications will be differentiators in tender and hospital contracting.
-
Clinical evidence generation: randomized and registry-level data that demonstrate reduced migration, improved drainage durability, or lower overall cost of care will accelerate uptake. Programs that integrate real-world evidence collection into commercialization plans will shorten payor conversations.
Recent corporate and regulatory milestones shaping 2026
-
July 2025 — Q3 Medical Devices received FDA 510(k) clearance for a biodegradable pancreatic stent; this was followed by the first documented U.S. clinical procedure using the device in January 2026. Such steps convert regulatory clearance into tangible market signals.
-
October 2025 — Boston Scientific received 510(k) and CE Mark clearances for an enhanced-deliverability biliary plastic stent and initiated international launch activity, with phased U.S. rollout plans. These product-level movements emphasize the continuing importance of incremental innovation and staged market entry.
-
October 2025 — Olympus expanded its endotherapy portfolio through an exclusive distribution arrangement for a well-known biliary endoprosthesis, underscoring distribution partnerships as a fast route to fill portfolio gaps.
-
April 2026 — Additional 510(k) clearances for biliary and pancreatic stent sets emphasize that regulatory momentum is sustained into 2026, raising the bar for clinical and commercial preparedness among entrants.
Competitive landscape — qualitative positioning and implications
The pancreatic and biliary stent market presents a mixed competitive topology. Large integrated medtech players leverage broad endoscopy portfolios, global distribution, and purchasing relationships with hospital systems. Specialist stent manufacturers and nimble innovators compete on specific design attributes, material differentiation, and focused clinical programs. Regional and cost-focused manufacturers supply lower-cost alternatives in price-sensitive markets, often through distributor networks.
Strategically, incumbents benefit from installed clinical support, multi-product contracting, and scale manufacturing. New entrants and smaller innovators rely on differentiation (biodegradable materials, novel delivery control) and regulatory agility. For corporate strategy teams, this means the go-to-market choice is rarely binary: successful plans often combine selective licensing, distribution partnerships, and targeted clinical investments rather than full organic rollouts.
Our market concentration metrics reinforce this reality: the three leading firms command a material share of the market, and the top five account for a dominant proportion. This structure creates defensible positions but also attractive acquisition targets for companies seeking rapid capability gains.
Actionable playbook for executive teams in 2026
-
Align regulatory and clinical timelines: synchronize 510(k)/CE processes with prospective clinical registry launches and payer engagement so product availability coincides with reimbursement readiness.
-
Prioritize clinical outcomes that payers value: design studies that capture not only technical success but also downstream resource use (reinterventions, hospitalization days, device removal procedures).
-
Mitigate raw material and supply risks: establish dual-sourcing or long-term supply agreements for nitinol and key polymers; build sterility and packaging validation into supplier contracts to avoid commercialization delays.
-
Use channel partnerships selectively: where direct sales are costly, consider exclusive distribution deals or OEM partnerships to accelerate market entry in geographies with tight clinical networks.
-
Build reimbursement dossiers early: map CPT/DRG/APC implications and prepare hospital submittals; use economic models to demonstrate value under outpatient payment frameworks.
-
Set a pragmatic M&A checklist: prioritize targets with complementary regulatory clearances, installed KOL relationships, or manufacturing capabilities that close specific gaps in your product roadmap.
What the full PW Consulting report delivers (practical features)
-
A transparent, model-driven market sizing and forecast with downloadable Excel workbooks and sensitivity scenarios that allow you to test alternate adoption and pricing assumptions.
-
Regulatory and reimbursement playbooks, including step-by-step timelines for 510(k) strategy, sterility/packaging expectations, and CPT/APC implications relevant to hospital contracting.
-
Competitor benchmarking dossiers and acquisition target screening matrices that combine technology, regulatory status, commercial reach, and margin profile.
-
Market-entry and commercialization playbooks for four archetypal strategies (incumbent expansion, focused innovator, cost-leader/distributor model, and acquisition-led scale), each with go/no-go decision criteria and resource estimates.
-
Supply chain and raw-material risk assessment, including mitigation templates for nitinol and polymer sourcing, sterilization validation checklists, and estimated time-to-scale for new capacity.
-
Clinical evidence templates, KOL engagement plans, and a prioritized list of registries and trial designs proven to move hospital formulary committees.
Next steps — where to get the complete intelligence
This executive preview is intended to surface the strategic choices and commercial priorities that will define success in 2026. For teams preparing investment memoranda, commercial launch plans, or M&A diligence, the full Worldwide Pancreatic and Biliary Stent Market report contains the granular segmentation, interactive financial model, and proprietary company scoring that will support operational decisions. Visit the PW Consulting report page to request the full dataset, download the model, or arrange a tailored briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Pancreatic and Biliary Stent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com