

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Military Floating Bridge Market Poised for 5.12% CAGR Through 2032

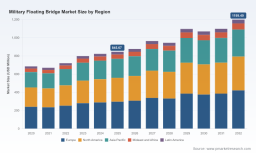
Worldwide Military Floating Bridge Market — Strategic Outlook for 2026 Decision-Makers
Executive Preview
As defense planners and procurement executives prepare budgets and capability roadmaps for 2026, the market for military floating bridge systems is taking on renewed strategic importance. PW Consulting’s latest market study shows a resilient, steadily expanding global market characterized by moderate compound annual growth, increasing interoperability requirements across allied forces, and concentrated supplier power in a handful of specialist manufacturers. This briefing highlights the report’s strategic value for 2026 decision-makers: what to watch, what to factor into acquisition decisions, and where to go for the granular data required to justify programs and supplier selections.
Worldwide Small Business eCommerce Software Market
Market snapshot: scale, trajectory, and the pace of change
After a period of cyclical investment from 2020–2025, the global market for military floating bridges enters 2026 with momentum. Our time-series model shows recovery and expansion since 2020 and forecasts a continued rise across the 2026–2032 horizon at a mid-single-digit CAGR. In practical terms, procurement volumes and supplier revenues in this sector are growing sufficiently to sustain multiple sustained modernization programs across NATO and allied partners, while creating new opportunities in regions prioritizing rapid-deployment amphibious and wet-gap capability.
Worldwide Air Inflation Flotation Cell Market
- Growth trajectory: the market’s forecast growth rate underscores predictable, program-driven demand rather than ephemeral spikes — a key point for planners seeking multi-year sustainment contracts and lifecycle funding profiles.
- Market structure: our concentration analysis shows that the market is led by a small number of specialized OEMs. The top three suppliers account for roughly half of global revenue, with the top five approaching two-thirds — a structure that favors deep-technology incumbents but leaves room for niche entrants with differentiated value propositions.
- Demand drivers: rising defense budgets, NATO interoperability projects, and expeditionary operations requirements are the dominant demand vectors shaping procurement in 2026 and beyond.
Why 2026 is a pivotal year for capability decisions
Several interlocking dynamics make 2026 the inflection point to convert strategic intent into contract actions:
Rail Traction Transformers Market
- Joint procurement programs and interoperability initiatives are converging on common capability baselines — creating opportunities for pooled procurement, common logistics chains, and standardized training programs across allied formations.
- Modernization programs for armored brigades and engineer formations are prioritizing rapid-deployment modular solutions that are compatible with current Military Load Classification (MLC) norms.
- Manufacturers are scaling production and field support for next-generation modular systems, prompting procurement authorities to balance near-term availability against longer-term capability growth.
Operational drivers shaping technical requirements
From a system engineering and operations perspective, several technical and doctrinal factors are converging to shape procurement specifications for 2026:
- Materials and survivability: aluminum alloys and high-grade steels remain the dominant choice for pontoons and structural elements due to strength, corrosion resistance, and modularity requirements. Design trade-offs between weight, transportability, and load-carrying capacity continue to drive engineering decisions.
- MLC compliance and vehicle compatibility: systems must align with recognized military load-class standards to ensure cross-platform compatibility. This constraint influences the modular architecture, launch/recovery systems, and handling equipment included in procurements.
- Rapid deployment and mechanization: motorized and amphibious bridge rigs that reduce assembly time and expose personnel to less risk in contested environments are high priorities for end users — particularly where wet-gap crossings must be accomplished under time pressure or in degraded environments.
- Training and sustainment: modular systems with common spare-part families and well-documented operator/trainer packages materially reduce total cost of ownership and accelerate initial operational capability timelines.
Competitive landscape — who matters and why
The supply base is comprised of established engineering houses and a selection of regional manufacturers. Our qualitative assessment of major vendors highlights capabilities, strategic positioning, and near-term program exposure:
- CNIM Systèmes Industriels (France): A specialist in motorized floating bridge solutions with in-service platforms supporting heavy combat vehicles. CNIM’s recent program awards and delivery pipelines reinforce its profile as a capable integrator for national engineer formations and allied transfers. Expect continued emphasis on mechanized launch systems and operator training packages.
- General Dynamics European Land Systems (GDELS) (Germany): A market leader for amphibious bridging and ferries, GDELS combines high-capacity bridge modules with rapid-deployment doctrine and modular pontoon families. Their role in cross-national programs positions them well for large replacement projects and the authoritative support chains these projects demand.
- Acrow (United States): Known for prefabricated modular steel bridge platforms and floating barge systems that support heavy logistic throughput. Acrow competes on adaptability for line-of-communication tasks and interoperability with existing transport fleets.
- Mabey Bridge (United Kingdom): Offers logistic support bridge systems and pontoon configurations that benefit from a broad international footprint within NATO-aligned users. Their legacy product family and configurable modularity make them a common choice where proven logistics and multinational useability are procurement priorities.
- Regional and alternative suppliers (including several Chinese and continental European manufacturers): These firms provide regionally competitive systems often aligned to national procurement priorities and export markets, sometimes with differentiated pricing or local production offers that matter in bilateral procurement dialogues.
Recent program milestones underscore this competitive dynamic: major European acquisition initiatives and bilateral procurements have moved from study into contract and delivery phases, accelerating fielding timelines and creating supply chain pressure points that will persist through 2026–2029.
Supply chain, risk and procurement levers
Procurement and program managers must weigh a set of interdependent risks and levers when designing 2026 bridge acquisitions:
- Raw material volatility: dependence on aluminum and steel exposes programs to commodity cycles and logistics constraints. Mitigation includes long-lead sourcing agreements, dual-sourcing strategies, and design allowances for alternative alloys where feasible.
- Industrial capacity and execution risk: with several large-scale programs concurrently active, lead times for manufacture and testing can lengthen. Staggered procurement, option agreements, and contractor performance clauses can protect capability timelines.
- Interoperability and standards compliance: ensuring compliance with recognized military load and interface standards reduces integration friction across coalition operations — a non-negotiable for multi-national programs.
- Lifecycle costs vs. capital acquisition: decisions that favor higher-capability modular systems may increase initial capex but reduce lifetime logistics burden and time-to-task. Total cost of ownership modeling is critical to justify these trade-offs to budget authorities.
What PW Consulting’s report delivers for 2026 decision-making
Our full report is designed as an operational tool for acquisition directors, capability planners, and industry partners. Highlights include:
- Proprietary demand modeling and scenario forecasts that translate geopolitical and doctrinal drivers into procurement volumes and timing windows for 2026–2032.
- A detailed supplier matrix covering product capabilities, export footprints, program exposure, and sustainment performance — enabling rapid shortlisting for RFQs and joint procurement initiatives.
- Practical procurement playbooks: contractual templates, sample option structures, and staged acquisition strategies to manage program risk while preserving competition.
- Lifecycle cost models and sensitivity analyses that quantify the trade-offs between modularity, transportability, and throughput capacity.
- Procurement-ready technical annexes: MLC alignment checklists, material selection guidance, and operator-training templates to accelerate fielding and interoperability testing.
Priority recommendations for 2026
For defense leaders and acquisition authorities planning actions in 2026, we recommend:
- Adopt multi-year, option-based procurements to smooth demand peaks and secure production slots with incumbent suppliers while preserving competition for follow-on lots.
- Prioritize modular, transportable architectures that maximize cross-platform compatibility and minimize unique spares footprints across engineer units.
- Integrate training and sustainment packages into award criteria to avoid capability gaps post-delivery — early investment in trainer systems reduces O&M spikes during the initial stand-up period.
- Coordinate allied procurement where feasible: pooled orders and shared logistic baselines reduce per-unit costs and enhance coalition interoperability during joint operations.
Closing — why the full report matters
PW Consulting’s Worldwide Military Floating Bridge Market study provides the actionable intelligence needed to make confident procurement decisions in 2026. It balances quantitative forecasting with hands-on procurement instruments, supplier benchmarking, and risk mitigation playbooks — intentionally withholding raw program-level splits here to encourage stakeholders to consult the full report for contract-ready figures, supplier scorecards, and a downloadable data annex.
Next steps
For program offices, integrators, and sovereign acquisition teams preparing 2026 submissions, our report is a decision-support asset: it reduces uncertainty, shortens procurement lead times, and identifies execution risks before contracts are signed. Visit PW Consulting’s report page to request the full dataset, supplier profiles, and the procurement playbook that will be critical to turning 2026 intentions into operational river-crossing capability.
For detailed analysis of this topic, please visit the official page: Worldwide Military Floating Bridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com