

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Digital Dermatoscope Market to Reach USD 2.16 Billion by 2032, Driven by a 9.2% CAGR

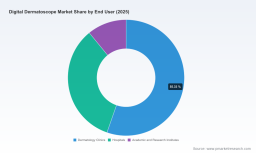
Worldwide Digital Dermatoscope Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s new market brief on the Worldwide Digital Dermatoscope Market provides a focused, decision-ready view for executives planning budgets, product roadmaps, M&A activity, or clinical commercialization strategies in 2026. The global market reached approximately USD 1,164 million in our base year (2025) and is modeled to expand at a compound annual growth rate (CAGR) of 9.2% through the forecast window, reaching just over USD 2.15 billion by 2032. That trajectory creates both clear opportunities and structural challenges for device manufacturers, software providers, hospital procurement groups, and investors seeking differentiated, defensible returns.
Worldwide SaaS Backup Software Market
What this report delivers — practical and operational
- Granular, model-driven market sizing and scenario analysis (historical 2020–2025 trend capture with a 2026–2032 forecast backbone) that supports multi-year capital planning and ROI calculations.
- Actionable go-to-market playbooks for three vantage points: established OEMs, new entrants (hardware-agnostic software/AI players), and strategic buyers in healthcare systems. Each playbook contains channel strategies, pricing archetypes, and clinical validation timelines.
- Procurement and contracting templates tailored to dermatology clinics and hospital networks, highlighting negotiation levers (service SLAs, bundled AI analytics, and upgrade cadence) that materially affect lifecycle cost of ownership.
- Regulatory and reimbursement readiness maps: stepwise checklists to align product development timelines with IEC medical electrical safety compliance and outpatient reimbursement pathways, including practical coding considerations for U.S. payors.
- Supply chain and cost-engineering dossier: component-level risk mapping (optics, illumination, sensors) and mitigation options such as alternate sourcing, vertical integration scenarios, and inventory hedging strategies.
- Competitive assessment and M&A screening matrix identifying likely acquirers, integration synergies, and value capture mechanics—supported by a proprietary scoring model that ranks targets against commercial and clinical milestones.
Why these outputs matter in 2026
As procurement cycles and clinical adoption accelerate, executives need more than point estimates. They need modular playbooks that translate market momentum into executable choices: what product features to prioritize, how to price bundled AI analytics, whether to pursue direct sales or distributor partnerships, and how to stage investments against reimbursement and regulatory timelines. The report’s integrated forecasts and decision frameworks convert the market’s 9.2% projected growth into concrete capital and commercial plans for 2026 and beyond.
Worldwide Drug Discovery Software Market
Market dynamics shaping strategic options
- Clinical and digital adoption drivers — Teledermatology expansion and automated lesion analysis are changing diagnostic workflows. AI-enabled triage and monitoring create stickier service revenue models than hardware sales alone.
- Component and manufacturing pressure — High-grade optics and LED illumination remain a primary cost driver; industry benchmarking indicates optics/illumination can represent a material share of manufacturing cost, which forces suppliers to optimize design for manufacturability and supplier consolidation.
- Regulatory architecture — Compliance to medical electrical safety standards is non-negotiable; aligning product development cycles with IEC standards reduces time-to-market risk and improves procurement confidence among hospital systems.
- Reimbursement and procedural coding — Clear outpatient reimbursement pathways exist for dermoscopy procedures; however, capture depends on correct coding, documentation workflows, and evidence of clinical utility tied to device/software combinations.
- Market concentration and competitive intensity — The market exhibits moderate concentration: a mix of specialized optical OEMs and software-first entrants dominate headline attention, but there is space for niche innovators with novel ergonomics, pricing, or integration approaches.
Competitive landscape — profiles and strategic implications
The report profiles the leading companies shaping the market and analyzes their strategic positioning, product capabilities, and recent moves. Below is a high-level synthesis of those profiles and what they imply for 2026 planning.
Smart Power Plant Market
- Heine Optotechnik (Herrsching, Germany) — Known for the DELTA line with advanced imaging and embedded AI workflows. Recent CE certification updates signal continued investment in imaging performance and European market traction. Strategic implication: incumbents should leverage clinical data from CE-marked devices to expand into bundled service offerings and prioritized EMR integration.
- DermLite (Caliber I.D., Vista, CA) — Market-recognized for clinician-friendly handheld devices and robust app connectivity for teledermatology. Active trade-show presence and app integrations suggest a focus on practitioner workflow optimization. Strategic implication: compete on ease-of-use, developer ecosystems, and direct-to-practice service contracts.
- FotoFinder Systems (Bad Birnbach, Germany) — Strong in whole-body mapping and lesion analytics; recently released an upgraded AI engine, reflecting the competitive premium on algorithm performance. Strategic implication: systems that combine hardware with defensible AI can command better long-term margins and create data-network effects.
- Canfield Scientific (Parsippany, NJ) — Offers tightly integrated imaging solutions with software suites for tracking and reporting. Strategic implication: integration depth with practice management and patient-record workflows remains a barrier to entry for newcomers.
- Dinolite (Los Alamitos, CA) — Focused on portable, USB-connected dermatoscopes with value-oriented sensors. Strategic implication: volume-driven segments (small clinics, mobile units) present a growth corridor for cost-efficient, easy-to-deploy devices.
- AnMo Electronics Corporation (New Taipei City, Taiwan) — Supplies wireless and USB dermoscopes emphasizing LED illumination efficiency. Strategic implication: component and supply-chain advantages in East Asia support competitive OEM pricing and rapid iteration cycles.
Recent product and certification events—such as FotoFinder’s AI upgrade (Oct 2024), Heine’s updated CE certification (June 2024), and DermLite’s product showcase at AAD (March 2024)—underscore the competitive focus on AI validation, regulatory alignment, and clinician-facing workflow improvements. These moves also spotlight two parallel strategic tracks: (1) deepen clinical-utility claims via prospective validation studies to secure premium pricing and reimbursement, and (2) broaden distribution through software and telehealth partnerships to capture recurring revenue.
Strategic playbook highlights for 2026
- For OEMs: prioritize modular architectures that allow hardware upgrades and software monetization. Design contract models that shift some revenue from one-time hardware sales to recurring analytics or support subscriptions.
- For software/AI entrants: focus on interop-first strategies—strong connectors to practice EMRs and imaging ecosystems accelerate adoption and create dataset advantages for algorithm improvement.
- For hospital systems and large group practices: leverage purchasing consortia and outcome-based contracting to mitigate device obsolescence risk; insist on upgrade paths tied to clinical validation milestones.
- For investors and M&A teams: use the report’s screening matrix to identify targets with defensible data assets, validated AI performance, or supply-chain advantages that can be integrated to scale quickly.
Using this research in your 2026 planning cycle
PW Consulting’s model and playbooks are designed to be directly operationalized in 2026 budget cycles. Specific use cases include:
- Capital allocation: translate the market’s growth trajectory into year-by-year revenue scenarios and break-even analyses for new product launches.
- M&A diligence: apply the report’s target scoring to shortlist acquisition candidates that provide complementary tech, channel reach, or cost synergies.
- Clinical commercialization: use the regulatory and reimbursement checklists to sequence clinical studies and coding strategies that unlock outpatient revenue capture.
- Procurement optimization: implement the supplier-risk and component-cost playbook to shield margins from optics/LED price volatility and to negotiate favorable lead times.
Next steps — accessing the full intelligence
This article provides a strategic preview of the report’s principal findings and recommended actions, while preserving the full data tables, regional and application subsegment breakdowns, company market shares, and our complete financial model for subscribers. Those detailed subsegment figures and company-level share analyses are intentionally gated in the full report to enable direct use in financial models and commercial negotiations.
To obtain the complete Worldwide Digital Dermatoscope Market report and the editable forecast model (2026–2032), including downloadable templates for procurement, clinical validation protocols, and the M&A screening workbook, visit the PW Consulting publications page or contact your PW Consulting account lead.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Dermatoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com