

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Biodegradable Disposable Foodservice Market to Reach USD 20.51 Billion by 2032 at 8.02% CAGR; Paper & Paperboard Leads with USD 4.55 Billion in 2025

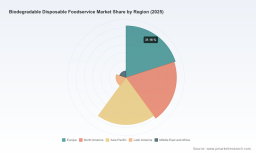
Worldwide Biodegradable Disposable Foodservice Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study on the Worldwide Biodegradable Disposable Foodservice Market synthesizes the evidence behind one clear conclusion: this industry is entering a structurally larger and more complex phase where commercial strategy, regulatory foresight, and operational execution will determine winners and losers. Our analysis shows the global market expanding from roughly USD 11.95 billion in 2025 to an estimated USD 20.51 billion by 2032, representing a compound annual growth rate (CAGR) of 8.02% over the forecast period. For executives setting priorities in 2026, the choices made this year about supply chain, product architecture, and policy positioning will define competitive position through the end of the decade.
Worldwide Screening Equipment Market
Key high‑level takeaways
- Robust, sustained growth: The market’s mid‑single digit to low‑double digit trajectory is driven by a mix of regulatory mandates, corporate sustainability programs, and consumer demand for lower‑impact disposables.
- Fragmented supply base: Market concentration remains low (CR3 ~18.5%; CR5 ~26.8%), reflecting a mix of global players, regional specialists, and numerous local manufacturers — a profile that favors targeted consolidation and scale plays.
- Material and infrastructure interplay: Material choice (paper, PLA, bagasse, starch blends, bamboo and others) is increasingly decided not by product marketing alone but by feedstock security, life‑cycle claims and local composting/collection infrastructure.
- Regulatory inflection points accelerate winners: Recent and pending regulations across multiple jurisdictions create both barriers and demand pull — from the EU packaging overhaul to national single‑use bans and evolving organic compost standards.
- Margin pressure and innovation premium: As volumes grow, price competition will increase; differentiation via coatings, barrier technologies, and compostability certification will be critical to protect premium positioning.
Why 2026 is an inflection year
Three forces converge in 2026 to reshape strategy: new regulation, shifting standards for what can enter compost streams, and fast‑evolving commercial partnerships. The EU’s Packaging and Packaging Waste Regulation (PPWR) has reoriented design‑for‑recycling criteria, introducing harmonized requirements that affect product architecture and label claims. The announcement of broad single‑use plastics bans in jurisdictions such as the UAE, and state‑level Extended Producer Responsibility (EPR) laws in the U.S., are raising the effective cost of inaction for manufacturers and brand owners.
Focus App Market
Additionally, changes to composting eligibility — notably decisions affecting synthetic polymers and organic compost standards — are creating uncertainty around which “compostable” claims will be accepted by waste managers and regulators. Operators now face a twofold risk: product obsolescence if claims are decertified, and stranded inventory if local composting capacity cannot absorb volumes. That is why the report emphasizes regulatory and standards scenario planning as a core strategic lever for 2026.
Real Estate Agent and Broker Market
Competitive landscape — what the leaders and challengers are doing
The industry features a mix of multinational manufacturers with deep distribution networks, specialist challengers focused on plant‑based portfolios, and regionally strong producers leveraging low‑cost feedstocks. Leading global firms have prioritized product innovation, certification and white‑label partnerships; regional players compete on price, feedstock access and rapid local fulfillment.
- Huhtamaki — global R&D and channel reach: As a major global provider, the company invests in product innovations that reduce polymer content and expand compostability in both home and industrial settings. Recent launches underscore the strategic focus on bio‑coatings and performance parity with conventional disposables.
- Vegware — plant‑based differentiation: Focused on PLA and bagasse portfolios, Vegware has strengthened retailer and foodservice partnerships, leveraging sustainability credentials and supply chain transparency.
- Eco‑Products (Novolex) and World Centric — certification and institutional channels: These players emphasize certified compostability for institutional clients and municipal compost programs, aiming to be the default supplier for foodservice contracts tied to sustainability KPIs.
- Asia‑based producers (e.g., Bioleader, Luzhou Pack, Biopac) and regional specialists (e.g., GreenGood) — scale and feedstock arbitrage: Manufacturers in Asia and Southeast Asia are leveraging abundant agricultural residues and lower production costs to compete on price while increasingly meeting international compostability standards.
- Smaller pure‑play manufacturers and distributors — tactical plays: Companies such as AMS Compostable and Green Wave International focus on bulk institutional sales and niche product sets, delivering cost‑effective options for high‑volume buyers.
The market’s low concentration ratio implies substantial runway for consolidation and contract wins by scale‑oriented players. Recent strategic moves — for example, alliances between manufacturers and large retail groups, and targeted product launches — demonstrate a two‑track strategy: secure large channel partnerships while continuing product innovation to meet tightening regulatory standards.
Report highlights — practical, transaction‑ready intelligence
PW Consulting’s report is built for decision makers who need actionable answers today, not just descriptive market color. Key deliverables include:
- Seven‑year base model anchored to 2025 data and scenario extensions through 2032, with sensitivity analysis for regulatory and feedstock shocks.
- Strategic playbooks for manufacturers, foodservice operators, retailers and investors: SKU rationalization, EBITDA improvement tactics, and go‑to‑market roadmaps for 2026–2028.
- Competitive scorecards and supplier heat maps that evaluate capabilities across certification, scale, product breadth, and ESG claims.
- Regulatory & standards tracker with timelines and impact assessments (PPWR, national bans, compost standards and EPR regimes), including recommended policy engagement strategies.
- Cost‑to‑serve and feedstock procurement models that quantify margin dynamics by material family and end‑use scenario.
- M&A target shortlists and diligence checklists tailored for private equity and strategic acquirers seeking consolidation opportunities.
- Operational playbooks for integrating composting partnerships with municipal waste managers and commercial composting networks.
To protect commercial value and encourage direct engagement, the report intentionally presents summary insights in public releases while reserving granular segmentation tables, product‑level forecasts and confidential supplier scorecards for licensed report purchasers.
Strategic imperatives for 2026
We recommend that market participants prioritize the following actions this year:
- Secure feedstock and logistics resilience: Negotiate multi‑year agreements for agricultural residues and vetted biopolymers; model logistics to avoid seasonal shortages that erode margins.
- Invest in claim defensibility and certification: Align product development with recognized industrial and home compostability standards and document end‑of‑life pathways for customers and regulators.
- Partner with waste management and municipal programs: Guarantee end‑of‑life solutions by co‑investing in collection pilots and scaleable commercial composting capacity, particularly in high‑volume metropolitan areas.
- Prioritize product design for recycling and circularity: Where regulation favors recyclable design, plan dual‑track product architectures and labeling strategies to avoid sudden obsolescence.
- Pursue targeted M&A and alliances: Use the current fragmentation to acquire technical capabilities (coatings, barrier tech) or expand channel access via strategic retail and foodservice partnerships.
- Prepare for EPR compliance: Build cost models that allocate EPR fees across SKUs and incorporate these into pricing and contract negotiations with institutional buyers.
Use cases — how leading organizations are already applying these insights
Several recent industry moves reflect the types of strategies we recommend. Strategic alliances with large retailers to co‑develop plastic‑free SKUs, targeted product launches that reduce polymer content and increase compostability, and market expansions into major foodservice geographies illustrate practical applications of scale, channel alignment and product differentiation. Each demonstrates the importance of aligning R&D, procurement and policy functions inside organizations to extract value from market growth.
Concluding perspective and how to access the full intelligence
The biodegradable disposable foodservice market combines favorable macro demand with granular operational and regulatory complexity. The next 18 months are decisive: companies that secure feedstock, prove end‑of‑life credibility, and align with evolving regulations will capture disproportionate market share as the industry scales. PW Consulting’s in‑depth report provides the playbooks, models and confidential benchmarks needed to design those winning strategies.
For the full dataset, confidential segmentation, supplier scorecards and executable 2026 playbooks, visit PW Consulting’s report page to request the licensed report or contact our advisory team for a bespoke briefing. This public summary intentionally omits the detailed regional, product and material splits contained in the premium report to protect commercial value and to ensure buyers receive the complete, validated dataset necessary for high‑stakes decision making.
For detailed analysis of this topic, please visit the official page: Worldwide Biodegradable Disposable Foodservice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com