

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Solar Laser Drilling Market to Reach USD 1,696.53 Million by 2032, Growing at a 13.66% CAGR

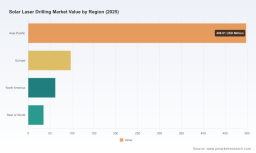
Worldwide Solar Laser Drilling Market — 2026 Strategic Brief
PW Consulting’s newest market intelligence release on the Worldwide Solar Laser Drilling Market delivers a focused, decision-ready briefing for executives preparing capital allocation, sourcing, and R&D roadmaps in 2026. The market is moving from niche enabler to mainstream productivity lever in photovoltaic (PV) manufacturing. This briefing synthesizes the report’s headline market trajectory, competitive dynamics, near-term risks and opportunities, and the concrete ways procurement, operations and corporate strategy teams should act this year — while preserving the granular segmentation tables and proprietary vendor scores available in the full report.
EV NMC Battery Market
Market trajectory: a data-driven snapshot
Our modelling, anchored on a 2025 base year, shows the solar laser drilling market expanding rapidly as PV manufacturers adopt higher-throughput laser processes across cell contact opening, glass drilling for double-glass modules, and cell dicing formats that increase module efficiency and yield. In monetary terms (USD, Million), the market more than doubled from the early-2020 base and is forecast to continue at an accelerated pace: the 2025 market stands at approximately USD 692.5 Million (base year), and our conservative scenario projects the market growing at a compound annual growth rate (CAGR) of 13.66% through the forecast period. By the end of our 2026–2032 forecast window, the market exceeds the USD 1.6 Billion threshold, reflecting sustained adoption across technologies and manufacturing geographies.
Worldwide Anhydrous Borax Market
These topline figures are intended to communicate the scale and urgency of the opportunity: laser drilling is no longer a marginal production step — it is becoming a strategic lever for module producers seeking incremental efficiency and cost-per-watt gains. The full report contains the detailed year-by-year sizing, scenario splits, and the sensitivity analysis that underpins our headline CAGR for teams that require transaction-level fidelity.
Oil Insulated Ring Main Units Market
Why 2026 is a true decision point
-
Investment pacing vs. technology transition: Several industry signals point to cautious capital deployment in early 2025–2026. Public disclosures from equipment vendors highlighted pockets of postponed orders linked to tariff uncertainty and an ongoing technology shift toward perovskite-coated cells. These dynamics are compressing windows to secure favorable supply terms and incentivizing suppliers to reprice or bundle services.
-
New process breakthroughs accelerating total cost reduction: Parallel advances in drilling speed and chipping control for thin back glass — demonstrated by recent vendor announcements — materially alter throughput and yield math on double-glass module lines. For manufacturers, the delta between pilot results and full-line deployment can translate into multi-million-dollar improvements in annualized module output; our operational models quantify payback timelines under multiple throughput and yield scenarios (available in the report).
-
Established process standards forming around high-efficiency cell formats: Laser contact opening (LCO) and Thermal Laser Separation (TLS) for cell dicing are now operational best practices in many high-volume lines. As module makers standardize on these laser-based steps, the pace of retrofit and greenfield laser adoption accelerates — which influences supplier bargaining power and aftermarket service economics.
Competitive landscape — who matters and why
The market’s competitive structure is moderately concentrated: the three largest suppliers capture a meaningful portion of the addressable market, and the top five increase that hold further. This concentration favors a small set of vertically integrated laser OEMs and specialized systems integrators that combine laser sources, beam delivery, and process automation into turnkey production cells.
-
3D-Micromac AG (Chemnitz, Germany) : Specializes in high-throughput micromachining systems tailored to PV applications, particularly LCO on advanced PERC cells and TLS dicing for half/shingle formats. Its strength is process-specific engineering and factory-proven modules for efficiency-driven producers.
-
Han’s Laser (Shenzhen, China) : Focused offerings for PV glass drilling make the company a natural partner for double-glass module lines. Its product positioning emphasizes cycle-time and low-cost-per-hole metrics that matter for balance-of-line economics.
-
TRUMPF (Ditzingen, Germany) : A long-standing provider of industrial laser systems with breadth across manufacturing verticals. TRUMPF’s advantage lies in product robustness and global after-sales coverage — critical for multinational module makers.
-
Coherent, IPG Photonics, Novanta, SCANLAB, Laserax, Rache, Laserod : These vendors play complementary roles — supplying laser sources (including fiber and ultrashort-pulse systems), beam delivery and scanning modules, laser cleaning and scribing subsystems, and specialized process know-how. Their varied portfolios mean customers will often use multi-vendor configurations and integration partners to optimize performance and risk.
Given the mixed ecosystem of component suppliers, subsystem integrators and full-line OEMs, strategic partnership choices will determine IP access, spare-parts lead times, and retrofit costs. Our vendor benchmarking in the report ranks vendors on 12 criteria spanning uptime, service reach, integration support, and roadmap alignment — a practical tool for sourcing teams preparing technical RFPs (redacted here).
Operational and commercial implications for 2026 buyers
-
Prioritize modular proofs-of-concept before full-line conversions. Our factory simulations show that pilot-focused investments reduce integration risk and accelerate time-to-yield by 20–40% compared with immediate full-line rollouts. The report includes templated pilot KPIs and acceptance criteria aligned to equipment CAPEX profiles.
-
Negotiate service-level bundles tied to throughput guarantees. With supplier concentration and recent demand volatility, structuring contracts to include joint process development and fixed-outcome incentives protects returns and limits performance drift over warranty periods.
-
Build a multi-horizon technology plan. Laser investments have different payback windows depending on whether you optimize for PERC/TOPCon today or position for perovskite-enabled cells tomorrow. We provide a clear decision tree and threshold metrics that quantify when to accelerate adoption vs. delay for later-generation cell compatibility.
-
Monitor regulatory and trade-policy scenarios. Tariff and subsidy uncertainty materially shifted order timing for many vendors; scenario outcomes in the report translate policy permutations into equipment order volatility and working-capital stress tests for suppliers and buyers.
What the PW Consulting report contains — practical, actionable modules
-
Methodology and assumptions: transparent forecasting framework, data sourcing, and sensitivity bounds.
-
Historical market analysis (2020–2025) and a seven-year forecast (2026–2032) with scenario sensitivity and Monte Carlo testing around throughput, yield and price curves.
-
Vendor profiles and a comparative scoring matrix covering hardware, software, service and integration capabilities.
-
Technology deep-dives: LCO, TLS dicing, ultrashort-pulse options, glass drilling, and laser cleaning — including process windows, expected defect modes, and operational best practices.
-
Factory-level financial modeling: CAPEX, OPEX, payback timelines, and a customizable TCO calculator you can use with your own throughput and yield inputs.
-
Commercial playbooks: RFP templates, contract structures, retrofit implementation checklists, and supplier risk-mitigation strategies.
-
M&A and partnership targets: a curated shortlist of candidates for bolt-on acquisitions, technology licensing, and JV partners, with deal rationale and integration risk mapping.
Near-term market signals to watch (and their strategic responses)
-
Perovskite adoption curve: Track OEM pilot announcements and certification progress. For most module makers, the optimal approach is a staged R&D alliance with laser suppliers to ensure process portability across substrate changes.
-
Glass-drilling throughput breakthroughs: Where vendors deliver step-function improvements in cycle time and chipping control, prioritize pilots on double-glass lines to capture fast payback windows.
-
Order volatility tied to trade policy: Secure flexible delivery terms and consider staggered capacity purchases to avoid over-exposure to policy-driven demand swings.
How PW Consulting’s report supports 2026 decision-making
For corporate strategists, our report translates market sizing and vendor capability into board-ready recommendations: the precise timing for greenfield versus retrofit investment, supplier partnerships to de-risk rollouts, and prioritized R&D themes to protect product roadmaps. For operations and procurement leaders, the report supplies the vendor scorecards, pilot acceptance criteria and TCO models to move from proof-of-concept to repeatable, low-risk production. For investors and M&A teams, the report identifies consolidation vectors and shows which vendor capabilities command premium valuations.
Next steps
This brief highlights the strategic contours and operational playbooks necessary for effective action in 2026; the full report provides the proprietary segmentation matrices, vendor scores, and downloadable modeling templates necessary to execute. PW Consulting invites C-suite teams, factory operations leaders, and strategic investors to review the complete dataset and custom advisory options available on our report landing page.
Contact PW Consulting to arrange an executive briefing, receive the full Worldwide Solar Laser Drilling Market report, or commission a tailored scenario analysis aligned to your factory and technology roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Solar Laser Drilling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com