

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
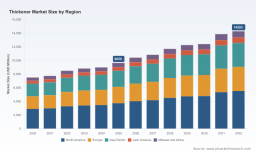
PW Consulting: Thickener Market to reach USD 14,283M by 2032 at 5.8% CAGR

Thickener Market — 2026 Strategic Briefing
As PW Consulting’s senior industry analyst, I present a concise, strategy-focused introduction to our comprehensive Thickener Market study (base year 2025). This briefing is designed to orient C-suite and commercial leaders facing critical 2026 choices — capital allocation, portfolio reshaping, sourcing strategy, and M&A prioritisation. We deliberately present high-level, data-driven insight here to demonstrate the analytical rigor behind the full study while omitting the proprietary segment-level tables and granular regional/application splits that are available only in the full report.
Thickener Market
Macro snapshot you can act on
- Market trajectory: The global thickener market expanded steadily through 2020–2025, reaching an estimated USD 9.65 billion in 2025. Our forecast model projects continued expansion through 2032, driven by both food & beverage and industrial end‑markets, resulting in a market size of roughly USD 14.28 billion by 2032 under a central scenario.
- Growth rate: The forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of approximately 5.8%, reflecting the combined effect of product innovation, sustainability-driven reformulation, and selective industrial demand resurgence.
- Market structure: The sector is moderately concentrated: the three-largest firms control the majority of organised volume and value-added solutions, and the top five together exert significant pricing and distribution influence. This concentration underpins both competitive defensive moves and attractive bolt-on M&A opportunities for mid-sized players.
What’s moving the market in 2026 — dynamics and headwinds
- Regulatory and sustainability pivot: Policymaker momentum is accelerating substitution away from certain synthetic polymers toward biodegradable and bio‑based thickeners. European regulatory shifts and procurement standards are increasing adoption rates of bio-based solutions — a trend that now shapes R&D priorities and product roadmaps.
- Raw material volatility: Cost pressure in key natural hydrocolloid feedstocks has intensified. For example, xanthan feeders experienced a meaningful Q1 2026 uplift in FOB pricing in major supply hubs, compressing formulators’ margins and raising urgency for procurement hedges, alternative sourcing strategies, and formulation optimisation.
- Industrial and water-management innovation: Equipment suppliers and miners continue to invest in throughput and efficiency upgrades for thickening processes. Recent capital projects and new product introductions are shortening deployment cycles for select industrial thickening applications.
- Operational compliance risks: Several emerging markets have reported rising effluent and wastewater treatment loads related to chemical processing, increasing compliance costs and creating local operating constraints for some manufacturers.
Competitive landscape — positioning and strategic posture
The market is served by a mix of global agribusiness ingredient players, speciality hydrocolloid firms, and chemical giants. Each plays a distinct role along the value chain and pursues specific go-to-market strategies:
Thickener Market
- Cargill — Global agrifood integrator with extensive hydrocolloid and starch-based offerings, increasingly positioning around clean-label and plant-based claims to capture food & beverage reformulation opportunities.
- Ingredion — Specialist in starch and fermentation-derived thickeners with broad application expertise in food, beverage and personal care, leveraging application labs to drive specification wins.
- Archer Daniels Midland (ADM) — Large-scale starch and corn-derived supplier focused on industrial scale and vertical raw-material integration, enabling competitive cost structures for commodity-thickener supply.
- Kerry Group & Tate & Lyle — Mid-to-large speciality ingredient firms combining hydrocolloids, pectins and application know-how to service premium food and beverage customers seeking clean-label replacements.
- CP Kelco — A category specialist in xanthan, gellan and carrageenan, increasingly emphasising sustainability upgrades and decarbonisation in its plant investments.
- BASF, Dow, DuPont, Ashland, AkzoNobel, Elementis — Chemical and speciality chemical players focused on synthetic, acrylic and cellulose ether thickeners for paints, coatings, construction, personal care and industrial applications. Their advantage lies in polymer technology, formulation performance and global coatings distribution channels.
Recent public developments illustrate these dynamics: facility decarbonisation projects, small-scale packaged thickening equipment launches for decentralised wastewater treatment, and commissioning of plant-level throughput upgrades in mining — all reinforcing a differentiated set of threats and opportunities across segments.
Thickener Market
What the PW Consulting report delivers (actionable, practitioner-focused)
- Proprietary market-sizing model: historical (2020–2025) reconciliation and a configurable forecast engine (2026–2032) that lets users run custom scenarios for price, raw material shock, and regulatory adoption paths.
- Segment and application architecture: a structured taxonomy linking type, formulation, and end-use (note: the public brief omits granular split tables — those are provided in the full report to paid subscribers).
- Pricing and margin analytics: pass-through sensitivity models that quantify margin impact from feedstock moves and differential adoption of bio‑based alternatives.
- Supply-chain mapping: supplier concentration matrices, critical-node risk heatmaps, and sourcing optimisation playbooks for both commodity and speciality feedstocks.
- Regulatory & sustainability impact assessment: scenario simulations on policy adoption (EU, US, India) and their impact on product portfolios and compliance costs.
- Competitive benchmarking: capability heatmaps across production footprint, innovation intensity, go-to-market coverage, and sustainability credentials, including M&A screening criteria for strategic acquirers.
- Practical go-to-market tools: commercial pricing playbooks, sample RFP language for procurement, and an 18-month action plan template for product relaunches centered on clean-label claims.
- Primary research: synthesis of over 50 stakeholder interviews (manufacturers, formulators, major end users, and regulators), corroborating quantitative findings with real-world commercial intelligence.
Strategic implications — recommended actions for 2026 decision cycles
- Prioritise bio-based and clean-label NPD: Fast-track reformulations where regulatory risk is highest and where premiumisation supports sustainable margin capture. Pilot launches should be paired with claims substantiation and customer co‑development agreements.
- Hedge raw-material exposure: Implement a layered procurement strategy combining long-term contracts, regional multi-sourcing, and limited vertical integration where economics justify. Pay special attention to high-volatility hydrocolloids.
- Segment-driven capacity strategy: Delay broad-spectrum greenfield investment; instead, pursue modular capacity that can be repurposed across types as demand shifts — particularly relevant for players exposed to both food and industrial applications.
- Targeted M&A and partnerships: For mid-sized players, focus on bolt-on acquisitions that add unique hydrocolloid chemistries or regional market access. For large firms, aim to secure specialty portfolios that accelerate clean-label leadership.
- Operational sustainability as differentiation: Invest selectively in decarbonisation and effluent management projects that reduce regulatory risk and shorten customer approval cycles in sustainability-focused procurement processes.
- Customer-centric commercial models: Introduce value-based pricing and technical support bundles for formulators to justify premium for higher-specification, sustainable thickeners.
- Digital enablement: Adopt advanced demand-forecasting and RI/OT tracking to reduce batch variability and improve raw-material yield — quick wins that protect margins under price volatility.
How to apply these insights — by archetype
- Ingredient manufacturers: Use the report’s supplier risk and pricing modules to set a 12–24 month procurement and CapEx plan; prioritise specialty lines with higher margin resilience to feedstock shocks.
- Formulators and brands: Leverage the end‑use performance matrix to identify candidate thickening systems that meet both sensory and sustainability thresholds; deploy co-funded pilot programmes with suppliers to accelerate time-to-market.
- Industrial end users (mining, wastewater, coatings): Adopt the equipment and throughput case studies to benchmark retrofit vs. replacement investments and quantify the total cost of ownership for thickening solutions.
In short, the thickener market in 2026 presents a mix of rising demand and increasing technical/regulatory complexity. The growth runway is clear at a macro level; the near-term competitive prize belongs to organisations that can combine formulation agility with disciplined procurement and credible sustainability narratives.
Next steps — where to find the full intelligence
This briefing intentionally omits the granular region-by-region and application-by-type splits and some proprietary pricing matrices to preserve the commercial value of the full study. PW Consulting’s complete Thickener Market report contains those detailed tables, the interactive forecast workbook, competitor scorecards, and a bespoke scenario workshop kit to support your 2026 planning cycle. Contact PW Consulting or visit the report landing page to access the full dataset and schedule a strategy workshop to translate the analysis into a concrete 18-month action plan.
For detailed analysis of this topic, please visit the official page: Thickener Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com