

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polyimide (Kapton) Tape Market to Reach USD 2,234M by 2032 at 9.2% CAGR

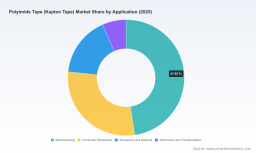
Polyimide Tape (Kapton Tape) Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of our full Polyimide Tape (Kapton Tape) Market study — designed to equip executive teams with the strategic vantage required for confident 2026 planning. This preview synthesizes market momentum, competitive moves, regulatory inflection points, and action-oriented frameworks from our full report. It intentionally highlights analytical depth while omitting the granular segment-level tables and privileged forecasts locked in the full study — a deliberate “trailer” meant to show capability and drive you to the complete dataset and playbooks.
Polyimide Tape (Kapton Tape) Market
Why this market matters to 2026 strategy teams
-
Market trajectory: The polyimide tape market is on a sustained growth path. Measured in USD Million, the market expanded from a multi-hundred million base in 2020 to an estimated USD 1,210.0 Million in 2025, and our modeling projects robust expansion through 2032, reaching over USD 2,200 Million in the baseline forecast horizon. This equates to a compound annual growth rate (CAGR) of approximately 9.2% across the forecast period.
Polyimide Tape (Kapton Tape) Market -
Why growth is durable: Demand drivers are both secular and cyclical — from the continued miniaturization and thermal management needs in semiconductors and advanced electronics, to scaling applications in EV power electronics, aerospace & defense heat shielding, and precision manufacturing processes that require high-temperature masking and electrical insulation.
Polyimide Tape (Kapton Tape) Market -
Decision relevance for 2026: With the market in an acceleration phase, 2026 is the pivotal year for capital allocation and supply-chain repositioning. Actions taken this year — capacity commitments, JV terms, sourcing contracts, or product-line pivots — will define market share trajectories through the late-2020s.
What our report delivers (practical, executable content)
-
Proven forecasting engine: A transparent, scenario-based model calibrated to historical performance (2020–2025) and forward-tested against alternative macro and industry-specific scenarios. The model is deliverable in an interactive workbook so planners can stress-test assumptions (e.g., capex delays, raw-material shocks, trade-control scenarios).
-
Supply-chain stress tests: Step-by-step simulations that quantify the operational and P&L impact of supply disruptions, including lead-time elongation, single-source dependencies, and raw-material price spikes. Each test links to mitigation playbooks (dual sourcing, hedging strategies, consignment agreements).
-
Commercial playbooks: Go-to-market modules covering B2B contracting (volume discounts, strategic alliances with OEMs), channel optimization, and pricing levers for different product variants. These playbooks are built for commerce teams ready to deploy within 90–180 days.
-
Regulatory risk matrix: A prioritized map of current and plausible export-control and materials regulations, with hedge strategies (compliance architectures, jurisdictional sourcing options, licensing roadmaps) for minimizing production and market access interruptions.
-
M&A and capex scoreboard: Rigorous target evaluation templates for acquisition or greenfield moves, including synergy calculators, integration scorecards, and break-even analyses tied to volume and price scenarios.
-
Supplier and technology scorecards: Comparative matrices that rate raw-material suppliers, tape producers, adhesive technology providers, and end-use integrators across metrics of capacity, geographic risk, technological fit, and ESG compliance.
Competitive landscape — what incumbents and new entrants are signaling
The market exhibits a moderate concentration profile: the top three providers account for a meaningful share of industry sales, and the top five further increase concentration — a dynamic that favors incumbents with scale, proprietary film formulations, and deep established relationships in semiconductor, aerospace, and industrial OEM channels. That concentration creates both barriers and opportunities: scale-sensitive players can exert pricing discipline and invest in capacity or specialty R&D, while nimble suppliers can carve higher-margin niches through customization and rapid-response service models.
-
DuPont — a strategic bellwether. With branded Kapton film and tape, DuPont has demonstrated a willingness to invest in capacity to secure long-term demand. A notable expansion completed in 2024 underscores how incumbent producers are pre-empting future shortages and locking in feedstock throughput.
-
3M Company — product-led differentiation. 3M’s ongoing product innovation for extreme-temperature masking in semiconductor fabrication illustrates how technology variants can open premium segments within existing markets.
-
Nitto Denko — regional capacity shifts. Recent expansions targeted at EV power electronics and EMI shielding signal demand-side shifts: producers are reorienting capacity to high-growth applications tied to electrification and miniaturized power systems.
-
Specialized and distributor players (e.g., Scapa Group, Saint-Gobain, Fralock, CS Hyde, KaptonTape.com, TapeCase) — collectively these players serve high-touch, application-specific needs — custom slitting, adhesive tuning, ESD-safe solutions, and small-batch specialty runs. These providers are attractive for OEMs needing rapid prototyping and specialized certifications.
Regulatory and raw-material dynamics that will shape 2026 choices
-
Raw-material cost structure: Production depends on aromatic polyimide monomers and specialty resins that are capital- and technology-intensive to produce. Elevated upstream costs meaningfully affect unit economics and industry margins, necessitating tighter procurement strategies and cost pass-through contract clauses for buyers and producers alike.
-
Export controls and trade policy: Multiple jurisdictions updated controls on advanced materials and processing technologies in 2024–2025, with additional measures impacting polyimide-related supply chains announced or enacted in 2025. These measures introduce new compliance obligations and potential sourcing constraints. Strategic responses include diversified sourcing footprints, licensing contingency plans, and proactive dialogues with trade authorities.
-
Geopolitical concentration risk: Manufacturer footprints and raw-material supply are geographically clustered in certain regions, creating systemic exposure. A pragmatic 2026 strategy must quantify that exposure and, where economically viable, implement hedges — whether via inventory buffers, local-sourcing agreements, or co-investments in regional production.
Strategic options for 2026 — prioritized and actionable
-
Option A — Secure supply, protect margins: For volume-dependent manufacturers, prioritize multi-year off-take contracts with staged price indexes tied to validated raw-material baskets. Combine contracts with rights of first refusal on capacity expansions to prevent spot-market squeezes.
-
Option B — Differentiate through specialization: Invest in adhesive chemistry and slitting capabilities that serve high-margin niches (extreme-temperature, EMI management, aerospace-grade certification). For many mid-sized players, this route yields higher returns than scale alone.
-
Option C — Strategic partnerships and co-investments: Where regulatory and capex constraints deter greenfield projects, consider joint ventures with incumbents or end-users. Co-location with semiconductor fabs or EV powertrain assembly lines shortens logistics and improves responsiveness.
-
Option D — M&A for capability and market access: Target tuck-ins that add adhesive technology, specialty slitting, or regional footholds. Use the M&A scoreboard in our full report to assess payback timing under differing market growth sensitivities.
How to use this preview in your 2026 planning
Leaders should treat this preview as a decision trigger. Use it to align stakeholders on three immediate steps for 2026:
-
Run a 90-day supply-chain diagnostic using scenario inputs (included in the full deliverable) to quantify single-source exposures and identify the top three suppliers where contract renegotiation or capacity options are urgent.
-
Commission a product-differentiation audit to evaluate whether premium adhesive formulations or specialized tape geometries could unlock new OEM contracts with better gross margins.
-
Engage in regulatory horizon scanning and secure legal counsel to model licensing or export permutations relevant to your sourcing jurisdictions and end-markets.
Conclusion — the strategic pay-off
The Polyimide Tape market is moving from steady growth to strategic inflection. With market size expanding from roughly USD 790 Million in 2020 to an estimated USD 1,210 Million in 2025 and a projected climb toward and beyond USD 2,200 Million by 2032 at a ~9.2% CAGR, the timing for decisive action is now. Whether your priority is supply security, margin expansion through technology, or acquisitive growth, 2026 decisions will disproportionately determine outcomes through the rest of the forecast decade.
PW Consulting’s full report provides the granular segmentation, supplier-level financials, and executable playbooks required to translate these strategic options into measurable results. For executives who must convert insight into strategic advantage this year, our complete study and the accompanying analytical toolkit are the next logical step.
For detailed analysis of this topic, please visit the official page: Polyimide Tape (Kapton Tape) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com