

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium‑Ion Electrolyte Market Set for 12.94% CAGR (2026–2032)

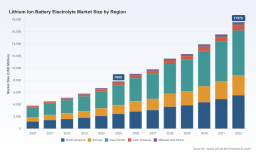
Lithium‑Ion Battery Electrolyte Market — Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused introduction to our latest market intelligence on the Lithium‑Ion Battery Electrolyte market. This briefing translates the report’s core strategic value into concrete decision levers for 2026 while preserving the gated, high‑value datasets that underpin our forecasts. The analysis is anchored to a 2025 base year and a 2026–2032 forecast window, with the market tracked from 2020 through 2025. Our bottom‑up projection shows the market growing at a compound annual growth rate (CAGR) of 12.94% across the forecast horizon — expanding from an estimated ~USD 7.8 billion in 2025 toward a multi‑billion dollar opportunity by 2032. This trajectory creates both structural winners and tactical risks for manufacturers, OEMs, raw‑material suppliers, investors, and policy stakeholders.
Lithium Ion Battery Electrolyte Market
Why this research matters for 2026 decisions
-
Timing of capital deployment: 2026 is a pivotal inflection point for many firms that committed to capacity expansions in the 2022–2025 cycle. Our analysis helps executives determine whether to accelerate, delay, or reconfigure capital allocation based on demand elasticity and supply‑side constraints.
Lithium Ion Battery Electrolyte Market -
Supply chain resilience and IRA‑era localization: Policy drivers and buyer commitments mean near‑term commercial qualification cycles and local content considerations have outsized value. The report maps where localized supply matters most to cell makers and battery integrators.
Lithium Ion Battery Electrolyte Market -
Raw‑material volatility and margin protection: Electrolyte makers face concentrated upstream supply risk (notably LiPF6) and episodic price spikes. We model price pass‑through, hedging approaches, and margin sensitivity under alternative commodity paths to inform procurement and contracting strategies.
-
M&A and partnership windows: Consolidation is emerging as a strategic route to secure capacity, access proprietary formulations, or accelerate geographic footprint. Our competitive triangulation identifies the classes of targets that will deliver the fastest strategic payback.
What the full report provides (operationally focused)
-
Market sizing and multi‑scenario forecasts (2026–2032) driven by cell chemistry adoption curves, EV and stationary storage demand scenarios, and OEM battery roadmaps.
-
Segment mapping (by region, electrolyte type, and end‑use application) with demand drivers and bottom‑up capacity reconciliation. Note: detailed segment tables and downloadable models are retained in the full report to preserve their commercial value.
-
Supply chain and cost‑curve analysis that connects raw‑material pricing, purification yields, and tolling economics to unit cost for electrolytes and salts.
-
Competitive benchmarking and capability matrices that score incumbent producers on purity technology, regulatory compliance, localized manufacturing, and customer port‑folios.
-
Regulatory, environmental, and safety risk assessments — including permitting timelines, hazardous‑materials handling constraints, and compliance pathways across major markets.
-
Go‑to‑market playbooks for producers: contract templates, qualification timelines for OEMs, customer segmentation, and premium formulation commercialization steps.
-
Investment decision tools: sensitivity analyses, NPV templates, and break‑even models for greenfield vs retrofit plants and for pursuing upstream integration into salts and additive supply.
-
Prioritized M&A target shortlists and diligence checklists for strategic buyers and private equity, based on technology, capacity, and route‑to‑market fit.
Methodology and confidence
-
Base: 2025 as the fiscal base year with historical trend analysis from 2020–2025.
-
Projections: Multi‑model forecasting that combines bottom‑up plant builds, OEM qualification lags, and demand curves for EV, consumer electronics, and energy storage segments. Scenario buckets include conservative, consensus, and aggressive technology substitution cases.
-
Primary data: Plant‑level capacity tracking, interviews with producers and OEM procurement leads, and proprietary pricing feeds for key precursors and salts.
-
Validation: Cross‑checking against public disclosures, regulatory filings, and transaction activity to ensure triangulation of capacity and commercial commitments.
Market structure and competitive dynamics — an executive snapshot
The market displays moderate top‑end concentration: the three largest players command a majority position, and the five largest account for a substantive, but not overwhelming, share of global supply. This structure produces a market that is neither a fragmented commodity race nor a closed oligopoly — instead it favors technically capable firms that can combine scale with purity, localized manufacturing, and strong customer qualifications.
-
Mitsubishi Chemical Corporation (Tokyo) — a legacy player with high‑purity liquid electrolytes and recent capacity initiatives aimed at serving North American cell makers that require localized supply. Their technology and global footprint make them a reference competitor on quality and compliance.
-
Green Energy Origin (GEO) (Weinheim) — rapidly expanding through asset acquisitions and integration of upstream inputs. Their strategy blends European and North American manufacturing to capture tier‑1 EV and stationary storage contracts.
-
Guangzhou Tinci Materials (Guangzhou) — a vertically integrated Chinese incumbent offering a broad portfolio of salts, additives, and electrolytes, with accelerated push into North America to secure OEM agreements.
-
Shenzhen Capchem, Shanshan (Dongguan), Soulbrain (Seoul), Guotai‑Huarong (Zhangjiagang), Panax Etec, Shandong Shida Shenghua, UBE, and BASF — each brings differentiated capabilities in purification, additive know‑how, or scale. The competitive field favors firms that can marry formulation IP with qualifying supply chains for automotive grade cells.
Recent strategic moves underscore the market dynamics executives must internalize: a notable asset transfer completed by Green Energy Origin in mid‑2026 that accelerates their North American footprint, and major greenfield and long‑term supply commitments by vertically integrated Chinese producers to service global OEM programs. These transactions are emblematic of two converging forces — capacity consolidation and geographic rebalancing — that will shape supplier selection and bargaining power in 2026.
Raw‑material volatility and regulatory signals — immediate tactical considerations
-
Price and supply risk: Key precursor pricing experienced sharp movements in the 2025–H1 2026 window. Such volatility compresses predictability for margins and favors producers with recycling, in‑house synthesis, or secured long‑term purchase agreements. The report models multiple raw‑material price paths and their effect on pass‑through mechanics to battery makers.
-
Policy and localization: Announcements of new North American manufacturing facilities and incentive‑driven localization have direct implications for cell‑maker sourcing strategies. Some projects have proceeded; others have been deferred or cancelled, signaling a reallocation of risk and capital that buyers and suppliers must track continuously.
Strategic playbook: recommended actions for 2026
-
Producers: Prioritize investments that shorten OEM qualification timelines (local labs, sample lanes), secure upstream inputs via long‑term contracts or JV structures, and selectively pursue bolt‑on acquisitions to scale purification capability.
-
OEMs and Tier‑1 battery integrators: Implement multi‑tier sourcing strategies that balance a small number of qualified strategic suppliers with a broader pool of qualified backups to mitigate single‑point supply disruptions.
-
Investors and PE: Use our risk‑adjusted valuation templates to screen targets for IP defensibility, contract stickiness, and the ability to meet automotive‑grade traceability and safety certifications.
-
Policymakers and regional planners: Recognize that electrolyte supply is a critical enabler of battery sovereignty. Incentivizing not just cell assembly but the upstream electrolyte and salt ecosystem materially improves local resilience.
How to use the full report in your 2026 planning cycle
-
Integrate our scenario outputs into board‑level capital allocation decisions and rolling 18‑month operating plans.
-
Use the supplier scorecards as a short‑list for qualification and commercial negotiations; adopt the procurement templates and hedging playbooks for immediate cost containment.
-
Leverage the M&A shortlists and diligence checklists to accelerate deal screening and reduce time to close for strategic acquisitions.
Next steps & how we can help
The full PW Consulting report contains the granular segment breakouts, downloadable financial models, plant‑level capacity schedules, and proprietary scenario files that corporate and investment clients use to make binding 2026 decisions. This introduction is designed to outline the decision‑relevant insights and to demonstrate the rigor of our approach while reserving the detailed datasets for the report and client workshops.
To move from insight to action in 2026, we recommend: commissioning a bespoke supply‑chain stress test, scheduling a supplier qualification acceleration program, and running a focused M&A sprint using our target shortlists. Contact PW Consulting to access the full report, the Excel model, and to arrange a workshop that aligns the findings to your firm’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Lithium Ion Battery Electrolyte Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com