

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tobacco & Hookah Market Set for 3.45% CAGR

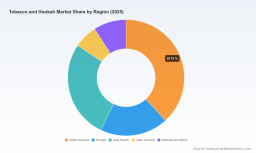
Tobacco and Hookah Market 2026 — Strategic Preview for Decision-Makers
PW Consulting presents a high‑altitude, decision‑oriented preview of our full Tobacco and Hookah Market study (base year 2025, historical 2020–2025, forecast 2026–2032). This briefing synthesizes the macro trajectory, regulatory inflection points, competitive dynamics and practical playbooks that will matter most to commercial leaders in 2026 — while intentionally withholding granular segment tables and region/application splits to preserve the value of the full report.
Tobacco and Hookah Market
Why this preview matters for 2026 decisions
Executives planning product launches, market entry or M&A in the tobacco and hookah space face a convergence of steady structural growth, episodic shocks and accelerating regulatory complexity. At the macro level, the market has shown modest but consistent expansion through 2025, and our modelling projects continued growth at a compound annual growth rate (CAGR) of approximately 3.45% over the 2026–2032 forecast window.
Tobacco and Hookah Market
To translate that headline growth into competitive advantage, companies must align portfolio choices, supply chain resilience and regulatory strategy in 2026 — the year when several policy changes and enforcement updates take practical effect across major markets.
Tobacco and Hookah Market
Market trajectory: what the numbers signal (not what they hide)
-
Historical resilience. After steady growth through early 2023, the sector experienced a short‑term market softness in 2024 and then a rebound into 2025. This pattern highlights the market’s sensitivity to regulatory cycles, commodity pricing and channel disruptions rather than a permanent demand collapse.
-
Moderate expansion ahead. Our base modelling shows the market progressing from its 2025 position into a larger market by the end of the forecast period, reflecting stable end‑consumer demand for both traditional tobacco and hookah formats, combined with incremental adoption of adjacent product formats in select markets.
-
Concentration and competitive headroom. Market concentration metrics indicate a moderate level of fragmentation: the top three firms account for under one‑third of market share, while the top five approach less than half of the total. That structure leaves meaningful space for new entrants, regional champions and roll‑up strategies.
Demand drivers and supply pressures to watch in 2026
-
Premiumization and experience. Consumer spending is shifting toward premium formats, differentiated flavors and experience‑led channels (flagship lounges, curated cafes). Brands that translate sensory differentiation into premium pricing will protect margins even in an environment of modest volume growth.
-
Product adjacency and substitution. Electronic nicotine delivery systems (ENDS), heat‑not‑burn variants and nicotine pouches continue to alter competitive sets. Regulatory treatment of these products will change local demand patterns quickly, creating both substitution risk and new opportunities for tobacco incumbents.
-
Input cost volatility. Raw tobacco leaf prices remain a material factor in margin planning. Depending on leaf class and origin, leaf prices can vary significantly, and prime flue‑cured inputs have shown notable price peaks in recent years — a dynamic that favors firms with hedging, diversified sourcing or vertically integrated supply chains.
-
Regulatory tightening and excise modernisation. Jurisdictions are actively revising excise and product‑scope rules. Notable developments include proposals to modernize excise frameworks to capture novel nicotine products and state‑level restrictions that alter retail footprints. These shifts will materially affect pricing, channel economics and compliance costs in 2026 and beyond.
Regulatory inflection points that change strategy in 2026
-
Enforcement and market access updates: Recent regulatory activity from major authorities underscores dual trends: stricter enforcement against unauthorized products, and selective market access for authorised ENDS and related products. Firms should expect a bifurcated environment where compliant innovation is rewarded while non‑compliant SKUs face swift market exclusion.
-
Excise scope expansion: Policymakers in several large markets are moving to extend excise frameworks to encompass e‑cigarettes, heated products and nicotine pouches — shifting relative price relationships and creating winners among product formats that are either more tax‑efficient or easier to regulate.
-
Localized retail regulations: State and regional statutes around retail mixing (e.g., restrictions on co‑location of certain products) will influence retail network strategies and channel economics, prompting reconfiguration of distribution and direct‑to‑consumer approaches.
Competitive landscape — who to benchmark and why
The market blends global tobacco multinationals, specialist hookah manufacturers and regional leaders. Below we summarize strategic positions to track; the full report contains deeper financial and capability benchmarking.
-
Al Fakher (Dubai) — A global name in flavored hookah tobacco and a recognized supplier to cafes and home users. The brand’s strength is deep category recognition and large flavor portfolios. Watch its channel plays and export orientation for partnership or licensing opportunities. ( https://www.alfakher.com/)
-
AIR Global (Dubai) — A major manufacturer with multi‑brand scale, including ownership of established labels. Its manufacturing scale and distribution reach create a cost advantage and make it a likely consolidator or preferred supplier for large retailers. ( https://www.air.global/)
-
Hookah.com (North Carolina) — A channel specialist with strong retail and accessory offerings, well positioned to capture premium domestic consumers and omnichannel demand. Its direct retail experience can be a model for D2C expansion. ( https://hookah.com/)
-
Altria Group (US) — An incumbent with deep go‑to‑market muscle in regulated markets. Its capability to navigate domestic regulation and leverage scale for product rollouts remains a competitive moat. ( https://www.altria.com/)
-
Philip Morris International (Switzerland) — Aggressively pursuing heat‑not‑burn and adjacent product strategies; its global reach means it can arbitrage regulatory environments and accelerate commercialization of hybrid formats. ( https://www.pmi.com/)
-
NJOY LLC (US) — Known for ENDS and related nicotine offerings; an indicator firm for how ENDS players may vertically integrate into hookah or tobacco flavors if regulation permits. ( https://www.njoy.com/)
-
Tangiers Tobacco (US) — A specialist shisha producer with niche appeal among connoisseurs; an example of brand strength driven by product authenticity and community. ( https://tangierstobacco.com/)
Recent developments that require immediate attention
-
Regulatory guidance and authorisations issued in 2026 shifted enforcement priorities and created pathways for authorised products to expand — rapidly changing the compliance landscape for ENDS and other nicotine products.
-
At the regional level, proposals to modernize excise duties are already influencing pricing strategies and long‑range tax modelling across product portfolios.
What our full report contains (practical, executable resources)
-
Transparent market sizing methodology and downloadable time‑series (historical and forecast) with scenario toggles for alternate price and regulatory scenarios.
-
Channel maps and route‑to‑market playbooks for premium, mass‑market and online strategies — including margin waterfalls, promotional elasticity and recommended retail footprints.
-
Regulatory matrix and impact heatmap covering major jurisdictions and projection of effective dates for key policy changes.
-
Supplier cost model and hedging playbook that captures leaf price sensitivities, input substitution and near‑term procurement steps to protect margin.
-
Competitive scorecards for leading manufacturers and brand portfolios, with capability gap analyses for M&A and JV targets.
-
Practical commercial templates: SKU rationalization framework, trade promotion optimization rubric and a 100‑day launch plan for new product introductions.
Strategic actions for leaders in 2026 (what to do now)
-
Prioritise regulatory intelligence. Establish a cross‑functional regulatory war room to map submissions, authorisation timelines and enforcement risks — treating compliance as a front‑line commercial lever.
-
De‑risk supply with diversified sourcing and hedging. Given input price volatility at the leaf level, build alternative origins and secure fixed‑price contracts or inventory hedges for critical SKUs.
-
Invest selectively in premium and experiential formats. Allocate a controlled share of innovation spend to flavor development, packaging and lounge/experience activations that defend pricing power.
-
Pursue pragmatic M&A and partnerships. Target assets that add manufacturing scale, geographic access or channel control — particularly regional players with concentrated customer loyalty.
-
Test hybrid product strategies where regulatory windows exist. Use pilot markets and modular SKUs to evaluate heat‑not‑burn and adjacent formats without over‑exposing legacy channels.
-
Build digital direct channels in parallel with wholesale. Digital D2C can both capture margin and act as a laboratory for rapid consumer learning on flavors and bundles.
Conclusion — the executive imperative
2026 will be a year of selective opportunity: steady market expansion offers predictable runway, but regulatory realignment and input volatility will determine who captures the upside. Firms that combine disciplined regulatory planning, supplier flexibility and consumer‑led premiumisation will convert the market’s modest CAGR into disproportionate returns.
For strategy teams, commercial leaders and investors preparing decisions in 2026, our full Tobacco and Hookah Market report provides the segment‑level tables, scenario models and executable playbooks that turn insights into action. Access to the detailed segmentation, regional splits and company‑level analytics is available through the report portal; PW Consulting’s advisory team is ready to translate the findings into a customised 90‑day plan for your business.
— PW Consulting, Senior Strategy Consultant & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Tobacco and Hookah Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com