

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Double-Edged Blades Market to Hit USD 1,480M by 2032 (9.0% CAGR)

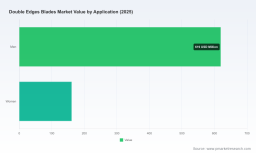
Double Edges Blades Market 2026: Strategic Imperatives from PW Consulting
As PW Consulting’s Senior Strategic Advisor and Lead Industry Analyst, I present a focused preview of our new market study on the Double Edges Blades sector. This briefing is designed as a strategic "trailer": it demonstrates the analytic depth and decision-grade insights that corporate leadership teams will need in 2026, while reserving the granular segmentation tables and supplier-level intelligence for the full report.
Double Edges Blades Market
Why this market matters in 2026
The double edges blades market is at an inflection point. After recovering from mid-decade volatility, the global market expanded from a baseline around USD 600 Million in 2020 to roughly USD 780 Million by the 2025 base year used in our study. Our forecast period (2026–2032) projects a sustained acceleration, with an aggregate compound annual growth rate (CAGR) of 9.0%, driving the market toward a significantly larger scale by 2032. That trajectory elevates the segment from niche legacy appeal to a strategically relevant component of personal-care portfolios and industrial supply chains alike.
Double Edges Blades Market
What makes 2026 a pivotal planning year?
- Regulatory convergence: New interpretation and enforcement of product and packaging standards (notably FDA device registration obligations and EU packaging regulations) require investment decisions now to avoid downstream noncompliance costs.
- Sustainability-triggered redesign: Buyers and retailers are accelerating the shift away from single-use plastics toward steel-and-cardboard solutions; packaging redesigns begun in 2026 will hit retail shelves in 2027–2028.
- Channel evolution: Direct-to-consumer brands, subscription models and cross-border e‑commerce continue to reshape pricing and customer acquisition economics. Established manufacturers must update go-to-market models or cede margin to pure-play digital brands.
What PW Consulting’s Double Edges Blades Market Study delivers
The full report is structured to support immediate strategic decisions in 2026 and the operational plans that follow. Key practical deliverables include:
Double Edges Blades Market
- Market sizing and validated demand curves (historical 2020–2025; base year 2025) and a scenario-driven forecast suite for 2026–2032 (central case anchored at a 9.0% CAGR).
- Demand segmentation frameworks and buyer archetypes that explain what drives repeat purchase across consumer cohorts and retail channels—plus playbooks for converting high-LTV segments.
- Supplier and capacity maps, including vetted lists of manufacturing partners, contract manufacturers and specialty processors with audit-ready due-diligence checklists.
- Price-pack architecture and margin benchmarks spanning commodity blades to premium-treated and coated SKUs—built from primary pricing sweeps and channel-level margin inversions.
- Regulatory compliance roadmaps (FDA registration, ISO 3558 safety testing, CE marking for EEA markets) and a practical timeline for labeling, registration, and test-lab throughput planning.
- Packaging transition playbook tied to EU packaging mandates: material substitution cost models, supplier qualification templates, and retailer acceptance criteria.
- Manufacturing cost model with sensitivity to raw-material inputs, yield improvements, and coating/heat-treatment process choices—designed for capex and capex-light operations planning.
- M&A and partner-screening criteria: proprietary scoring that ranks targets for scale, technology, route-to-market, and cost synergy potential.
- Three stress-tested strategic scenarios (baseline growth, premiumization squeeze, and rapid-cost inflation) and the discrete response playbooks that senior management can operationalize within 90–180 days.
Competitive landscape — what incumbents and challengers are doing
The market is moderately fragmented by revenue concentration; our top-line concentration metrics indicate that the largest three players account for less than one-quarter of global revenues, with a similar spread for the top five. That dispersion creates room for both scale plays and differentiated niche strategies.
Leading consumer and specialty brands in this space exhibit distinct strategic postures:
- Global consumer leaders leverage brand trust, broad retail distribution, and integrated marketing to defend premium-priced stainless steel lines. Expect continued investment in brand-backed innovation and co‑branded retail assortments.
- Premium specialty producers emphasize metallurgy, precision grinding and plating processes that deliver superior shave quality and longevity. These firms command price premiums among discerning wet-shave consumers and barbershop channels.
- Large-scale cost players focus on volume distribution through private label programs, value retail, and OEM contracts—competing on manufacturing efficiency and scale rather than brand.
- Emerging market suppliers and contract manufacturers are active at trade fairs and accelerating export programs; their participation in global sourcing is changing logistics and lead-time norms.
Representative names that define competitive dynamics today include long-established consumer brands, heritage European manufacturers, Japanese precision specialists, and a set of growing suppliers in East Asia and Taiwan. Each group presents different implications for pricing, product quality, and partnership choices.
Recent industry movements with strategic implications
- Trade fair activity in early 2026 has been intense among contract and regional suppliers, signaling renewed supply-chain outreach and buyer-supplier rebalancing. Suppliers exhibiting at major trade events are actively courting international buyers for volume contracts.
- Regulatory clarifications—particularly the classification of razor blades under medical-device or consumer product regimes in certain jurisdictions—have tightened speed-to-market and documentation requirements. Firms must plan for registration and label-change lead times measured in quarters, not months.
- Packaging mandates in the EU are compressing redesign cycles: those who delay will face higher inventory write-offs and heavier listing friction with major European retailers.
Dynamics to watch: raw materials, standards, and margin pressure
Material choice remains the primary determinant of cost, positioning and customer percept. Stainless steel and specialty-coated blades are central to premium and durability claims, while carbon-steel and economy lines sustain price-driven volume. Standards and conformity requirements—ISO testing regimes and regional CE/FDA obligations—raise the bar for suppliers, particularly those seeking cross-border growth.
At the same time, input-cost volatility and logistics complexity are pressuring gross margins across all segments. The firms that will outperform through 2028–2032 are those that combine material-technology differentiation with disciplined supply-chain hedging and modular packaging strategies.
Strategic recommendations for 2026 decision-makers
- Prioritize compliance-capability investments: Treat regulatory registration, ISO testing slots, and packaging requalification as strategic assets. Early investment reduces time-to-shelf friction and opens preferred listings with large retailers.
- Segment product portfolios: Simplify SKUs where margin is thin and double-down on higher-margin coated or premium-treated blades that benefit from brand-back claims and subscription economics.
- Design for sustainability now: Migrate packaging away from unrecyclable plastics in product families targeted at Europe. Negotiate long-lead framework agreements with eco-material suppliers to lock in costs and supply priorities.
- Hedge raw-material exposure: Use staged procurement contracts and dual-sourcing to manage stainless-steel and specialty coating input risk; validate alternative alloy formulations in controlled lab trials.
- Consider targeted M&A or JV moves: Use acquisitions to buy capacity, certification, or distribution in geographies where organic entry is slow or capital-intensive.
- Build direct channels strategically: Create subscription-first offerings for premium blades while retaining a compact retail footprint for mass-volume SKUs—each supported by differentiated logistics and customer-acquisition economics.
How to use this research in your 2026 planning cycle
Leadership teams should use the report to inform three immediate activities this year:
- Board-level scenario planning: Stress-test budgets and capex for the three supply and regulatory scenarios in our forecast suite.
- Commercial prioritization: Rebase SKU rationalization and channel strategies against the price-pack and margin matrices in the report.
- Risk mitigation: Implement the supplier audit templates and compliance roadmaps to eliminate bottlenecks that typically emerge 6–9 months before new market-entry dates.
Closing: Why PW Consulting’s analysis is decision-grade
Our study combines primary interviews, on-site supplier verification, trade-fair intelligence, and confidential pricing sweeps to deliver forecasts and operational templates that translate directly into 90–180 day actions. We intentionally withhold selective segment-level tables and supplier scores from this preview to preserve the practical exclusivity that makes the full report an executable toolkit for 2026 decisions.
For companies that must choose between incremental optimization and strategic repositioning this year, the report offers the evidence base and operational checklists needed to accelerate the right choices with minimal disruption. To access the full segmentation matrices, supplier due-diligence lists, margin models and downloadable scenario tools, please consult the PW Consulting source page for the Double Edges Blades Market study.
For detailed analysis of this topic, please visit the official page: Double Edges Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com