

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Feed + Aquafeed Market Poised for 6.0% CAGR Through 2032

Feed + Aquafeed Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
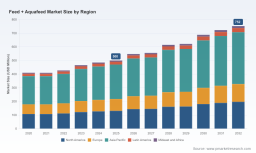
As the feed and aquafeed complex enters a new strategic inflection, PW Consulting’s Feed + Aquafeed Market study offers a tactical and operational playbook tailored for 2026 corporate decision cycles. The market has expanded materially over the past half‑decade — growing from roughly USD 410 million in 2020 to about USD 500 million in our base year of 2025 — and is projected to continue at an approximate 6.0% compound annual growth rate, reaching near USD 752 million by 2032 under the central scenario. That trajectory masks important heterogeneity across product types, geographies and value chains; our research isolates those differentiators while preserving the competitive intelligence that executives need to act with conviction.
Feed + Aquafeed Market
Why this preview matters for 2026 strategy
-
Investment timing: 2026 is a pivotal year for allocating capital toward capacity expansion, product development, and strategic partnerships. Moderate, sustained growth at ~6% CAGR creates attractive windows for targeted investment, but requires precision in site selection and product mix to avoid margin dilution.
Feed + Aquafeed Market -
Regulatory inflection points: Sustainability certifications and feed standards are shifting purchasing criteria for large buyers and retailers. Early movers on certification and traceability can convert compliance spend into commercial advantage.
Feed + Aquafeed Market -
Supply‑chain resilience: Volatility in feedstock markets and the rise of ingredient co‑products call for new procurement strategies — from long‑dated offtakes to technical partnerships that validate alternative ingredients in species-specific formulations.
Macro picture: growth, structure and near-term momentum
The sector’s steady expansion over the historical 2020–2025 period has transitioned into the forecast window with momentum driven by protein demand, intensification of aquaculture and livestock systems, and rising feed conversion optimization. Our model — built on granular production, price and input indices — shows a continuation of mid‑single digit annual growth through 2032 under the central case, with upside and downside scenarios tied to commodity cycles, certification uptake and disease dynamics in high‑value species.
Market structure is neither a monopoly nor completely fragmented: large multinationals maintain strategic positions through scale, proprietary formulations, and integrated sourcing, while regional specialists and contract manufacturers capture niche and species‑specific demand. This balance creates a marketplace where both consolidation plays and specialist differentiation strategies can succeed, but they require different execution rhythms and capital plans.
Key dynamics shaping 2026 decisions
-
Sustainability and certification: Certification schemes and buyer requirements are escalating. Several leading producers advanced ASC Feed Certification across multiple mills in recent years, raising the bar for market entry in premium supply channels and signaling an immediate need for risk assessments tied to certification timelines.
-
Ingredient innovation & substitution: New entrants and co‑product streams (e.g., high‑protein DDG derivatives and corn protein concentrates) are maturing as viable ingredient classes. Robust inclusion trials and supplier partnerships are making these inputs operationally relevant for commercial diets, particularly where cost‑to‑performance improves feed economics without compromising growth.
-
Formulation and species specialization: Premium, species‑specific feeds and functional formulations (antimicrobial‑reducing, immune‑supporting diets) are becoming a differentiator in higher margin segments. Product launches targeting health and survivability in certain high‑value species demonstrate both R&D focus and willingness of buyers to pay for outcomes.
-
Channel and geographic nuances: Growth pockets are uneven — some regions show faster aquaculture intensification while others remain driven by livestock feed demand and feed mill modernization. Navigating market entry is as much about partnership and distribution design as it is about product formulation.
-
Digital and on‑farm precision: Adoption of feed management software, sensors, and performance analytics is enabling feed companies to bundle services, reducing price sensitivity and increasing lifetime value of farm clients.
Competitive landscape — what leading players signal for rivals and investors
The competitive set is composed of multi‑national integrators, regional champions, and technology‑focused specialists. Several themes stand out across the leading firms we examined:
-
Cargill: Scale and integrated supply chain give the firm leverage across ingredients, formulation science and global procurement. Their multi‑mill footprint supports rapid product rollouts across species and geographies.
-
Skretting: A clear strategic focus on sustainability and certification has translated into upgraded partnerships and preferential access to premium buyers. Their facility upgrades and multi‑country production model are designed to support large contract volumes and sustainability premiums.
-
BioMar: Specialization in high‑value, species‑specific feeds positions BioMar as an R&D and premium product leader. Recent functional feed launches underscore the commercial payoff from investing in targeted formulations for disease mitigation and performance.
-
Alltech: Nutrition science and additives are converging with feed manufacture, enabling a solution‑selling model that enhances feed efficiency and animal health outcomes — a pathway to protecting margins under pricing pressure.
-
Regional players (Aller Aqua, Thai Union Feedmill, Purina, Ridley): These companies combine market intimacy, branded products and local supply chain advantages. Strategic tie‑ups or selective capacity investments can yield outsized returns in constrained markets.
Recent corporate moves — strategic agreements, MOUs to enter new markets, and product launches addressing species‑specific health issues — collectively indicate an industry accelerating both consolidation of capabilities and thinner margins in bulk segments, while expanding premium opportunities in health‑oriented feeds.
Strategic implications and a 2026 decision checklist
For boards, investors and commercial leaders considering allocations or strategic pivots in 2026, we recommend a structured approach:
-
Prioritize certification and traceability investments where premium channels exist or where buyer requirements are firming. Early certification creates a defensible commercial position.
-
Pilot and validate alternative ingredients via joint trials with reputable suppliers and contract farmers. Our analysis indicates that technical partnerships accelerate commercial adoption and de‑risk formulation changes.
-
Design M&A screens that differentiate between capacity‑seeking transactions and technology/brand acquisitions. Integration playbooks should be prepared in advance to capture synergies without diluting specialty margins.
-
Build on digital service propositions that increase stickiness with farm customers — data packages and feed performance guarantees materially change negotiation dynamics with large integrators.
-
Stress‑test procurement portfolios under commodity shock scenarios and evaluate hedging or long‑term offtake strategies for critical raw materials.
What the full PW Consulting report delivers (operational highlights)
The published study goes beyond narrative: it contains the full quantitative model, scenario matrices, and tactical playbooks you need to convert insight into action. Highlights include:
-
A calibrated historical and forecast model (2020–2032) with base‑year granularity and alternative demand scenarios.
-
Supplier benchmarking and capability heatmaps comparing technical capacity, certification status, product portfolios and geographic reach across the competitive set.
-
Regulatory tracker and certification roadmap that maps likely timing and commercial impact of sustainability standards on trade flows and premium channels.
-
Raw material intelligence, including evolving co‑product streams and commercial readiness assessments for corn protein concentrates and HP‑DDG derivatives from key suppliers.
-
Commercial playbooks: go‑to‑market strategies for premium feeds, contract manufacturing models, and integration templates for acquisitions and JV formations.
-
Risk matrices and mitigation options covering disease outbreaks, ingredient shocks, and policy changes — all tied to quantified P&L sensitivities for informed capital allocation.
How to use this intelligence in 90 days
Executives can translate the study’s insights into near‑term actions with a focused 90‑day plan:
-
Week 1–3: Rapid diagnostic — align leadership on priority geographies and species segments; run the sensitivity module for your P&L.
-
Week 4–8: Commercial pilots — initiate formulation trials with vetted ingredient partners; scope certification requirements for priority production sites.
-
Week 9–12: Execute strategic moves — finalize selective offtake contracts, begin integration planning for targeted acquisitions, and deploy a customer retention program tied to digital services.
Closing note — the trailer principle
This preview is intentionally diagnostic: it surfaces the structural forces, competitive moves and tactical options that will shape winners and laggards in 2026. The full PW Consulting Feed + Aquafeed Market report provides the detailed segmented datasets, company scorecards, and financial models that underpin the recommendations summarized above. If your 2026 plan depends on precise region‑type‑application allocations, mill‑level certification status or vendor‑specific price curves, the complete dataset and accompanying workshop materials are the decision support tools you will need to execute confidently.
PW Consulting stands ready to walk your team through the model, customize scenario runs to your balance sheet, and translate the research into an executable M&A, product or procurement roadmap for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Feed + Aquafeed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com