

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polycarbonate Sheet Market to reach USD 6,450M by 2032 at 5.46% CAGR

Polycarbonate Sheet Market — Strategic Outlook for 2026 Decision-Making
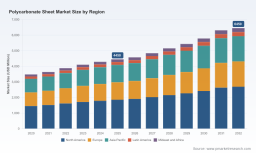
As organizations map growth and resilience strategies for 2026, polycarbonate sheets have emerged as a strategically material market: capital-intensive to scale, sensitive to feedstock volatility, and tightly coupled to construction, transport, and electronics cycles. PW Consulting’s latest market study—anchored on a 2025 base year with a historical view from 2020–2025 and a forward projection to 2032—quantifies a clear growth trajectory. The global polycarbonate sheet market expands at a compounded annual growth rate (CAGR) of 5.46% across the forecast window, progressing from a market size of USD 3,480.4 Million in 2020 to an estimated USD 4,450.0 Million in 2025 and approaching USD 6,450.0 Million by 2032. These headline dynamics set the frame for near-term commercial choices: where to invest, where to hedge exposure, and how to position product portfolios against competing plastics and emerging regulation.
Polycarbonate Sheet Market
Why this study matters to executive teams in 2026
-
Capital allocation and capacity planning: With several large-scale capacity initiatives announced across the value chain, detailed demand scenarios and supplier impact maps in this study enable CFOs and plant strategists to time expansions, retrofit initiatives, or contract manufacturing decisions to manage utilization and margins.
Polycarbonate Sheet Market -
Sourcing and feedstock risk management: The market is increasingly shaped by Bisphenol A (BPA) and energy-linked cost swings, regional tariff regimes, and logistics inflation. Procurement leaders will find the report’s scenario-based cost curves and supplier concentration analysis essential to redesign multi-sourcing strategies and hedge instruments.
Polycarbonate Sheet Market -
Product and channel strategy: The diversity of polycarbonate formats—from solid and multiwall to corrugated profiles—creates differentiated margin structures and route-to-market implications. Marketing and product teams can use our adoption-risk matrices to prioritize SKUs for volume growth vs. high-margin customization.
-
M&A and partnership screening: Given an elevated market concentration among the leading suppliers, strategic buyers and private equity investors will benefit from our proprietary target fit framework that overlays capability maps with regulatory and raw material exposures.
What’s inside the report (practical, actionable deliverables)
-
Demand and supply modelling with three distinct scenarios (base, upside, downside) through 2032, using a bottom-up volume and revenue architecture that captures long-cycle construction, automotive cycles, and short-cycle industrial demand signals.
-
Price and margin sensitivity tools that translate Bisphenol A and energy price pathways into producer margin bands and suggested indexation strategies for commercial teams.
-
Supplier benchmarking and capability heatmaps: operational footprint, technology differentiation (UV-stabilized grades, fire-retardant formulations, high-transmission diffusers), logistics and lead-time profiles, plus a regulatory-compliance checklist for major markets.
-
Go-to-market playbooks for four archetypal firms (global producer, regional fabricator, distributor-led model, and specialist custom extruder), with practical KPIs, sales incentives, and channel economics templates.
-
Risk matrix and mitigation blueprints covering feedstock shocks, tariff shifts, trading restrictions, and compliance costs tied to chemical policy trajectories in Europe and North America.
-
A concise M&A playbook including valuation multiples observed in recent deals, integration priority checklists, and a list of value-creation levers from procurement harmonization to SKU rationalization.
Market structure and competition — qualitative implications
The polycarbonate sheet industry displays significant consolidation among top producers (our market concentration analysis shows three-firm concentration in the high double-digits and five-firm concentration that is substantially higher), which has practical consequences for competitive dynamics. High concentration implies that strategic moves by any of the leading players—capacity expansion, product innovation, or distribution partnerships—can materially shift regional supply balances and pricing power.
-
Plaskolite, Inc. (Columbus, Ohio): A North American bellwether with direct production capability and broad grade coverage. Plaskolite’s focus on engineered thermoplastics, including high-transmission and specialty white diffusing sheets, positions it as a natural partner for OEMs requiring reliable domestic supply and predictable lead-times. Its recent product introductions underscore a go-to-market emphasis on printability and surface performance—attributes that matter for digital signage and interior architectural applications.
-
Palram Industries Ltd. (Israel): Known for corrugated and flat solid lines, Palram’s global distribution and established branded SKUs make it a credible rival in construction and DIY channels. Their emphasis on sustainable options is increasingly important in tenders where lifecycle and recyclability are procurement criteria.
-
Excelite Plastic Co., Ltd. (Suzhou) & other Chinese manufacturers: Specialist exporters with in-house fabrication and a cost-competitive position. These players excel at serving volume-driven channels and export markets, but their exposure to international tariffs and shipping volatility can create windows of opportunity for localized producers.
-
Regional fabricators and distributors (e.g., Varico LTD, A&C Plastics): These firms convert sheets into fit-for-purpose components and manage inventory-to-order cycles for local markets. They are key partners for global players aiming to reduce last-mile costs and improve responsiveness in renovation and retrofit segments.
Recent market signals that should shape 2026 strategies
-
Capacity shifts: Large-capacity investments announced by major chemical players signal tighter domestic supply dynamics in certain markets. For example, announced expansions in North American polycarbonate compounding and line additions targeted at customized blends point to potential improvement in availability—but also to near-term competition for skilled labor, utilities, and logistics.
-
Product innovation: New product introductions—such as high-transmission, light-diffusing sheet grades tuned for first-surface digital printing—highlight where demand is moving (value-added, design-driven applications). Firms that prioritize application-specific testing and co-development with OEMs can capture margin uplift.
-
Raw material pressure: Bisphenol A price movements and energy-linked production costs are translating into step changes in raw material cost bases across regions. Procurement teams must stress-test contracts against both immediate spikes and extended elevated price environments.
-
Regulatory and trade friction: Geopolitical tensions and tariff regimes are actively reshaping trade flows. At the same time, regulatory initiatives—especially chemical transition pathways in Europe—are increasing compliance burdens and could accelerate demand for alternative formulations or recycled content solutions.
-
Cost inflation and logistics: Persistent inflationary pressures and higher freight costs are compressing manufacturer margins and raising the break-even distance for exports. Nearshoring or regional sourcing strategies are increasingly economically rational for higher-value sheet formats.
Strategic imperatives — what winning looks like in 2026
-
De-risk feedstock: Implement layered hedging (short-term physical cover + options) and diversify BPA suppliers across geographies. Consider long-term offtake agreements with conditional price ladders tied to transparent indices.
-
Prioritize product differentiation: Invest in UV-stabilization, fire-rating certifications, and surface finishes that unlock higher-margin channels (signage, architectural facades, specialized glazing).
-
Localize selectively: Evaluate nearshoring for high-value, time-sensitive SKUs while keeping commoditized volumes in cost-advantaged corridors, adjusting for tariff and logistics breakpoints identified in our regional scenario maps.
-
Partner for circularity: Early movers toward recycled-content polycarbonate and take-back schemes will be better positioned as chemical policy tightens and lifecycle metrics feature in procurement decisions.
-
Refine channel economics: Reassess distributor agreements, inventory turn targets, and minimum order quantities to reduce working capital drag and improve fill-rates for premium SKUs.
-
Use acquisitions tactically: Look for bolt-on fabricators or regional distributors that provide route-to-market and customization capabilities, rather than large greenfield capacity builds unless backed by long-term offtake.
How to use the full PW Consulting report
This introduction provides the strategic framing and critical signals executives need to prioritize choices in 2026. The full report contains the granular models, interactive scenario dashboards, supplier scorecards, and regional/application split analyses that operational teams, commercial leads, and M&A advisors will require to execute. To preserve the predictive value of this research and to ensure you receive the actionable intelligence required for transaction-level or plant-level decisions, detailed segmentation numbers and the full set of financial modelling outputs are available only in the complete report package.
If your organization is preparing board-level recommendations, capital plans, or commercial reorganization for 2026, PW Consulting’s Polycarbonate Sheet Market study provides the scaffolding for defensible choices: robust scenarios, supplier-risk quantification, and a pragmatic set of playbooks proven in prior plastics and construction-material engagements. Use the study to prioritize actions that protect margin, shorten lead times, and future-proof product portfolios against regulatory and raw-material uncertainty.
For detailed analysis of this topic, please visit the official page: Polycarbonate Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com