

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tension Hand Grip Market to Grow at 6.98% CAGR, Reaching USD 344.8M by 2032

Tension Hand Grip Market — Strategic Briefing for 2026 Decision-Makers
As organizations set priorities for 2026, understanding the structural trajectory of the tension hand grip market is indispensable. PW Consulting’s latest market research (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes macroscopic growth metrics with executable commercial intelligence. The market expanded from roughly USD 163 million in 2020 to about USD 215 million in 2025 and is modeled to grow at a compound annual growth rate (CAGR) of 6.98% over the forecast horizon, reaching an estimated USD 344.8 million by 2032. These headline figures are not an endpoint — they are the basis for prioritized bets across R&D, distribution, pricing and M&A in 2026.
Tension Hand Grip Market
Why this research matters for 2026 strategic choices
-
Resource allocation: The market’s mid-single-digit CAGR indicates steady, investible growth rather than hyper-scale opportunity; capital should be targeted to high-return pockets rather than broad-based expansion.
Tension Hand Grip Market -
Portfolio focus: The product ecosystem includes adjustable and fixed-resistance devices plus ancillary forms (finger-specific trainers, cylinder/pinch tools). Choosing which product archetypes to scale should follow demand and margin projections presented in the report.
Tension Hand Grip Market -
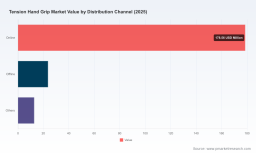
Channel strategy: Online channels have become a dominant route-to-customer; however, offline and hybrid models remain relevant for rehabilitation and institutional sales. Determining the right channel mix for 2026 requires the granular channel economics and scenario testing included in the full study.
-
Competitive positioning: The sector is fragmented (aggregate concentration metrics show a low-to-moderate top-player share). That fragmentation creates opportunity for niche differentiation, premiumization, and roll-up strategies.
Report contents — practical outputs for immediate use
-
Market sizing and forecasting model (2020–2032) built from primary interviews and supply-side validation. The model supports scenario toggles (demand shock, material-cost shock, accelerated direct-to-consumer adoption).
-
Segment and channel frameworks that map product archetypes to buyer use-cases (fitness, rehabilitation, occupational therapy, musicians/precision-skill users) with tactical recommendations for product-market fit.
-
Go-to-market playbooks for online-first, retail/club, and institutional channels — including distributor selection criteria, promotional cadence, and partnership archetypes.
-
Commercial benchmarks: margin curves by product family, suggested pricing tiers, and SKU rationalization guidance tailored for mid-size and enterprise players.
-
Supply chain and manufacturing roadmap: on-shore vs. off-shore trade-offs, BOM sensitivity analysis, and supplier readiness checklists for scale-up.
-
Competitive intelligence pack: deep profiles and strategic motion analysis for the market’s active manufacturers and brand owners (profiles summarize capabilities, IP positions, and go-to-market strengths).
-
M&A and partnership playbook: screening criteria for bolt-on targets, valuation heuristics, and integration checklists aimed at consolidators and corporate development teams.
-
Risk matrix and regulatory compass (product safety, materials, and claims), plus a prioritized list of data requirements to validate product claims in medical or therapeutic channels.
Competitive landscape — positioning and strategic implications
The market’s competitive field is populated by specialized niche brands and a handful of recognized names that command strong credibility with distinct customer cohorts. Aggregate concentration metrics (top-3 and top-5 shares in the mid-20% range) confirm that no dominant global incumbent has closed the market; this is a structural feature that shapes strategic options.
-
IronMind Enterprises, Inc. — A de facto premium standard-bearer for torsion-spring grippers and discrete resistance levels. IronMind’s strength is brand authority and specialist credibility among strength athletes; potential strategic moves for competitors include value-priced alternatives and complementary digital training ecosystems to capture a broader user base.
-
GD IND Corp. — A South Korea–based innovator with patented quick-adjust mechanisms and all-metal construction. Its patent-led engineering suggests defensive IP moats in adjustable hardware; license or design-arbitrage strategies should be evaluated by rivals.
-
WOD Nation — Aligned with high-intensity functional fitness, WOD Nation targets endurance and performance users. Strategic questions for incumbents: compete on community-driven programs or partner to access CrossFit-style distribution channels.
-
Prohands (Gripmaster) — Focused on finger-isolation devices and rehabilitation niches. This positioning exemplifies the value of clinical and therapeutic channels as differentiated, higher-margin distribution routes.
-
D’Addario & Company — With Varigrip products, the firm leverages core competency in finger/dexterity tools and distribution to musicians and precision-demand users. Cross-market branding and co-marketing approaches are instructive for players exploring adjacent customer segments.
-
TITLE Boxing Equipment — Brings sports-equipment distribution scale and progressive resistance variants. Traditional sports brands can leverage retail relationships to accelerate penetration for targeted product lines.
-
NEDVI, Grip Genie, Golden Grip — These brands illustrate market breadth: portable/ball-style devices, aluminum grippers, and high-resistance tools for crush/pinch performance. Collectively they demonstrate how product form-factor innovation and material selection define sub-segments.
Key market dynamics and implications to prioritize in 2026
-
Channel migration to digital: E-commerce continues to compress go-to-market timelines and reduce customer-acquisition cost for direct brands. Prepare for increased investment in content, customer retention flows, and D2C fulfillment capability.
-
Product differentiation via utility and data: Hardware differentiation will increasingly be paired with performance-tracking and mobile-integrated experiences — especially for rehabilitation and sports-performance buyers.
-
Therapeutic and institutional adoption: Clinical use-cases (physical therapy, occupational therapy) provide durable, higher-margin demand when supported by validated outcome data and clinician endorsements.
-
Materials and cost volatility: Metal and spring components are sensitive to commodity cycles; sourcing strategy and design-for-cost optimization should be immediate priorities for product teams.
-
IP and design advantages: Patented adjustment mechanisms and unique form factors create defensible niches — pursuing or acquiring specific design IP can accelerate defensibility.
-
Fragmented market = acquisitive runway: Low top-end concentration makes the sector attractive for roll-ups and bolt-ons to build scale in manufacturing and distribution.
Concrete next steps for 2026 planning (90-day and 12-month horizons)
-
90-day: Run a portfolio profit-to-investment review using the report’s margin maps; prioritize one adjustable or specialty product for a rapid digital pilot. Begin supplier risk assessment and shortlist 2–3 contract manufacturers for scale testing.
-
6–12 months: Execute a channel experiment (D2C + one retail partnership), finalize product-spec separations for therapeutic vs consumer SKUs, and initiate discussions with one potential bolt-on acquisition or licensing target informed by the competitive profiles.
-
12+ months: Scale successful pilots, institutionalize data collection for therapeutic claims, and deploy a phased national or regional roll-out guided by the report’s scenario-based forecasts.
Conclusion — what you gain and what remains behind the paywall
PW Consulting’s tension hand grip market study delivers a pragmatic bridge between headline market expansion and executable strategy: it quantifies the opportunity (2020–2032 trajectory and a 6.98% CAGR), maps competitive positions, and supplies operational playbooks for commercialization, supply-chain resilience, and acquisitive growth. To preserve the strategic advantage of subscribers, the public summary intentionally omits granular regional and product-split figures, exact channel economics and proprietary company market shares — these are included in the full report along with downloadable models, sensitivity worksheets, and vendor scorecards. For teams making investment, product, or M&A decisions in 2026, the complete dataset and playbooks are the necessary input to move from hypothesis to high-confidence action.
For detailed analysis of this topic, please visit the official page: Tension Hand Grip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com