

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Amorphous Metal Cores Market Set to Grow at 7.5% CAGR Through 2032

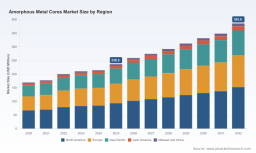
Amorphous Metal Cores Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, forward-looking primer on the amorphous metal cores market designed to inform executive decisions in 2026. This article synthesizes the market’s macro trajectory, competitive dynamics, and the strategic levers that will matter most to manufacturers, utilities, investors, and policy makers over the next strategic planning cycle. The intent is to demonstrate analytical depth while preserving the granular segmentation and proprietary datasets for the full report—viewing this as a high-value “preview” that signals where to dig deeper.
Amorphous Metal Cores Market
Market trajectory at a glance
The amorphous metal cores market has shifted from a niche technical solution to a measurable industrial market. On a consolidated basis (USD, revenue in Million), the market rose from roughly 169.5 in 2020 to about 236.5 in 2025, and is projected to reach approximately 385.6 by 2032, representing a compound annual growth rate of 7.5% over the forecast window. The immediate forecast point for 2026 sits near 259.2, underscoring continued near-term momentum.
Amorphous Metal Cores Market
These macro figures reflect a combination of demand-side drivers—grid modernization, stricter energy-efficiency regulations, and growth in distributed power electronics—and supply-side responses including capacity investments and material innovation. For executives planning 2026 capital allocation, these topline dynamics frame the probability of demand growth and the expected cadence of returns on investments tied to amorphous core production and integration.
Amorphous Metal Cores Market
Why this matters for 2026 corporate decisions
-
Capital allocation and capacity planning: A sustained mid-single-digit to high-single-digit CAGR implies that greenfield capacity or targeted expansions can achieve utilization thresholds within typical payback horizons—provided deployments are matched by offtake agreements and cost optimization.
-
Product portfolio and R&D prioritization: The technology landscape is bifurcating between cores optimized for lowest no-load loss in distribution transformers and alloys tailored to high-frequency power electronics. Prioritizing R&D to either improve core material performance or lower processed ribbon/unit costs will be a differentiator.
-
Procurement and supplier strategy: Supply-chain localization and strategic supplier partnerships (including tolling or licensing arrangements) will be important to manage raw-material volatility and geopolitical risk. Early contractual choices in 2026 will determine cost curves for the next five years.
-
M&A and alliance playbooks: With a moderately concentrated supply base (CR3 and CR5 metrics indicating industry concentration in the high-20s to low-30s percent range), targeted acquisitions or JVs can be used to secure technology, capacity, or market access without necessitating broad-scale consolidation.
Key strategic themes shaping the market
-
Energy-efficiency arbitrage: Regulatory tightening and utility-level TCO assessments place a premium on transformer cores that materially reduce no-load losses. Leading material technologies can lower no-load loss substantially versus conventional electromagnetic steel, changing replacement economics for utilities and industrial end-users.
-
Electrification and power-electronics demand: The accelerating deployment of EV infrastructure, renewables, and data-center power systems lifts demand for both low-frequency distribution cores and high-frequency specialized core materials. Product roadmaps should accommodate both waveforms and thermal profiles.
-
Localization of production: Manufacturers are rebalancing footprints toward end-market proximity to reduce logistics, currency exposure, and tariffs. Recent capacity moves indicate a strategic bet on local demand capture and faster time-to-market.
-
Material and process innovation: Alloy composition and strip processing (ribbon casting, annealing, coating) remain the technologic frontier. Some grades now claim materially higher saturation flux density and targeted performance across frequency ranges—attributes that alter component-level trade-offs.
-
Scale economics vs. customization: The industry will reward firms that can marry large-volume, low-cost ribbon production with nimble downstream core-forming and value-added assembly for specialized applications.
Competitive landscape — what executives need to know
The market’s competitive structure combines global technology leaders with regional or vertically integrated producers. A few strategic observations:
-
Proterial, Ltd. / Metglas, Inc. — Operating as primary producers of Metglas™ amorphous ribbon, these businesses combine proprietary alloy know-how with multi-continent production footprints. Notably, the group is expanding capacity with a new production site in India slated to come online in late 2026, a move that signals an intent to secure domestic demand and improve regional cost positions. Their commercial claims—such as a roughly one-third reduction in no-load loss compared to traditional electromagnetic steel in select transformer applications—are central to their product value proposition.
-
VACUUMSCHMELZE (VAC) — VAC’s VITROVAC® family demonstrates the industry’s material differentiation strategy. With Fe-based grades offering high saturation flux density (reported up to ~1.74 T for select alloys), VAC positions itself for applications requiring both power density and performance at frequency extremes.
-
Chinese volume players — Several large Asian manufacturers have scaled ribbon and core production, combining cost-competitive volume output with service models tailored to domestic and export customers. Their strategic advantage lies in manufacturing scale, integration with transformer OEMs, and supply-response agility.
-
Specialist manufacturers — Niche players that focus on particular core geometries or downstream assembly remain attractive partners for OEMs seeking tailored solutions, rapid prototyping, or bundled supply arrangements.
Collectively, the market exhibits moderate concentration (CR3 and CR5 metrics point to a sector where the top players control meaningful—but not dominant—share). This structure fosters both competitive pressure on pricing and opportunities for well-targeted vertical or geographic moves by challengers.
What the full PW Consulting report delivers
The companion market study provides the complete analytical toolkit executives need to act in 2026. Highlights include:
-
Comprehensive historical time series (2020–2025) and a transparent forecast model (2026–2032) with scenario sensitivity to material cost, regulatory shifts, and demand shocks.
-
Granular segmentation by product type, application, and geography (including downloadable tables and pivot-ready datasets). Note: this preview intentionally omits the detailed split tables to preserve proprietary insights available in the full report.
-
Supplier scorecards and SWOTs for the principal manufacturers, including capacity maps, technology differentiators, and recent capex announcements.
-
Demand-driver dossiers—regulatory lineage, utility procurement frameworks, and end-market adoption curves—translated into procurement and product-development decision rules.
-
Commercial playbooks: go-to-market strategies, partner-screening templates, sample offtake and tolling contract terms, and negotiation levers to secure long-term advantage.
-
Investor-ready financial models and IRR/NPV scenarios for greenfield production, brownfield expansion, and technology licensing cases.
-
Practical checklists for manufacturing transition (ribbon sourcing, annealing line investments, quality control metrics, and recycling loops).
How to use these insights in 2026
-
C-suite: Use the topline CAGR and forecast horizon to set capital allocation thresholds—define minimum utilization targets for new capacity and prioritize investments that shorten time-to-revenue (e.g., capacity in-market, strategic partnerships).
-
Product leaders: Align R&D roadmaps with the two-track demand profile—low-loss distribution transformer cores and materials optimized for higher-frequency inverters and converters. Focus on thermal management and manufacturability alongside magnetic performance.
-
Procurement heads: Reassess supply arrangements through a geography-and-risk lens. Evaluate short-term purchase agreements with options that scale into long-term contracts tied to indexed pricing or pass-through mechanisms to manage raw-material swings.
-
Investors and PE: Screen targets using the report’s supplier scorecards and valuation scenarios. The current concentration metrics indicate room for bolt-on acquisitions that can rapidly expand addressable capacity without creating monopoly risk.
Methodology note and limitations
The analysis is grounded in a transparent framework: historical base year 2025, historical series 2020–2025, and forecasts for 2026–2032. Revenue is reported in USD (Million) and growth is presented on a nominal basis with a central CAGR of 7.5% for the forecast interval. Company intelligence combines public filings, official product literature, press releases (including recent capacity announcements), and primary interviews. As a preview, this article omits detailed segmentation tables and certain unitized regional or application-level figures—those are available in the full dataset.
Next steps
For executives preparing budgets, negotiating supplier agreements, or evaluating strategic transactions in 2026, the full PW Consulting Amorphous Metal Cores Market report delivers the quantitative slices and negotiation-ready playbooks you need. The preview above highlights where value can be captured and where risk is concentrated—but the precise levers (regional mixes, application-specific adoption curves, and supplier-by-supplier capacity schedules) are contained in the complete study. Access the full report to download the forecast model, supplier scorecards, and the contract templates that we use with clients to translate insight into action.
PW Consulting stands ready to brief leadership teams, run tailored scenario workshops, and model bespoke investment cases. If your 2026 planning cycle depends on getting material, capacity, or product choices right, treat this market as a strategic lever rather than a technical accessory.
For detailed analysis of this topic, please visit the official page: Amorphous Metal Cores Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com