

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
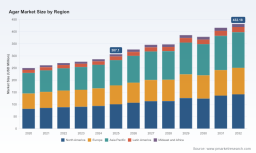
PW Consulting: Agar Market to Reach USD 432.18 Million by 2032 at 5.0% CAGR

Agar Market 2026 Strategic Primer: What Decision‑Makers Need to Know
Executive summary
As organizations set strategy for 2026, the agar market presents a blend of steady growth, concentrated supplier power, and episodic supply risks that make targeted intelligence indispensable. Our market model, calibrated to a 2025 base year and built on historical observations from 2020–2025, shows a compound annual growth rate of roughly 5% through the 2026–2032 forecast window. That trajectory translates into a clear, investable expansion path over the coming six years, with mid‑single‑digit organic demand growth, punctuated by short runs of volatility in raw material availability and pricing.
Agar Market
For senior executives — commercial leads, procurement chiefs, and corporate development teams — this research functions as a strategic playbook: it reframes the agar market from a commodity mindset to a portfolio of differentiated opportunities (from food & beverage uses to high‑value agarose resins for bioprocessing). Importantly, this introduction is a trailer: it demonstrates analytic depth and line of sight while reserving the granular segment matrices and price curves for the full report.
Agar Market
Why 2026 is a pivot year
-
Growth is steady but selective. The market’s mid‑single‑digit CAGR suggests predictable baseline demand — enough to support new investments, but not so rapid that late entrants will be rewarded without a focused strategy.
Agar Market -
Concentration matters. Market concentration metrics indicate the top three and top five players hold material influence over pricing and standards, making strategic supplier relationships and competitive positioning decisive for margin recovery and share gain.
-
Supply shocks are real and recent. Global raw material movements have led to significant price spikes in discrete periods; these episodes translate directly into margin pressure for manufacturers and higher procurement risk for buyers.
Key dynamics shaping near‑term decisions
-
Raw material supply volatility. The extraction of agar from red algae links the industry to geographically concentrated biological resources and weather patterns. In late 2023, market reports documented a sharp spike in spot prices for agar-agar powder in China, underscoring how limited supply can translate quickly into global cost pressure. For 2026 planning, stress‑tested procurement strategies and multi‑sourcing arrangements should be treated as baseline investments, not optional insurance.
-
Regulatory and quality expectations. Laboratory and clinical applications demand traceability and certified manufacturing. Leading producers supplying clinical and pharmaceutical customers operate under regulated systems and recognized standards; compliance investments (e.g., FDA registration, USP alignment, ISO QMS) materially affect total cost of ownership and time‑to‑market for higher‑value product lines.
-
Trade patterns and logistics. Export leadership is concentrated among a few countries, while certain markets remain reliant on imports. Freight dynamics, trade policy shifts, and regional sourcing preferences continue to shape build vs. buy decisions for end‑users and OEMs alike.
-
Product differentiation is increasingly strategic. Commodity agar still exists, but the most attractive pockets for margin improvement are in specialized agarose resins and application‑tailored grades for cell culture, diagnostics, and chromatography. These subsegments require closer collaboration with end customers and higher technical service intensity.
Competitive landscape — what incumbents are signaling
The market is served by a mix of global laboratory suppliers, specialized producers, and regional manufacturers. The competitive map is characterized by a few large, branded players with broad product portfolios and regulatory footprints, alongside niche specialists that target high‑value bioprocess and chromatography applications.
-
Becton Dickinson (Franklin Lakes, NJ, USA): A legacy supplier of bacteriological media and culture agars, with product lines targeted at diagnostic and microbiology laboratories. Their brand presence and distribution network make them a reference supplier for regulated end markets.
-
MilliporeSigma (Merck KGaA) (Burlington, MA, USA): Supplies agar and agarose grades across cell culture, microbiology, and research applications. Their portfolio and global reach position them as a preferred partner for life‑science customers seeking certified, high‑consistency inputs.
-
HiMedia Laboratories (Global operations headquartered in the U.S. for certain markets): Focused on dehydrated culture media and agars for microbiology and pharmaceutical testing, with regulatory certifications that support clinical and QA/QC end users.
-
Java Biocolloid (Indonesia): A regional specialist emphasizing native and specialty agars (including organic and fast‑soluble formats) for food, pharma, and industrial segments — a reminder that product innovation can be an effective route to commercial differentiation even from smaller bases.
-
Agarose Bead Technologies (ABT) (Burgos, Spain with US operations): A focused manufacturer of agarose resins and chromatography beads, actively investing in capacity and market expansion for bioprocess applications — their recent facility investments and trade‑show commitments indicate clear ambition in the high‑value subsegment.
Company activity across 2025–2026 underscores two themes: incumbents are consolidating their hold on regulated and high‑service markets, while smaller, specialized players are expanding selectively into high‑margin niches. For potential investors or partners, the choice between scale and specialization will determine which partnerships or acquisition targets make sense.
What the full report delivers (practical, decision‑ready content)
PW Consulting’s full agar market study has been structured for immediate operational use, not just high‑level briefing. Highlights include:
-
A forward model (2026–2032) with scenario runs (baseline, downside supply shock, and upside innovation adoption) to stress revenue and margin outcomes under realistic permutations of raw material and regulatory shock.
-
Supplier scorecards and a buyer‑supplier heat map that codify capabilities, regulatory certifications, and strategic fit for different end uses — enabling procurement and quality teams to prioritize vendor engagements.
-
Price‑sensitivity and margin impact tools that translate raw material price moves into P&L outcomes at various points along the value chain, calibrated to observed historical volatility.
-
Go‑to‑market playbooks by application cluster that guide product positioning, required certifications, and sales engagement models — particularly for higher‑value agarose and lab‑grade segments.
-
M&A and partnership screens: prioritized target profiles, valuation heuristics, and integration risk checklists for buyers seeking immediate scale or tech‑led capability additions.
-
Risk and resilience checklists covering sourcing diversification, inventory buffers, contractual clauses (e.g., force majeure and indexation), and contingency logistics pathways.
How to use this research in 2026 — recommended actions
-
For procurement leaders: implement multi‑tier sourcing for critical grades and adopt hedging or indexed contracts for exposure to raw material swings. Run the report’s supply‑shock scenario to quantify required buffer inventory and allowable lead times.
-
For commercial teams: prioritize differentiated product lines (e.g., agarose resins, certified lab agars) where technical barriers and service expectations defend pricing. Align go‑to‑market resources to support technical onboarding in clinical and bioprocess customers.
-
For M&A and corporate development: use the report’s target screen to evaluate bolt‑on buys that accelerate access to specialty resins or regional supply hubs. Pay attention to integration risks tied to regulatory compliance and plant certifications.
-
For R&D and product leaders: invest in formulation and process improvements that reduce raw materials intensity or increase product performance (e.g., faster solubility, organic/clean‑label grades). These innovations can convert commodity buyers into long‑term partners.
-
For risk managers: codify trigger points for activation of contingency plans (price thresholds, supplier failure rates) and test logistics playbooks against a realistic shock event modeled in the study.
Signal versus noise — what this primer leaves intentionally out
This brief intentionally surfaces the strategic implications and the analytical architecture without reproducing the granular segmentation matrices, region/application breakdowns, and proprietary price‑by‑grade curves that underpin our scenario runs. Those elements are the core of the paid study because they materially affect tactical choices (e.g., which regional market to prioritize first, which application pockets justify capex). If you are evaluating deployment of commercial resources, sourcing reorganization, or an acquisition strategy in 2026, access to that granular intelligence will materially de‑risk execution.
Next step
PW Consulting’s full Agar Market 2026–2032 report contains the detailed tables, sensitivity models, and action templates referenced here. For buyers and leaders who must make decisions in 2026 — particularly those weighing supply‑chain resilience, premium product investments, or strategic acquisitions — the complete model and playbooks provide the necessary level of granularity to translate strategic intent into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Agar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com