

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: BOPA Films Market to Expand at 5.4% CAGR Through 2032

Biaxially Oriented Polyamide (BOPA) Films — 2026 Strategic Briefing
Executive snapshot
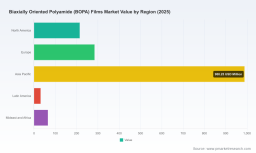
As PW Consulting’s lead industry analyst, I present a concise, decision-focused briefing on the Biaxially Oriented Polyamide (BOPA) films market to orient corporate strategy for 2026. Our assessment draws on a comprehensive base-year review (2025), a five-year historical series (2020–2025) and a forward-looking forecast through 2032. The market expanded from roughly USD 1.23 billion in 2020 to about USD 1.58 billion in 2025 and is projected to grow to approximately USD 2.29 billion by 2032, representing a compound annual growth rate of 5.4% over the forecast period. These macro-dynamics, combined with recent price and feedstock volatility, create a distinctive window for decisive moves in procurement, product positioning, and capacity investment.
Biaxially Oriented Polyamide (BOPA) Films Market
Why this matters for 2026 decision-makers
-
Resilience vs. growth trade-off: BOPA’s steady mid-single-digit CAGR masks divergent trajectories within the value chain. Companies must choose whether to prioritize margin protection (through vertical integration and procurement hedges) or accelerated growth (through specialty offerings and new geographical channels).
Biaxially Oriented Polyamide (BOPA) Films Market -
Price and feedstock volatility: Industry sales volume and effective pricing have shown notable swings recently — global BOPA sales reached about 514.7 kilotons in 2025 with average realized prices that moved higher in early 2026 following raw material cost shifts. Those dynamics make short-term cost visibility and contractual agility critical to protect gross margins in 2026.
Biaxially Oriented Polyamide (BOPA) Films Market -
Regulatory and sustainability inflection points: New environmental rules in the EU and tariff shifts in the U.S. are altering total landed costs, product specifications, and access to markets. Firms that embed regulatory foresight into product development and procurement will avoid reactive margin erosion and lost sales windows.
What the full study equips you to do (high-level)
The full PW Consulting report is purpose-built as a playbook for executives and business units planning capital, commercial, and M&A moves in 2026. Rather than generic market commentary, it synthesizes actionable analytics that translate into clear choices: where to invest, what to de-risk, and how to monetize differentiated performance.
-
Validated market sizing and scenario forecasts (base-year 2025 plus 2026–2032 scenarios) that convert strategic options into revenue and EBITDA implications.
-
Cost-to-serve and plant-level economics models that let you simulate pricing, capacity utilization, and feedstock pass-through under multiple petrochemical-price scenarios.
-
Competitor and capability benchmark tools that map product portfolios, barrier technologies, and route-to-market strengths for leading BOPA producers.
-
Regulatory and procurement playbook: actionable steps for EU sustainability compliance, tariff mitigation in North America, and supplier contracting templates to stabilize supply-cost exposure.
Competitive landscape — what matters in 2026
The sector remains moderately consolidated with room for strategic consolidation: the top three and top five players hold a meaningful but not dominant share, indicating opportunity for focused M&A and capability plays. The competitive field is a mix of specialized technology leaders, regional commodity producers, and vertically integrated suppliers. Strategic positioning in 2026 will largely hinge on a few capabilities:
-
Barrier and aroma control technologies — companies that can maintain or improve barrier performance while meeting environmental targets will command pricing power in food and pharma packaging.
-
Supply-chain verticality — access to feedstock (notably Nylon 6 resin) and the ability to lock long-term supply are central to margin protection. Industry evidence suggests Nylon 6 will represent a dominant share of BOPA feedstock revenue in 2026.
-
Regional manufacturing footprints and trade-aware sourcing — tariff regimes and freight volatility favor multi-hub manufacturing strategies and flexible distribution networks.
Player archetypes and strategic implications
-
Technology-driven incumbents (example archetypes: Unitika, Toyobo, Hyosung): These players lead on high-performance specialty films and benefit from strong IP and application-specific R&D. Strategic emphasis: premiumization, co-development with brand owners, and higher-margin laminated solutions.
-
Sustainable/specialty innovators (example archetypes: Biaxis, Green Seal): Firms focused on sustainable barrier solutions are well positioned for EU regulatory tailwinds. Strategic emphasis: certification, lifecycle messaging, and premium pricing for branded sustainability credentials.
-
Commodity and regional producers (example archetypes: Cangzhou Mingzhu, Xiamen Changsu, FSPG): Competitive on cost and local access, these players must defend volumes through operational efficiency and scale. Strategic emphasis: cost leadership, asset uptime, and selective move into higher-value laminates.
-
Feedstock and integrated suppliers (example archetypes: AdvanSix, Oben Group): Entities with feedstock capabilities or close supplier partnerships can lock margins via backward integration or preferential commercial terms. Strategic emphasis: secure-long term resin contracts, joint ventures for capacity expansion.
Recent dynamics your strategy must internalize
-
Price movement: Early 2026 saw a near-term rise in BOPA film prices driven by raw material volatility. Companies need contract clauses or dynamic pricing mechanisms to avoid margin compression during such spikes.
-
Feedstock concentration: Nylon 6’s predominance in the feedstock mix makes tactical resin sourcing and co-investment with resin suppliers a high-return lever for risk-averse producers.
-
Regulatory friction: Tariff actions in North America have increased landing costs for some Asian-sourced BOPA, while EU environmental policy is accelerating product reformulation toward biodegradability and recyclability. These forces change route-to-market economics and product acceptance thresholds.
Priority strategic moves for 2026 (roadmap)
-
Immediate (0–6 months): Secure feedstock through hedged contracts or strategic alliances; implement dynamic price pass-through clauses with key customers; conduct a rapid margin-at-risk audit to quantify impact of current price trends.
-
Near-term (6–18 months): Shift a portion of product mix toward specialty, sustainable offerings where margins and growth are higher; validate plant upgrades for high-barrier lines; pursue certifications and pilot collaborations with brand owners to capture shelf-space premiums.
-
Medium-term (18–36 months): Execute targeted capacity additions or M&A to acquire complementary barrier technologies or regional distribution hubs; build a resilient multi-regional manufacturing footprint to mitigate tariff and freight exposures.
-
Long-term (36+ months): Invest in circularity (recycling streams, chemically recycled polyamides) and next-generation BOPA chemistries that reconcile biodegradability with barrier performance, positioning the firm ahead of tightening environmental rules.
How to use the full PW Consulting report in boardroom debates
Use the report as a single source of truth when debating capex, pricing, or M&A. It converts market narratives into measurable impacts: revenue trajectories, EBITDA sensitivities to feedstock pricing, and break-even timelines for specialty lines. For sales and commercial teams, it offers differentiated segmentation logic and buyer willingness-to-pay frameworks that can materially lift negotiation outcomes. For operations and procurement, it contains plant-level cost drivers and suggested contract structures to reduce exposure to petrochemical swings.
Methodology and confidence drivers
The analysis rests on proprietary synthesis of primary interviews with producers and brand owners, triangulated trade and shipment data, plant-level economics, and regulatory monitoring. The base year is 2025 and forecasts span 2026–2032. We model multiple price and regulatory scenarios to stress-test outcomes — enabling planners to prioritize moves that pay off across plausible futures rather than a single “most likely” view.
Concluding call to action
2026 is a hinge year: the market is large enough to reward scale and differentiated enough to reward innovation. Executives who combine disciplined procurement, selective premiumization, and regulatory-aligned product development will convert the environment’s turbulence into sustainable advantage. PW Consulting’s full BOPA report provides the segmented analytics, pricing curves, competitor scorecards, and executable templates you need to move from strategy to implementation with confidence. Access the full dataset and the operational playbooks on our report page to unlock the detailed splits and models that are intentionally withheld from this briefing.
For detailed analysis of this topic, please visit the official page: Biaxially Oriented Polyamide (BOPA) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com