

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HFO-1234yf Market to Expand at 16.02% CAGR (2026-2032)

HFO-1234yf Market: Strategic Imperatives for 2026 Decision‑Makers
Executive snapshot
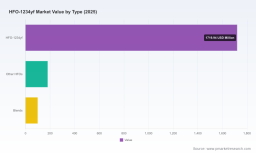
Between 2020 and 2025 the HFO‑1234yf market moved from a niche replacement refrigerant into a commercialized core for automotive and stationary cooling systems. Our base‑year sizing shows the market rose from USD 900 Million in 2020 to USD 2,000 Million in 2025. Under conservative adoption and supply assumptions, the market is projected to expand through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 16.02%, reaching roughly USD 5,660 Million by 2032. These headline numbers capture both the rapid demand pull from regulatory adoption and the persistent price premium driven by production complexity and raw‑material bottlenecks.
HFO-1234yf Market
Why the HFO‑1234yf study matters for 2026 corporate strategy
-
Regulatory inflection points are live: the U.S. EPA’s final SNAP acceptance issued in April 2026 formalizes HFO‑1234yf’s acceptability for motor vehicle air conditioning under defined use conditions. This materially lowers regulatory uncertainty for fleet OEMs and aftermarket service providers but creates a compressed timetable for supply and compliance actions through 2026–2027.
HFO-1234yf Market -
Supplier economics and concentration amplify execution risk: a concentrated supply base coupled with a limited number of integrated producers means pricing and allocation dynamics will be decisive for margin management. Our concentration analysis shows a highly consolidated supplier landscape, which increases strategic importance of sourcing tactics and long‑lead supplier commitments.
HFO-1234yf Market -
Input‑price volatility is a real operating hazard: acid‑grade fluorspar shortages and export curbs have translated into a material cost step‑up for feedstock. The sector has seen feedstock prices rise significantly versus prior years, requiring companies to reconsider procurement windows and inventory policies.
-
Price premium persists versus legacy refrigerants: R‑1234yf commands a multiple of the legacy R‑134a on a per‑pound basis because of production scale, process complexity and compliance handling. That premium will affect vehicle OEM cost‑in‑use calculations, aftermarket pricing and retrofit decisions.
-
Commercial moves are setting the dial for 2026: leading producers have already adjusted commercial terms — including across‑the‑board price increases announced in 2025 — signaling that pass‑through and contractual protections will be a major focus for buyers in 2026.
Report scope — what PW Consulting delivers (practical, decision‑ready outputs)
-
Validated market sizing and trend decomposition (2020–2025 historic base, 2026–2032 forecast) with sensitivity bands tied to adoption, price and regulation scenarios.
-
Scenario models: three investor‑grade cases (Base, Accelerated Adoption, Supply‑Constrained) with model inputs you can edit to stress‑test budgets and capex plans.
-
Commercial playbooks for procurement, contracting and pass‑through mechanisms that protect margins in a high‑volatility commodity environment.
-
Supplier heatmap and strategic assessment (capacity, integration risk, geographic exposure, technological moats) that supports short‑list decisions for qualified suppliers and potential JV partners.
-
Regulatory playbook and compliance checklist tied to U.S., EU and major APAC regulatory vectors, including retrofit guidance under relevant U.S. authorities. This section translates regulatory language into operational steps for 2026.
-
Capex and facility planning guidance for automotive OEMs and refrigerant producers — outlining breakeven volumes, ramp timelines, and recovery economics under multiple price scenarios.
-
M&A and partnership screening tool to identify targets and deal structures that hedge supply risk and accelerate access to compliant product streams.
Competitive landscape — high‑level synthesis
The HFO‑1234yf ecosystem is shaped by a mix of global chemicals leaders, regional producers and distributors. Several firms combine legacy refrigerant portfolios with branded HFO offerings; others are focused producers targeting automotive and industrial adoption. The structural features to watch in 2026 are scale, integrated upstream feedstock access, vertical distribution reach, and the ability to offer blended or service‑based solutions (e.g., reclaim, recovery, retrofit kits).
-
Honeywell International Inc. (Solstice™ YF): A flagship branded play with clear leadership in global production and downstream distribution for automotive air‑conditioning. Honeywell’s April 2025 price adjustments reflect an active commercial posture to preserve margin amid raw material inflation.
-
The Chemours Company (Opteon™ YF): Focused on expanding capacity, including U.S. investments supporting automotive AC supply chains. Chemours’ strategy is to secure regional scale for OEM qualification cycles.
-
A‑Gas International Ltd.: Operating as a strong distributor and supplier, with capability to service aftermarket and commercial refrigeration channels through branded and reseller models.
-
Arkema S.A. (Forane™ blends): Competes with differentiated blended products and a focus on application engineering for vehicular systems where blended refrigerants and tailored service offerings matter.
-
China‑based producers (e.g., Zhejiang Hua’an, Huanxin Fluoro): Expanding production footprints to serve domestic and export demand. Their capacity growth will be an important dynamic for supply continuity and regional pricing pressure.
Collectively, the market exhibits a high degree of concentration among top players — a dynamic that favors sellers in price negotiation windows and elevates strategic value of preferred‑supplier agreements for buyers. For procurement leaders this means supplier selection is as much a strategic decision as a commercial one.
Market dynamics and the hidden levers
-
Regulation: The EPA’s SNAP acceptance (April 2026) reduces regulatory uncertainty but introduces compliance conditions that must be embedded into product spec and after‑sales protocols. Companies that can translate regulatory language into operational checklists win approval cycles faster.
-
Feedstock exposure: Acid‑grade fluorspar supply disruptions and export controls have driven raw‑material inflation. Firms with upstream integration or hedged feedstock contracts will be advantaged in cost stability.
-
Pricing mechanics: The sustained premium of R‑1234yf over R‑134a — driven by production complexity and limited global producers — will continue to influence OEM design choices (e.g., thermal efficiency tradeoffs) and aftermarket pricing strategies.
-
Service and circularity: Recovery, reclaim and lifecycle management for HFO‑1234yf present both regulatory obligations and commercial opportunities to monetize used refrigerant streams.
Actionable strategic playbook for 2026
-
Lock in flexible long‑term supply with indexed price‑adjustment clauses tied to clearly defined feedstock or published indices; combine with short‑cycle spot coverage to manage upside price swings.
-
Accelerate supplier qualification of at least two alternate producers or distributors per strategic region to reduce single‑sourced exposure.
-
Prioritize investment in reclaim and on‑site blending capacity where scale economics support lower total cost of ownership versus buying virgin product at a premium.
-
Build regulatory compliance into product development timelines: fast‑track lab and field validation to meet EPA and regional conditions, avoiding production stoppages or retrofit liabilities.
-
Use commercial levers — premium allocation, tiered contracts, and OEM bundled warranties — to protect margins during periods of supply tightness.
-
For M&A‑active firms: target bolt‑on producers or specialized reclaim players that compress your supply chain and de‑risk feedstock cost exposure.
What we intentionally withhold (and why)
To preserve the strategic value of the full study and to comply with our “trailer” approach, this introduction deliberately omits granular region‑by‑region and application‑level percentage splits, detailed company revenue breakdowns, and ready‑to‑use unit‑price tables. These high‑value, transaction‑grade data points are included in the full PW Consulting HFO‑1234yf Market report package and the downloadable model. If your 2026 decisions require supplier‑level allocations, detailed regional demand curves, or price‑sensitivity runs tied to specific contract structures, the comprehensive datasets and editable models are available through our report page.
Conclusion — the 90‑day decision horizon
For executives and investors making decisions in 2026, the HFO‑1234yf market is not simply about adopting a new refrigerant; it is a supplier and regulatory transformation that will reshape cost structures, after‑sales economics, and supply‑chain architectures. The market’s headline growth (from USD 2,000 Million in 2025 to a projected USD 5,660 Million by 2032 at a 16.02% CAGR) encapsulates opportunity and disruption in equal measure. Short‑term actions — securing flexible supply agreements, accelerating supplier qualification, and embedding regulatory compliance into product and service design — will determine which firms capture the bulk of emerging value. Our full study equips you with the granular datasets, scenario models, and commercial playbooks needed to convert this market trajectory into a defensible 2026 strategy.
For detailed analysis of this topic, please visit the official page: HFO-1234yf Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com