

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Radiopharmaceuticals Market to Hit USD 10.56 Billion by 2032

Radiopharmaceuticals Market 2026: A Strategic Preview for Executive Decision-Making
Between 2020 and 2025 the radiopharmaceuticals market moved from an emerging niche to a commercially material sector—growing from approximately USD 3.5 billion to roughly USD 6.0 billion. Our base year for the full study is 2025, and the forecast horizon extends 2026–2032. Over that forecast period the market is modeled to expand at a compound annual growth rate (CAGR) of about 8.5%, reaching an anticipated total north of USD 10 billion by 2032. That trajectory, combined with a moderate industry concentration (top-three and top-five firms representing meaningful but non‑dominant shares), creates opportunity and complexity for life‑science CEOs, CDMO leaders, investors and hospital systems planning capital allocation in 2026.
Radiopharmaceuticals Market
Why this study matters for 2026 corporate strategy
2026 will be a pivotal planning year. Three convergent forces—accelerating therapeutic innovation, supply‑side capacity constraints for critical isotopes, and shifting public policy on domestic production and trade—will materially influence commercial outcomes over the next three to seven years. Our report translates these forces into actionable intelligence by combining a rigorous market-size baseline (2020–2025), scenario-driven forecasts (2026–2032), and company‑level playbooks. For executive teams, the strategic value is practical: prioritize capital projects and partnerships that preserve launch timetables for novel radiotherapies, mitigate tariff and reimbursement risk, and position supply chains to capture the higher‑margin therapeutic opportunity as it matures.
Radiopharmaceuticals Market
What the numbers tell you (and what we deliberately withhold)
- Macro growth is real and sustained: from ~USD 3.5B in 2020 to ~USD 6.0B in 2025, with a modeled rise toward ~USD 10.56B by 2032 at an 8.5% CAGR for 2026–2032.
- Concentration is meaningful without being prohibitive: incumbent producers and vertically integrated players hold strong positions, yet the market leaves room for CDMOs, specialized isotope suppliers and therapeutic innovators.
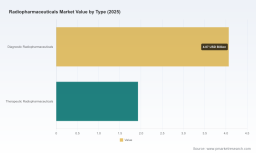
- We intentionally do not publish granular segment shares or regional breakdowns in this preview. Those strategic detail layers—regional and application splits, pricing curves and contract‑level margins—are core deliverables in the full report and are the levers you will need to finalize 2026 capex and M&A decisions.
Competitive landscape: the players you must model into your scenarios
Across the value chain you will find three archetypes: vertically integrated isotope producers and radiopharma originators, specialist contract development and manufacturing organizations (CDMOs), and focused therapeutic developers. The competitive set we model in depth includes established producers and faster-scaling CDMOs, each with different strategic implications:
Radiopharmaceuticals Market
- Telix Pharmaceuticals (Melbourne): expanding GMP capacity in Europe and Asia, with operational manufacturing sites deployed to support commercial diagnostic and therapeutic supply—these assets change supply availability and contract negotiation dynamics in 2026 and beyond.
- ITM Isotope Technologies Munich SE (Garching): a vertically integrated company with leadership in accelerator and isotope production pathways; their portfolio and production posture are a strategic hedge for sponsors seeking assured access to certain therapeutic isotopes.
- Nucleus RadioPharma (Rochester) and Evergreen Theragnostics (Springfield): US‑based full‑service CDMOs offering end‑to‑end development and manufacturing—critical partners for sponsors aiming to accelerate clinical development without investing in in‑house manufacturing.
- PanTera (Mol) and specialized developers such as RayzeBio and Perspective Therapeutics: players focused on advanced alpha and beta emitter precursors and finished therapies—their progress on Ac‑225 and Lu‑177 pathways is a key variable in therapeutic adoption curves.
- Cardinal Health: represents the distribution and logistics layer that becomes increasingly strategic as therapy administration settings diversify and supply‑chain traceability rises in importance.
The full report contains proprietary supplier maps, capability matrices and a five‑node risk scoring model (technical, regulatory, geopolitical, commercial and logistics) for each of these organizations. In the preview we demonstrate posture and momentum—while reserving the contract-level benchmarking and supplier scorecards for report subscribers.
Recent developments shaping tactical choices in 2026
- Facility moves and capacity: Multiple announcements through 2025–2026 indicate an industry in capacity expansion mode—new research and GMP facilities coming online, and permitting progress for dedicated Ac‑225 production. These are inflection points for sponsors needing guaranteed supply windows.
- Technology partnerships for novel isotopes: Collaborative projects to develop next‑generation isotopes (e.g., photonuclear routes, Astatine programs) will determine who secures first-mover advantage in next‑wave alpha therapies.
- Trade and tariff risk: Recent governmental proclamations announced in early 2026 introduce potential ad valorem duties and phased tariff schedules for imported pharmaceuticals and inputs—an operational and P&L risk that must be stress‑tested in 2026 budgeting cycles.
- Regulatory and reimbursement updates: New guidance on oncology radiopharmaceutical dosage optimization and CMS payment adjustments for domestically produced doses change the economic calculus for local manufacturing investments and pricing strategies.
Regulation, reimbursement and the domestic production premium
Two policy changes merit elevated attention. First, payors and regulators are beginning to explicitly reward domestic production—CMS introduced add‑on payments for certain domestically produced study doses and maintained cost‑based methodologies for separately payable diagnostic radiopharmaceuticals. Second, the FDA’s draft guidance on dosage optimization for oncology radiopharmaceuticals signals heightened expectations around clinical development pathways, PK/PD modeling and manufacturing consistency. Together, these changes make a strong case for sponsors to model a 'domestic production premium' in price sensitivity and to prioritize clinical packages that address optimized dosing from Phase II onward.
Supply chain realities and isotope scarcity
Long lead times for new irradiation and processing capacity, coupled with surging demand for isotopes such as Lu‑177 and Ac‑225, create persistent supply risk. The market is not purely demand‑driven: bottlenecks in production scale can impose launch delays, increase unit costs, and shift bargaining power toward suppliers with vertically integrated isotope ecosystems. Our report uses a factory‑level build‑out timeline model and isotope availability scenarios to quantify the expected degree and timing of constrained supply under multiple adoption curves.
What the full PW Consulting report delivers (operationally focused)
- Validated market-sizing and forecast framework: back‑tested against 2020–2025 performance with transparent assumptions for 2026–2032 scenarios.
- Commercial sensitivity analyses: price and reimbursement shock models, tariff stress tests, and domestic vs. import supply-case P&L impacts.
- Supplier and capability maps: audited GMP assets, isotope production capacity timelines, and CDMO lead times—presented with a supplier risk score per node.
- Regulatory impact matrix: mapping new FDA guidance, CMS payment updates and tariff proclamations to clinical development milestones and commercialization costs.
- M&A and partnership heatmaps: targets and rationale for bolt‑on CDMOs, upstream isotope plays, and late‑stage therapy licenses—ranked by strategic fit and time‑to‑value.
- Executive playbook: 12‑month and 36‑month action plans tailored to three archetypes (Sponsor, CDMO, Distributor) with decision triggers and investment thresholds.
Immediate strategic recommendations for 2026 planning
- Model tariff and reimbursement sensitivity into every scenario. Build worst‑case duty and delayed‑launch assumptions into capex and licensing schedules to avoid negative surprises.
- Secure multi‑tiered supply agreements with clear force‑majeure and capacity allocation clauses. Given isotope scarcity, prioritize contractual certainty over marginal price concessions.
- Prioritize modular, scalable manufacturing investments (e.g., cleanrooms and cyclotron capacity) that accelerate time‑to‑clinic while limiting stranded asset risk.
- Use the FDA draft guidance to pre‑emptively refine dosing strategies; better early optimization reduces costly late‑stage rework and supports stronger reimbursement positioning.
- Assess opportunistic M&A: target CDMOs with validated GMP track records or niche isotope producers with near‑term capacity declarations to shorten supply risk horizons.
How to use this preview
This article is a strategic primer: it surfaces the macro trajectory and the practical forces executives must factor into 2026 decisions, while preserving the granular, supplier‑level intelligence that drives transactional moves. If your 2026 plan includes capital projects, manufacturing partnerships, or late‑stage licensing in radiopharmaceuticals, the full PW Consulting study supplies the regionally and segment‑specific data, supplier scorecards, and contract‑level margin benchmarking you will need to finalize commitments.
In an industry where isotope availability, regulatory nuance and policy shifts can compress or extend commercial runways overnight, decision makers who blend scenario discipline with supplier certainty will win. Our research is designed to move your strategy from assumptions to defensible decisions—fast.
For detailed analysis of this topic, please visit the official page: Radiopharmaceuticals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com