

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 1,3-Butylene Glycol Market to Reach USD 321.7M by 2032 at 5.9% CAGR

1,3-Butylene Glycol (CAS 107-88-0): Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a focused, decision-oriented preview of our 1,3-butylene glycol market study (base year 2025). The global market has evolved from roughly USD 163 million in 2020 to about USD 212.5 million in 2025, and our modelling projects a confident ascent to more than USD 320 million by 2032 under a compound annual growth rate (CAGR) of approximately 5.9% through the 2026–2032 forecast window. This preview distills actionable implications for strategy teams, corporate development groups, and procurement leaders considering investments, partnerships, or portfolio repositioning in 2026 — while deliberately withholding the granular subsegment tables and regional splits reserved for the full report.
1,3-butylene Glycol (CAS 107-88-0) Market
Why this study matters for 2026
-
Timing: 2026 sits at the inflection between post-pandemic normalization and the next phase of value-chain consolidation. Buyers and sellers will make multi-year commitments this year; accurate midpoint forecasts and risk maps are therefore mission-critical.
1,3-butylene Glycol (CAS 107-88-0) Market -
Scale vs. Specialization: The market’s projected mid-term expansion creates both volume-driven opportunities and premium niches (e.g., bio-derived and pharmaceutical grades) that command differentiated margin dynamics. Our study quantifies these trade-offs and models likely margin impacts under multiple demand scenarios.
1,3-butylene Glycol (CAS 107-88-0) Market -
Regulatory and sustainability thresholds: Certification regimes and regulatory compliance (regional registration frameworks and voluntary ‘clean’ labeling programs) are reshaping procurement specifications and supplier eligibility. The 2026 procurement cycle will reflect these elevated non-price criteria more sharply than previous years.
What the macro picture tells us
The market’s historical trajectory and forecast envelope reveal several high-level truths. After moderate volatility in the early-2020s, the market recovered, with overall revenue moving from the low hundreds of millions (USD) in 2020 to above USD 200 million in 2025. From 2026 onward, the industry demonstrates steady, above-average growth relative to many commodity intermediates, driven by expanding personal care formulations, food-contact applications under stricter safety expectations, and industrial uses that benefit from enhanced supply security.
Importantly, the projected CAGR of about 5.9% across the forecast period reflects a composite of steady baseline demand plus episodic upside from regulatory-driven substitution and bio-based adoption. For executives sizing capacity or evaluating M&A targets, this growth rate is not a signal to expand indiscriminately; rather, it demands calibrated investment that differentiates on feedstock flexibility, certification capabilities, and channel intimacy.
Market dynamics and operational levers
-
Feedstock and route diversification: Two primary production pathways — bio-based fermentation (notably sugarcane-derived routes) and synthetic routes based on petrochemical feedstocks (e.g., butadiene derivatives) — create distinct cost and risk profiles. Supply volatility in hydrocarbon feedstocks can compress margins for synthetic producers, while bio-based routes introduce agricultural exposure (crop yields, sugar pricing) and logistics considerations. Successful players are those who build optionality across routes or secure long-term feedstock arrangements.
-
Regulatory and label-driven demand: Certification frameworks for natural and safer-ingredient claims (e.g., COSMOS, NATRUE, and voluntary labeling schemes recognized by authorities) are accelerating adoption of bio-derived grades in cosmetics and personal care. Simultaneously, regional chemical registration regimes impose compliance costs that influence sourcing strategies — particularly for cross-border suppliers.
-
Concentration and supplier power: The supplier landscape is skewed toward a limited set of capable manufacturers and well-positioned distributors. This structure confers bargaining power to those with scale, proprietary production know-how, or specialized quality certifications. Strategic buyers should expect contracting to favor multi-year frameworks with performance and sustainability clauses rather than spot-only procurement.
-
Certification as a commercial moat: Compliance and certification are increasingly translatable into pricing power. Producers that can demonstrate traceable bio-origin, achieve recognized ‘natural’ seals, or secure high-purity pharmacopeial grades command preferential access to premium channels.
Competitive landscape: who to watch
The competitive set combines global chemical majors, regional producers, and specialized biorefineries. Key players with material strategic relevance include:
-
OXEA GmbH (Oberhausen, Germany) — A well-established supplier offering both industrial and cosmetic grades. OXEA’s integrated supply chains and customer relationships in personal care make it a go-to for formula developers requiring consistency.
-
Daicel Corporation (Osaka, Japan) — Operates at scale with both bio-based and synthetic production routes; recent corporate reviews indicate the company is aligning 1,3-BG activity with broader sustainability and portfolio-efficiency goals.
-
Godavari Biorefineries Ltd. (Hyderabad, India) — A notable bio-derived supplier, leveraging sugarcane fermentation under dedicated branding. Recent throughput optimization efforts highlight the company’s operational focus on meeting certification-driven demand.
-
Penta Manufacturing Company (New York, US) — Offers regulatory-grade variants and focuses on pharmaceutical-intermediate and food-grade applications, an important niche when end-use compliance is a gating factor.
-
Specialist distributors (MMP Inc., Whyte Chemicals, Rita Corporation) — These firms play a critical role in channeling high-purity and compliant product streams into regulated markets, enabling smaller formulators to access certified material without direct manufacturer contracts.
-
Regional producers (Shanghai Jinjin, KH Neochem) — Address localized demand and export flows, especially in high-growth markets across Asia, with competitive cost profiles and tailored grades.
Recent corporate developments reinforce strategic themes for 2026. For example, a 2026 business plan review by a major Japanese manufacturer signals portfolio prioritization and potential rebalancing of capacity allocations. Additionally, announced capacity debottlenecking by a bio-based supplier underscores the near-term supply response to certification-led demand. These moves foreshadow a market where operational execution and certification readiness will define winners.
What’s inside the full PW Consulting report (practical content)
-
Methodology and transparent assumptions — including demand-driver modeling, price-sensitivity scenarios, and feedstock price pass-through mechanisms.
-
Bottom-up market sizing (historical 2020–2025 and forecast 2026–2032) with sensitivity bands and scenario overlays that stress-test demand under varying regulatory and raw-material environments.
-
Commercial diligence modules — supplier scorecards, certification readiness assessments, contract archetypes, and a supplier risk heatmap suitable for procurement negotiations.
-
Go-to-market playbooks for entrants and incumbents — tailored to scale players, bio-based challengers, and distributors aiming to expand into regulated channels.
-
M&A and partnership screening — a prioritized shortlist of target profiles, valuation heuristics, and a roadmap for integration of quality systems and certification pipelines.
-
Operational playbooks — detailed capex/opex scenarios for debottlenecking, capacity additions, and co-location strategies with feedstock suppliers.
Strategic recommendations for 2026
-
Map demand by specification, not by broad application buckets. Procurement and commercial functions must identify which customers require certified bio-origin or pharmacopeial grades and prioritize those relationships for premium allocation.
-
Pursue feedstock optionality. Contracts and co-investments that enable switching between synthetic and bio-based routes (or hedging feedstock exposure) will materially reduce margin volatility.
-
Capitalize on certification as a differentiator. Invest selectively in third-party certification and traceability systems; their commercial payback is accelerated when linked to long-term offtake agreements.
-
Design contracts with embedded sustainability and compliance KPIs. Buyers and suppliers should codify testing frequencies, chain-of-custody requirements, and penalty/bonus structures to align incentives.
-
Use phased capacity plays. Where demand visibility is limited, favor modular debottlenecking and tolling arrangements over greenfield commitments to protect balance sheet flexibility.
Limitations of this preview and next steps
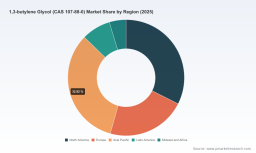
This preview intentionally omits the granular geographic and application splits, proprietary price series, and the detailed company-level revenue estimates that form the core of the full intelligence package. Those subsegment tables and supplier scoring matrices are essential for transaction diligence, detailed sourcing tender design, and regionally differentiated pricing strategies — and they are included exclusively in the full PW Consulting report.
For 2026 planning cycles, executives should use this analysis to align strategic priorities, while commissioning the full report to obtain the granular inputs required for contracting, capex approval, and commercial negotiations. PW Consulting can provide tailored workshops to translate the report’s scenarios into board-ready investment cases and procurement RFx templates.
Contact PW Consulting to access the full study and the proprietary dataset that underpins our forecasts, scenario models, and supplier risk assessments. The decision window in 2026 rewards those who combine rigorous macro foresight with granular, execution-ready intelligence — that is the core value PW Consulting delivers.
For detailed analysis of this topic, please visit the official page: 1,3-butylene Glycol (CAS 107-88-0) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com