

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PEEK Market to Grow at 6.3% CAGR Through 2032 — PW Consulting

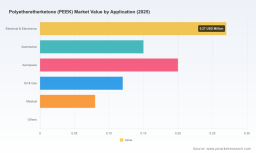
PEEK Market Outlook 2026: Strategic Imperatives for Industrial Decision‑Makers
As PW Consulting’s senior strategic advisor and industry analyst, I present an executive introduction to our latest Polyetheretherketone (PEEK) Market study — a decision‑grade briefing designed to inform capital allocation, product strategy, supply‑chain design and M&A activity throughout 2026. The study is built on a 2020–2025 historical baseline (base year 2025) and a 2026–2032 forecast horizon. At the macro level, the global PEEK market is growing at a mid‑single‑digit compound annual growth rate (6.3% CAGR) and is projected to progress from its 2025 base toward a markedly larger market by 2032. This briefing highlights the strategic value of the full research while intentionally withholding the granular segment tables and region/application splits that form the core competitive intelligence in order to guide readers to the complete report.
Polyetheretherketone (PEEK) Market
Why this research matters in 2026
-
Strategic clarity for capital allocation — The PEEK value chain is capital‑intensive. Understanding the trajectory of the overall market and the technological inflection points (e.g., lower‑melting PAEK variants, additive manufacturing readiness) is essential for disciplined CAPEX and facility siting decisions.
Polyetheretherketone (PEEK) Market -
Supply‑chain risk mitigation — Volatility in key precursors and the growing advantage of vertically integrated producers require procurement strategies that balance security, cost and agility.
Polyetheretherketone (PEEK) Market -
Commercial and qualification roadmaps — Aerospace and medical buyers remain the longest lead markets for PEEK qualification. Suppliers and OEMs must prioritize product‑qualification pathways and partner ecosystems to accelerate adoption.
-
M&A and partnership targeting — The market is concentrated among a few global leaders, but rapid regional capacity expansions and new technology entrants create attractive bolt‑on and cross‑border partnership opportunities.
What the full report delivers (operationally focused)
-
Trusted market sizing and 2026–2032 forecasts with scenario modelling calibrated to current adoption patterns, technology diffusion and raw‑material stress tests.
-
Demand driver analysis: application‑level growth levers, unit economics for replacement metals/composites, and procurement cadence for aerospace, medical, electrical & electronics, automotive and energy segments.
-
Supply‑side intelligence: global capacity maps, recent expansions, contract manufacturers and compounding specialists; sensitivity to feedstock bottlenecks (notably 4,4'‑DFBP) and inventory buffer strategies for 2026.
-
Technology & product playbook: grade maps, processing envelopes, additive manufacturing readiness, and the practical implications of new lower‑melting PAEK/PEEK variants for conventional processing lines.
-
Competitive benchmarking: profile scorecards, capacity positioning, go‑to‑market models and supplier strengths/weaknesses — actionable for commercial sourcing and M&A diligence.
-
Regulatory and ESG checklist: material declarations (including PFAS status), biocompatibility pathways, and region‑specific certification requirements.
-
Commercial templates: sample qualification roadmaps, long‑term purchase agreement (LTPA) clauses, and price‑indexing structures tied to precursor feedstock indices.
Market dynamics to watch in 2026
-
Structural growth with technology inflection: PEEK remains a high‑performance polymer whose adoption trajectory is powered by structural lightweighting, higher operating temperatures, and harsher service environments. The study’s historical trends and forecasting envelope — anchored to a 6.3% CAGR — show steady expansion rather than explosive substitution, meaning tactical moves now yield compound benefits through 2032.
-
Processing innovation reduces adoption friction: New lower‑melting PAEK/PEEK variants widen processing windows and reduce energy and cycle cost for conventional manufacturing systems. These material advancements materially lower the technical barrier for broader use in complex assemblies and are already influencing supplier roadmaps.
-
Feedstock and integration premium: Security of supply for critical precursors (e.g., 4,4'‑DFBP) favors vertically integrated producers or those with long‑term off‑takers. Procurement teams should model scenarios where feedstock tightness imposes stepped cost increases and where vertical integration creates differentiated margin profiles.
-
Regional capacity migration and scale: Capacity expansions in Asia are lowering delivered cost and shortening lead times for regional OEMs. Market entrants from China are enlarging global tonnage and changing price dynamics for non‑qualified commodity channels; incumbents remain competitive where qualification and regulatory credentials are prerequisites.
-
Regulatory and sustainability positioning: PEEK’s PFAS‑free manufacturing profile is an emerging commercial advantage in regulated end markets. Buyers and specifiers increasingly shortlist materials that facilitate compliance and minimize downstream risk.
Competitive landscape — positioning and strategic implications
-
Victrex plc — The global reference for performance PEEK and related PAEK solutions. Recent product introductions (notably lower‑melting PAEK variants) and partnerships with additive‑manufacturing specialists strengthen Victrex’s position on both performance and manufacturability fronts. Their technology roadmap and award‑winning composite applications make them the primary strategic partner for aerospace programs seeking thermoplastic architectures.
-
Solvay S.A. — A technology‑led supplier with high‑temperature grades and recent launches tailored for medical implants. Solvay’s emphasis on specialized grades and biocompatibility keeps it competitive in regulated medical and aerospace niches where certification and performance at extreme temperatures are differentiators.
-
Evonik Industries AG — A supplier‑to‑industry offering compounded and specialty PEEK formulations with an increasingly Asia‑focused compounding footprint. Evonik’s strategy is to pair material breadth with localized value‑added services for medical and industrial customers.
-
Arkema S.A. — Competes via complementary high‑performance aromatic ketone polymers (PAEK family) and advanced feedstocks suitable for 3D printing and extreme‑environment applications. Arkema’s route targets markets where alternate PAEK chemistries deliver system advantages.
-
Chinese producers (e.g., Jilin Joinature, Junhua) — Scaling medical‑grade and filled PEEK portfolios with aggressive capacity expansions and global distribution partnerships. Their emergence compresses lead times and cost structures in regional markets while driving new qualification cycles among cost‑sensitive OEMs.
-
Specialists and converters (e.g., RTP Company, Ensinger GmbH) — Critical to downstream adoption: compounding houses and semi‑finished goods suppliers translate polymer grades into application‑ready forms. These firms are acquisition targets for players seeking to move downstream into higher margin, application‑specific services.
-
Market concentration — While the PEEK market exhibits consolidation among a handful of global leaders, expanding regional capacity and compounding specialists create pockets of competitive pressure. The top tier controls a substantial share of qualifying business, making supplier selection a strategic decision rather than a purely transactional one.
Practical strategic recommendations for 2026
-
For producers: Prioritize feedstock resilience. Consider vertical integration, strategic offtakes, or inventory strategies that de‑risk precursor supply and protect margins during price cycles.
-
For buyers/OEMs: Shortlist suppliers by certification depth and processing support, not just price. Allocate resources to qualification where lifetime cost and performance matter (aerospace, medical).
-
For investors and M&A teams: Focus on compounding, semi‑finished goods producers and regional capacity platforms that provide immediate access to qualified channels and proprietary processing expertise.
-
For technology teams: Evaluate lower‑melting PAEK/PEEK grades and additive manufacturing partnerships to shorten time‑to‑part and reduce total cost of ownership for complex geometries.
-
For procurement: Build multi‑tiered sourcing strategies that combine global leaders for critical, certified supply and regional converters for speed‑to‑market; include robust indexation and flexibility clauses tied to feedstock indices.
How to use the full PW Consulting PEEK report
The full report contains the granular segment economics, supplier scorecards, capacity maps, pricing corridors, and application‑level adoption curves that materially change execution choices made in 2026. It also includes downloadable commercial templates and a prioritized action matrix tailored for suppliers, OEMs and investors. Because the most sensitive competitive intelligence is core to our subscription offering, this introduction purposefully omits the detailed splits and numeric tables that underpin supplier selection and deal structuring.
If your 2026 agenda includes manufacturing investments, qualification roadmaps for high‑value applications, supply‑contract renegotiations, or M&A scouting, the full PW Consulting PEEK Market study converts market noise into a prioritized, time‑phased plan. Our clients use this research to shorten decision cycles, calibrate downside protections and identify the exact capability gaps to close before RFPs or deal execution.
Concluding perspective
PEEK is not a mass‑market polymer; it is a performance story where technology, supply security and regulatory alignment determine winners. The market’s medium‑term outlook is constructive and compounding — not explosive — which rewards thoughtful, preemptive strategies in 2026. Suppliers that secure feedstock, embrace processing innovations and move selectively downstream will convert steady market growth into outsized commercial returns. Buyers that align sourcing with qualification priorities and manufacturing partners will reduce program risk and compress time‑to‑market.
For a data‑driven playbook, supplier scorecards and the complete set of forecasts and scenarios that inform executable 2026 strategies, access the full PW Consulting PEEK Market report on our website or contact our research team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Polyetheretherketone (PEEK) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com