

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Precipitated Barium Sulfate Market to Reach USD 583.94 Million by 2032 at 4.16% CAGR

Precipitated Barium Sulfate Market: Strategic Briefing for 2026 Decision-Making
Executive snapshot
As companies prepare strategies for 2026, the precipitated barium sulfate (PBS) market presents a stable, moderately growing opportunity set that rewards supply-chain sophistication, product differentiation, and timely capital deployment. Our proprietary model shows the global PBS market rising from a base-year value of USD 437.4 Million (2025) to roughly USD 584.0 Million by 2032 — a compound annual growth rate (CAGR) of approximately 4.16% across the 2026–2032 forecast horizon. Historical growth has been steady: the market expanded from roughly USD 356 Million in 2020 to USD 437 Million in 2025, reflecting both end-market recovery cycles and incremental substitution into higher-performance grades.
Precipitated Barium Sulfate Market
Why this briefing matters for 2026
-
Time window: 2026 is the inflection point where near-term cost pressures and longer-term structural demand (specialty grades, performance coatings, and polymer fillers) converge. Decisions on contract lengths, capacity additions, and product investments made in 2026 will see payback across the 2026–2032 forecast period.
Precipitated Barium Sulfate Market -
Margin sensitivity: Recent raw-material and logistics shocks have compressed margins for upstream producers and created pass-through opportunities for agile players. Understanding the volatility vectors now reduces execution risk for pricing and procurement moves next year.
Precipitated Barium Sulfate Market -
Competitive positioning: Market concentration is meaningful but not prohibitive — the three largest players control under half the market and the top five roughly half. This structure rewards targeted differentiation, regional supply strategies, and M&A consolidation in white space segments.
Market dynamics shaping strategy
-
Cost and supply shocks: Freight inflation and container shortages have increased delivered costs for mineral feedstocks in import-dependent corridors. Simultaneously, rising antimony and other critical input costs have placed upward pressure on producer margins. Multiple suppliers announced price increases in late 2024 and through 2025 to close these gaps; these moves materially changed contract benchmark expectations.
-
Capacity tuning: Producers in Europe and Asia have reacted heterogeneously — some expanding capacity for specialty/ultra-pure grades, others rationalizing commodity lines. A notable European expansion added meaningful incremental tonnes in 2024, while Asian manufacturers continue to scale for regional demand. These capacity shifts create localized price differentials and create arbitrage for flexible traders.
-
Product-grade bifurcation: Demand is increasingly bifurcated between commodity-grade PBS used as a cost-effective filler and higher-value modified and nano-grade products required by advanced coatings, specialty plastics, and performance rubber. Firms that can move up the value chain — via particle engineering, surface treatment, or formulation partnerships — capture materially higher margins.
-
Regulatory and sustainability pressure: Environmental regulation on process effluents, worker safety, and supply-traceability are forcing incremental compliance costs, particularly for powder manufacturing. Buyers with stringent ESG procurement policies will favor suppliers able to demonstrate low-impact production and documented supply chains.
Competitive landscape: what leading players signal
Company strategies offer a clear map of where the market is heading:
-
Cimbar Performance Minerals (Chatsworth, GA, USA) — a leading North American producer — has signaled a pricing stance to protect margins and is focused on applications in paints, coatings, plastics, printing inks, and lead-acid batteries. Their actions illustrate how scale and application diversification enable pricing discipline across cycles.
-
Nippon Chemical Industrial Co., Ltd. (Tokyo, Japan) — with emphasis on high-purity PBS — represents the technology-led route: investing in consistent quality and application-specific grades to command premium positioning in industrial niches.
-
Shanghai Tengmin Industry Co., Ltd. (Shanghai, China) — positioned as a primary filler supplier for paints, coatings, and pigments — underscores the role of cost-competitive, high-volume supply into regional coatings value chains.
-
Hubei Qinba Advanced Materials Co., Ltd. (Hubei Province, China) — specializing in synthetic PBS for high-performance powder coatings — highlights the growing importance of tailored chemistry and process control for premium coatings markets.
Recent events (price increases announced by major suppliers in March 2025 and earlier strategic pricing moves by Cimbar) and capacity moves (a European producer’s expansion in 2024) are already re-setting negotiated pricing frameworks and supply expectations for 2026 procurement cycles.
How the full report adds operational value
The PW Consulting study is structured to convert market insight into executable decisions. Key, practitioner-oriented deliverables included in the full report:
-
A validated market-sizing model (base year 2025; historical 2020–2025; forecast 2026–2032; currency USD Million) with scenario toggles to stress-test volume and price outcomes under alternative macro and raw-material assumptions.
-
Supply-side mapping and capacity tracker, with facility-level intelligence, lead times, and planned expansions/closures to inform sourcing and contingency planning.
-
Price-driver analysis that quantifies the impact of freight, antimony and other input-cost swings on landed cost curves and enables procurement teams to build dynamic pass-through clauses into supplier contracts.
-
Competitive benchmarking and capability matrices for the major suppliers, including product-grade footprints, geographic reach, and go-to-market models — enough to prioritize vendor sessions without revealing customer-sensitive volumes.
-
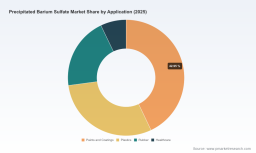
Application-focused demand diagnostics (paints & coatings, plastics, rubber, healthcare, and others) that translate end-use trends into near-term specification shifts and acceptance thresholds for modified and nano-grade PBS.
-
Commercial playbook: negotiation levers, contract templates, hedging approaches for raw materials, and pricing cadence recommendations to lock in margins or capture upside in inflationary periods.
-
Strategic options matrix for M&A, JV, and greenfield capacity choices targeted at stakeholders evaluating capital deployment between 2026 and 2028.
Strategic implications and recommended actions for 2026
-
Procurement: Shift from annual spot-centric buys to blended contracting (short-term indexation + medium-term fixed volumes). Use the report’s price-driver sensitivity to size collars and pass-through mechanisms that limit downside while retaining upside participation.
-
Operations & CapEx: Prioritize incremental investments in particle-engineering capabilities (surface-modification and nano-fabrication) over raw tonnage additions. Higher-value grades deliver better returns given the market’s mid-single-digit CAGR and the premium available for performance differentiation.
-
Commercial: Segment customers by value-to-manufacturer; offer tiered service models (technical co-development, guaranteed quality lanes, logistics-managed programs) to protect margins as commodity supply tightens.
-
Supply-chain resilience: Map single-source risks, especially in import-reliant corridors where freight inflation is acute. Consider nearshoring options, multi-supplier contracts, and working-capital optimizations to mitigate delivery disruptions.
-
M&A and partnerships: With the market moderately consolidated but fragmented across regions and grades, bolt-on acquisitions or JVs in specialty grades or underserved geographies remain attractive, particularly where production technology or customer relationships can be acquired cheaply.
-
R&D and sustainability: Invest in lower-impact process chemistries and traceability systems now — ESG-compliant suppliers are gaining preferential access to sophisticated OEMs, and regulatory compliance costs are likely to rise.
Decision-making toolkit included in the report
To move from insight to action, the full PW Consulting deliverable includes:
-
Interactive financial models that allow CFOs and strategy teams to test capex and pricing scenarios against the 4.16% CAGR baseline and alternative growth paths.
-
Negotiation-ready supplier scorecards and a phased supplier-onboarding checklist for technical qualification and ESG audits.
-
Three strategic playbooks (Cost Leadership, Differentiation through Grade Innovation, and Regional Consolidator) with step-by-step milestone plans for 12–36 months.
Protecting the signal — what we do not show here
In this briefing we intentionally present high-value insights and strategic direction while withholding granular segment-level allocations, exact regional splits, and confidential unit-price schedules. Those core sub-segment datapoints and supplier-level commercial metrics are included in the complete report and the interactive models — they are the actionable inputs buyers, investors, and suppliers need to finalize 2026 contracts and capex approvals.
Next steps for executives
-
Procurement leads: use the report’s price-driver module to set 2026 sourcing strategy workshops and to renegotiate expirations in Q1 2026.
-
Business development and R&D: prioritize three pilot projects for grade-up initiatives with select customers to capture premium mix before competitors scale.
-
Corporate strategy and M&A teams: request the target-screening appendix to identify acquisition prospects compatible with mid-single-digit market growth and fragmentation dynamics.
Conclusion & how to obtain the full intelligence
The precipitated barium sulfate market in 2026 sits at the intersection of cost volatility and measured demand growth. With a transparent baseline (USD 437.4 Million in 2025; market set to reach ~USD 584.0 Million by 2032 at a ~4.16% CAGR), firms can craft defensible strategies that balance margin protection with selective investments in higher-margin specialty grades. PW Consulting’s full report converts this macro-view into transaction-ready intelligence: supply maps, price-driver sensitivities, supplier scorecards, and commercial playbooks tailored for 2026 execution.
For access to the detailed segment matrices, supplier-level commercial metrics, and the interactive forecasting model needed to finalize 2026 decisions, visit our report page or contact PW Consulting to license the complete Precipitated Barium Sulfate Market study.
For detailed analysis of this topic, please visit the official page: Precipitated Barium Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com