

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vaginal Pessary Market Poised for 6.5% CAGR Through 2032

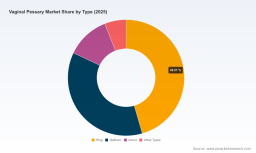
Vaginal Pessary Market: Strategic Preview for 2026 Decision-Making
Between 2020 and 2025 the global vaginal pessary market moved from a modest specialized therapy niche into a resilient, clinically entrenched modality with clear commercial expansion. Our PW Consulting baseline (2025 as base year) places the market at roughly USD 320 Million, and our forecast models project a sustained compound annual growth rate (CAGR) of about 6.5% over the 2026–2032 horizon—placing the market well above current mid‑cycle expectations by 2032. This preview summarizes the strategic implications we expect to matter most to executive teams in 2026, highlights the competitive moves reshaping access and adoption, and outlines the operational playbooks that will translate market growth into durable commercial advantage.
Vaginal Pessary Market
Why this research matters for 2026 strategic planning
-
Timing: 2026 is the inflection point where clinical acceptance, regulatory clarity, and commercialization innovation converge—creating windows for product repositioning, reimbursement negotiation, and channel expansion.
Vaginal Pessary Market -
Risk-managed growth: With a predictable mid-single-digit CAGR, leaders must convert macro growth into defensible revenue and margin expansion through product differentiation, pricing strategy, and supply-chain resilience rather than mere volume plays.
Vaginal Pessary Market -
Portfolio decisions: The market supports both legacy reusable devices and emerging disposable/at‑home formats; choosing which to prioritize determines CAPEX, clinical evidence investments, and go‑to‑market partnerships.
-
M&A and partnerships: Moderate concentration (CR3 ~52%, CR5 ~65%) indicates room for bolt‑on acquisitions and strategic alliances to consolidate specialty distribution and close capability gaps in commercialization and regulatory pathways.
Market at a glance (strategic highlights)
-
Trajectory: The market expanded steadily through 2020–2025 and is projected to continue growing through 2032 on the back of non‑surgical treatment demand, aging populations in developed markets, and improved device usability.
-
Scale: Our 2025 baseline of approximately USD 320 Million provides the starting point for 2026 planning; forecast topology indicates acceleration into the latter part of the decade as new product forms reach scale and payer pathways mature.
-
Concentration: Market concentration metrics demonstrate that while a handful of players command meaningful share, the competitive landscape remains accessible for focused challengers and specialized offerings targeting specific clinical or commercial segments.
What the full report delivers (practical, operational modules)
-
Market sizing and methodology: Transparent base‑case and sensitivity scenarios with step‑by‑step assumptions—enabling teams to adapt the model to internal forecasts.
-
Commercial playbooks: Supplier negotiation templates, channel mix optimization tools, and clinic/hospital adoption roadmaps for both reusable and disposable formats.
-
Reimbursement and coding playbook: Actionable guidance on leveraging existing HCPCS and CPT codes in payer negotiations, including counseling on differential reimbursement pathways and documentation requirements.
-
Regulatory pathway matrix: 510(k) strategy templates, common predicate mapping, and GMP readiness checklists to compress time‑to‑market while limiting regulatory risk.
-
Competitive benchmarking: Profiles, capability heatmaps and white‑space analysis for incumbent and emerging manufacturers—aligned to commercialization, IP, product breadth, and supply capacity.
-
Clinical and adoption evidence plan: Tiered evidence strategies (from pragmatic real‑world studies to randomized trials) prioritized by ROI and payer influence.
-
Go‑to‑market toolkits: Sales training modules, point‑of‑care decision aids, and patient support program drafts to accelerate clinician uptake and patient self‑management.
-
M&A/partnership screen: Thermometer scoring for targets (manufacturing scale, IP, distribution, regulatory clearance) and a two‑year integration roadmap template.
Competitive landscape—profiles and strategic implications
-
CooperSurgical (Connecticut, USA) : A global manufacturer and distributor with a broad portfolio and clinic penetration. Strengths include established brand recognition, range of pessary styles, and entrenched relationships in gynecologic practice. Strategic implication: incumbency advantage in channel access; challengers must offset with either superior economics (disposable at‑home convenience) or focused clinical evidence by indication.
-
MedGyn Products (Illinois, USA) : Known for comprehensive fitting sets and clinician‑oriented tools for diagnosis and short‑term management. Strategic implication: plays to clinician workflow; partnerships that expand fitting efficiency or telehealth integration can increase adoption.
-
Bioteque America (USA) : Focus on silicone offerings and device diversity. Strategic implication: differentiation through materials and durability claims requires supporting safety and lifecycle data to justify premium pricing.
-
Panpac Medical (Canada) : Offers disposable and flexi‑shelf options with regulatory clearances. Strategic implication: success in bridging single‑use convenience with clinical acceptance provides a model for rapid scale in outpatient settings.
-
Cetro Medical (Israel) and Thomas Medical (Indiana, USA) : Focused manufacturers of specific device types with regional footholds. Strategic implication: attractive targets for distribution partnerships or bolt‑on acquisitions to accelerate geographic reach.
-
ConTIPI Medical (Israel) : Recent U.S. commercial launch of a disposable at‑home ring pessary (ProVate) and a commercialization partnership enhances the appeal of patient‑centric models. Strategic implication: validates at‑home insertion as a credible product pathway; incumbents should assess defensive options (e.g., licensing, co‑promotion) or accelerate their own consumer‑facing programs.
-
Bray Group (UK) : Focus on cost‑efficient PVC ring devices with deep UK/EU clinician relationships. Strategic implication: low‑cost local manufacturing models remain relevant in cost‑sensitive procurement environments.
Dynamics shaping 2026 strategies
-
Reimbursement mechanics: HCPCS coding differentiators are material—codes for non‑rubber (silicone) devices tend to command higher reimbursement and present a lower allergy risk profile. Clinical and billing teams must document material and device lifecycle claims to optimize reimbursement capture.
-
Provider reimbursements for fitting: Fitting and insertion are commonly billed under established CPT codes, often during annual exams; contractual alignment and clear documentation are therefore necessary to avoid revenue leakage.
-
Material economics and lifecycle: PVC remains the cost leader for clinic stock due to low raw material cost and familiarity, while silicone supports reusable lifecycle claims (defined wash and reuse cycles). Procurement teams should model total cost of ownership over device life rather than unit price alone.
-
Regulatory environment: Vaginal pessaries are regulated as Class II devices requiring 510(k) for the U.S. market. Efficient predicate mapping and robust design controls are preconditions for a predictable pathway to clearance.
-
Recent product and regulatory events: 2024–2025 has seen multiple 510(k) clearances and commercial launches, and commercialization partnerships that accelerate adoption of novel formats. These events compress the window for late entrants and increase pressure on incumbents to demonstrate differentiated clinical and economic value.
Actionable strategic pathways for 2026
-
For market leaders: Defend clinical share by investing in clinician training, expanding product breadth to include disposable/at‑home formats, and locking in payer relationships that recognize device and fitting value. Use M&A to fill capability gaps (e.g., digital patient support, single‑use manufacturing).
-
For challengers: Prioritize rapid evidence generation for differentiated use‑cases (e.g., at‑home insertion, reduced clinic burden), secure targeted distribution partnerships, and price to capture early adoption while protecting margin through supply chain efficiency.
-
For new entrants and investors: Focus on narrow use‑case wins (e.g., stress urinary incontinence adjuncts, specific patient cohorts) that can be commercialized with lean evidence packages and partner‑led distribution to limit upfront commercial cost.
-
Operational priorities: standardize supplier qualification, embed reimbursement specialists in launch teams, and align clinical affairs with market access to accelerate payer conversations post‑clearance.
Conclusion — what to do next
For teams making 2026 decisions, the question is not whether the vaginal pessary market will grow—it will—but how to convert that growth into sustainable, defensible revenue and improved patient outcomes. The levers are clear: product form factor, reimbursement positioning, evidence strategy, and channel architecture. Our full PW Consulting report provides the granular segmentation, region‑level forecasts, pricing ladders, and downloadable commercial templates that enable stitchable, board‑ready plans. This preview highlights the strategic contours; the detailed data and ready‑to‑use tools are available through our full market report to support investment decisions, M&A screening, and launch execution in 2026.
For detailed analysis of this topic, please visit the official page: Vaginal Pessary Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com