

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LNG Tank Container Market Poised for 7.5% CAGR Through 2032

LNG Tank Container Market: Strategic Imperatives for 2026 Decision-Makers
Executive snapshot
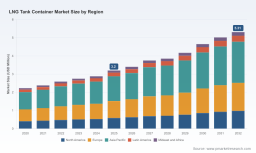
The LNG tank container market entered 2026 from a position of steady, measurable expansion. Measured on a market-wide basis (base year 2025), the sector grew from an estimated USD 2.23 million in 2020 to approximately USD 3.20 million in 2025, and our forecast — underpinned by a 7.5% CAGR over the 2026–2032 horizon — points toward continued, compound growth through 2032 (projected market size ~USD 5.31 million). This trajectory reflects the confluence of decarbonization-driven demand for flexible gaseous fuel logistics, the maturation of virtual-pipeline concepts, and expanding commercial use cases (from industrial feedstock to power back-up and off-grid supply).
LNG Tank Container Market
Why this report matters for 2026 strategy
-
Timing capital: Buyers, lessors and OEMs must align multi-year capital plans to an environment where demand is growing but concentrated — market concentration metrics indicate that the top three players control a clear majority of commercial supply, with the top five expanding that share further. This dynamic shapes pricing power, aftermarket services and scale advantages.
LNG Tank Container Market -
Operating model choices: The market’s growth supports multiple commercial models (ownership, leasing, managed fleets, and spot hire). Strategically choosing between them in 2026 will materially influence cashflow, balance-sheet exposure and route-to-market agility for the next five-plus years.
LNG Tank Container Market -
Regulatory and technical risk: Compliance with multimodal transport standards and class approvals remains a gating factor for cross-border projects. Early alignment to regulatory trajectories reduces costly rework for manufacturers and logistics providers.
What this study delivers — practical, board-ready content
-
Market sizing and forward curves (base year 2025; historical 2020–2025; forecast 2026–2032) built on primary interviews and transaction triangulation to support robust budgeting and scenario testing.
-
Proven methodology appendix documenting data sources, segmentation logic and sensitivity testing so CFOs and strategy teams can reproduce and stress-test assumptions.
-
Supply-chain mapping from raw-material inputs through finished-unit testing and certification, highlighting critical nodes and single-point risks for procurement teams.
-
Competitive benchmarking: capability matrices for OEMs, large lessors and specialist engineering providers, with payback profiles and go-to-market footprints.
-
Operational playbooks: procurement checklist, RFP templates, inspection & acceptance criteria, and maintenance scheduling that shorten time-to-deployment for project teams.
-
Investment decision tools: NPV/IRR sensitivity templates, leasing vs. buying calculators, and three investment-ready case studies tailored to upstream, midstream and industrial off-takers.
-
Regulatory compliance checklist and certification roadmap aligned to ISO 1496-3, IMDG, ADR, RID, ASME and DOT regimes and common class societies.
-
Risk and mitigation matrix covering raw-material volatility, labor skill gaps in cryogenic fabrication, and cross-border certification friction.
Five strategic takeaways for 2026
-
Adopt a hybrid fleet strategy. With market volumes rising at roughly a mid-single-digit CAGR into the next decade, blended models that combine owned assets for core routes with leased capacity for demand spikes minimize underutilized capital and protect project timelines.
-
Prioritize certification-first sourcing. Suppliers with proven class approvals and cross-jurisdiction certifications unlock faster commercial deployment. For buyers, contractual milestones tied to class certificates materially reduce commissioning risk.
-
Factor manufacturing labor complexity into lead-time assumptions. High-vacuum multilayer insulation, cryogenic welding and composite integrations introduce specialized labor inputs — underestimating these will extend procurement cycles and compress margins.
-
Design for modularity and multi-modal interoperability. ISO tank containers that meet international multimodal standards deliver higher utilization across shipping, rail and road networks and reduce asset idle time.
-
Embed a “virtual-pipeline” play in growth plans. Off-grid distribution and temporary infrastructure use-cases create near-term demand pockets that can be captured through flexible logistics arrangements and standardized container platforms.
Competitive landscape — who matters and why
The LNG tank container market combines a handful of global OEMs with regional specialists and financially-driven lessors. Market concentration metrics underscore a competitive environment where scale and certification breadth matter: the top three players hold a substantial share, and the five largest firms increase that influence further, shaping OEM pricing, aftermarket services and fleet availability.
-
CIMC Enric Holdings Limited (Shenzhen, China): A vertically integrated manufacturer notable for multi-size ISO tank formats and broad compliance to international standards. Strengths include production scale, a diversified product portfolio and deep experience in multimodal certification regimes — a natural choice for customers prioritizing steady supply and standards conformity.
-
Zhangjiagang Furui Group Co., Ltd. (Zhangjiagang, China): A specialist in cryogenic ISO tanks with high-vacuum, multilayer insulation designs. Recent deliveries into complex markets highlight its capability to meet stringent transport and safety requirements — attractive for projects needing tailored cryogenic engineering.
-
TransWorld Equipment (United States): Acts as a regional engineering and distribution representative, offering North/South American market access to large-capacity ISO tanks and hazardous materials expertise. Their market role exemplifies how distribution partners can accelerate local deployment through engineering services and aftersales support.
-
Chart Industries, Inc. (United States): Known for transportable cryogenic solutions with certified T75 model families and a focus on durability and hold-time performance — a fit for customers emphasizing lifecycle performance and reliability in end-use applications.
-
Srisen Energy Technology Co., Ltd. (China): Offers a broad range of tank formats and storage systems; appeals to buyers looking for diversified product configurations and competitive cost structures.
-
MCM Management, Control & Maintenance SA (Switzerland): A leasing specialist expanding fleets with advanced designs, illustrating the fast-growing role of asset managers in unlocking demand through flexible commercial structures.
Supply-chain and regulatory dynamics to watch
-
Material choices and fabrication standards are consequential. Inner vessels typically use carbon steel (e.g., ASTM A516) or stainless grades (e.g., SA240Gr304L), with frames from structural steels such as Q235B/S235JR — material selection affects thermal performance, weldability and lifecycle maintenance.
-
Volumetric physics underpins logistics economics: LNG stores at roughly one six-hundredth the gaseous volume, which creates opportunities for container-based distribution but also requires strict tightness, insulation and pressure control engineering.
-
Regulatory compliance is non-negotiable. ISO 1496-3, IMDG, ADR, RID, ASME and DOT standards dictate design envelopes, pressure ratings and multimodal interoperability; class approvals (LR, BV, DNV, CCS and equivalents) are operational gating factors for international projects.
-
Labor and skills: Advanced cryogenic assembly requires specialized welding and handling skills; this labor intensity is a recurrent cause of lead-time variability and should be explicitly priced into sourcing decisions.
Scenario planning: translating growth into decisions
With a forecast CAGR of 7.5% for 2026–2032, executive teams should model multiple scenarios: base-case growth aligned with the 7.5% path, an upside driven by accelerated onshore/off-grid projects, and a downside reflecting slower-than-expected adoption or policy shifts. Each scenario yields different capital timing for ordering containers, structuring leases, and securing manufacturing slots. Importantly, given the market’s concentrated supplier base, lead times and slot availability — particularly for class-certified units — will materially affect project phasing and working-capital needs.
How to use this research in the 2026 boardroom
-
Procurement calibration: Use the market-sizing and supplier-capability matrices to define order cadences, contractual delivery milestones and penalty regimes tied to certification milestones.
-
CapEx planning: Incorporate the forecast curve into multi-year capex budgets and test alternative ownership models using provided leasing vs. buying financial tools.
-
M&A and partnerships: Screen targets against capability gaps (e.g., certification breadth, regional service footprint, production capacity) to prioritize tuck-ins that accelerate market entry.
-
Operational pilots: Launch controlled roll-outs leveraging leasing partners for proof-of-concept virtual-pipeline deployments before committing to large, long-lead orders.
-
Regulatory engagement: Prioritize early engagement with relevant class societies and transport regulators to de-risk international shipments and pre-clear designs for cross-border use.
Final note — what we deliberately withhold here
This introduction highlights the strategic implications and practical tools contained in the full PW Consulting study. To preserve our clients’ competitive edge and to respect the report’s role as an actionable, proprietary roadmap, we have deliberately withheld granular segmentation tables and full datasets that break down regional, product and application shares. Those detailed breakdowns — including multi-dimensional slicings, supplier-level share charts and scenario-specific demand curves — are available within the full report and are essential for transaction-level decision-making.
If your 2026 capital allocation, procurement schedule or market-entry plan depends on accurate timing and supplier-specific validation, the full PW Consulting LNG Tank Container Market report provides the verified numbers, templates and supplier dossiers to execute with confidence.
For detailed analysis of this topic, please visit the official page: LNG Tank Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com