

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ceiling-mounted Supply Pendants Market — USD 568.5M in 2025

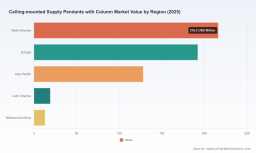
Ceiling-mounted Supply Pendants with Column Market — Strategic Outlook for 2026 Decision-Makers
As hospitals and acute care providers recalibrate capital spending and clinical workflows in 2026, ceiling-mounted supply pendants with columns are moving from niche infrastructure items to strategic enablers of operational efficiency, infection control and clinician ergonomics. This introduction summarizes the strategic value of PW Consulting’s full market study — highlighting data-driven signals, competitive dynamics, regulatory drivers and the practical decisions health-system and supplier executives must take in 2026. The full report contains granular segment-level intelligence and supplier scorecards to convert these insights into executable plans.
Ceiling-mounted Supply Pendants with Column Market
Market snapshot: a mature, steady-growth niche with structural tailwinds
Across 2020–2025 the market expanded from roughly USD 458 million to about USD 568.5 million (base year 2025), reflecting steady demand driven by OR/ICU modernization, retrofits and new-build hospital projects. Our forecast horizon (2026–2032) projects a modest compound annual growth rate (CAGR) of 1.88%, taking the market toward the mid-six-hundred million dollar range by the end of the period. The near-term path includes some lumpy demand as hospitals prioritize modular, lifecycle-friendly investments, but the structural drivers — workflow optimization, regulatory updates and reimbursement-aligned procurement policies — sustain long-term growth.
Ceiling-mounted Supply Pendants with Column Market
Why this matters for 2026 strategic choices
-
CapEx prioritization in a constrained environment: Health systems are increasingly selective about where capital goes. Pendants that demonstrably reduce throughput times, lower infection risk and simplify maintenance are more likely to clear budget reviews in 2026.
Ceiling-mounted Supply Pendants with Column Market -
Regulatory inflection point: NFPA 99:2024 and related standards have tightened specifications for medical gas and vacuum systems. Procurement and engineering teams must ensure new purchases and retrofit plans comply today, not tomorrow — non-compliance imposes rework costs and installation delays.
-
Operational ROI beyond acquisition price: Total Cost of Ownership (TCO) models that include installation complexity, downtime risk, consumables and service contracts are becoming the decisive evaluation criteria for both hospitals and leasing partners.
-
Supply-chain and material pressures: Aluminum alloys and corrosion-resistant materials dominate designs for durability in clinical environments. Fluctuations in raw-material costs and lead times materially affect pricing negotiations and inventory strategies.
How PW Consulting’s study informs 2026 decisions
Our study is positioned as a navigator for three distinct client personas: supplier executives (product, commercial and M&A teams), hospital procurement and engineering leads, and strategic investors. For each, the analysis converts macro trends into actionable choices without revealing confidential segment-level figures in this preview.
-
For suppliers: we include go-to-market scenarios that prioritize modularity, motorized vertical movement and integration with lighting/workstation systems — enabling faster approvals by clinical engineering and more competitive bids in tender processes.
-
For hospital operators: the report contains procurement frameworks to compare vendors on lifecycle cost, compliance footprint and upgrade pathways for existing OR/ICU footprints — critical inputs for 2026 budget cycles.
-
For investors/M&A teams: concentration metrics and competitive positioning analysis illuminate consolidation opportunities and adjacent bets (e.g., integrated OR systems, rental models, service-led revenue expansion).
Competitive landscape — what we observed from leading vendors
The market shows a mixed profile: specialist medical-equipment manufacturers with deep clinical relationships sit alongside regional engineering-focused firms. The top three players account for a meaningful but not dominant share of the market, and the top five remain well under majority control. This places a premium on focused product differentiation, channel strength and service capabilities.
-
Drägerwerk AG & Co. KGaA (Lübeck, Germany) — Product platforms such as modular ceiling-mounted units demonstrate how a systems approach (gas, power, accessory management) can be positioned as a clinical workflow solution rather than a point product.
-
Tedisel Medical S.L. (Badalona, Spain) — Recent product launches emphasize motorized vertical movement and modularity for ICU and OR configurations; these design choices simplify installation in constrained ceilings and appeal to retrofit projects.
-
Starkstrom (Germany) — Focus on mechanically robust column geometries and clinically driven mounting options positions them strongly for critical care theaters where reliability and serviceability are paramount.
-
Novair Medical (Spain) — Product sets tailored for space-constrained facilities and integrated gas management demonstrate opportunities in emerging-market hospital upgrades and smaller private clinics.
-
Brandon Medical (UK) — Their work on sizable projects highlights the importance of project-management capabilities, integration with other surgical systems and local support in winning large contracts.
-
KLS Martin SE & Co. KG (Germany) — Swiveling pendants and flexible room-positioning designs speak to OR planners who prioritize multi-configuration spaces.
-
Maquet (Getinge AB, Sweden/Germany) — Integration of pendants with surgical lights and workstation systems showcases the value of bundled offerings for turnkey OR solutions.
Recent market signals reinforce these patterns: product launches focused on modular ICU systems and high-profile project deployments underscore supplier differentiation by installation complexity, lifecycle service and clinical integration rather than price alone.
Regulation, procurement and installation — practical constraints that shape 2026 winners
-
Compliance-first buying: NFPA 99:2024 updates increase the attention that procurement and clinical engineering give to design tolerances, testing and documentation. Vendors that provide pre-certified modules and installation packages will shorten project timelines.
-
Installation labor matters: ceiling-mounted columns reduce floor clutter but create installation prerequisites (structural supports, gas routing). Suppliers that bundle structural assessment, installation crews and testing protocols reduce buyer friction.
-
Service and spare parts: longevity in installed bases shifts the competitive battleground to field service networks, remote diagnostics and predictable spare-part pricing.
-
Material choice and durability: aluminum alloys and corrosion-resistant finishes are table stakes; additional coatings and sealed electronics are differentiators for high-use environments.
M&A and investment implications
The market concentration metrics show a mid-level concentration: a meaningful share is captured by leading firms while a broad long tail remains populated by regional specialists and engineering houses. For investors and corporate development teams, this structure yields three clear playbooks for 2026:
-
Buy-and-build in regional markets to consolidate procurement and service footprints.
-
Acquire niche technology (e.g., motorized vertical movement, integrated monitoring) to upgrade modular product portfolios quickly.
-
Scale service-led revenue models (maintenance, certification, upgrades) where recurring cash flows and high switching costs improve valuation multiples.
What’s in the full PW Consulting report (practical, implementable elements)
-
Comprehensive market model (historical 2020–2025 and forecast 2026–2032) with scenario analysis and sensitivity to capex cycles and regulatory change.
-
Segmented demand analysis by geography, product type and clinical application — with buyer personas and procurement decision triggers. (Segment-level figures are available in the subscription report.)
-
Supplier scorecards covering product functionality, installation complexity, TCO, service network and compliance readiness for 20+ providers.
-
Installation and compliance playbook aligned to NFPA 99:2024 including checklist templates for clinical engineering and procurement teams.
-
Commercial playbooks for suppliers: value-based propositions, tender-response templates, and channel strategies calibrated for retrofit vs. new-build projects.
-
M&A screening tool: empirical filters to identify tuck-in targets, technology buys and regional consolidation opportunities.
Immediate actions for 2026
-
Hospital purchasers: prioritize vendor evaluations that include documented NFPA-compliance packages and turnkey installation commitments to reduce schedule risk.
-
Suppliers: accelerate modular, serviceable designs and expand pre-commissioned product offerings that shorten site time and reduce engineering hours billed to customers.
-
Investors: target companies with scalable service platforms and intellectual property around motorized movement and integrated workstation solutions.
Ceiling-mounted supply pendants with columns remain a technical yet strategically significant component of modern clinical spaces. For 2026 decisions, success will come from aligning product design, installation economics and compliance readiness to hospital operational outcomes — not from competing on headline price alone.
Next step
PW Consulting’s full study provides the granular figures, supplier evaluations and downloadable decision tools that translate the strategic themes above into procurement checklists, RFP templates and M&A screening outputs. Access the complete report to obtain the detailed segmentation data and supplier scorecards needed to finalize 2026 budgets and commercial plans.
For detailed analysis of this topic, please visit the official page: Ceiling-mounted Supply Pendants with Column Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com