

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Digital X-Ray Systems Market to Reach USD 6.86 Billion by 2032 at 4.5% CAGR

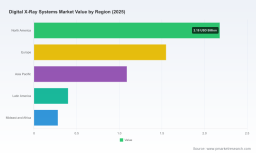
Digital X-Ray Systems Market — Strategic Briefing for 2026 Decision Makers
Executive summary
Digital radiography is no longer a niche upgrade; it is a core clinical infrastructure decision that shapes capital planning, service models, and care delivery economics. Our latest PW Consulting market study uses 2025 as the base year and an extended historical window (2020–2025) to deliver a forward-looking, action-oriented perspective across the 2026–2032 forecast horizon. At the macro level, the industry has expanded from the early-2020s troughs to approximately USD 5.5 Billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of roughly 4.5% through 2032, reaching the high‑single-digit billions by the end of the projection period. Despite steady headline growth, competitive dynamics, reimbursement reform, and rapid product innovation are creating asymmetrical opportunities for incumbents and new entrants alike.
Digital X-Ray Systems Market
Why this study matters for 2026 corporate decisions
- Capital allocation: Hospitals and imaging networks must prioritize where to replace legacy computed radiography and when to accelerate investments in wireless flat panels, mobile systems, and hybrid solutions to safeguard throughput and quality.
- Product strategy: Vendors face a choice between platform-led investments (integrated systems and service ecosystems) and component specialization (detectors, software, retrofit kits). Small differences in detector technology, system ergonomics, and clinical workflow integration will translate to meaningful procurement advantages.
- M&A and partnership timing: Fragmented market concentration and niche technology pockets make 2026 a pivotal year to evaluate bolt-on acquisitions, strategic alliances, or licensing deals to quickly secure detector IP, remote service capabilities, or channel access.
- Regulatory & reimbursement navigation: Changes to coding and payment frameworks materially affect ROI models for hospital administrators and vendor pricing strategies; early alignment yields competitive advantage.
Market dynamics: what is driving growth and disruption
The sector’s modest but consistent growth is a function of several intersecting forces:
Digital X-Ray Systems Market
- Technology substitution. The transition from plate-based computed radiography to modern direct radiography platforms continues, driven by workflow gains, dose efficiencies, and preference for wireless flat panel detectors that enable mobile and bedside imaging.
- Service and lifecycle economics. Customers increasingly procure integrated service agreements (hardware + managed services + uptime guarantees) rather than capex-only purchases, shifting vendor value propositions toward lifecycle profitability.
- Regulatory and coding changes. The 2026 CPT code set introduced a large set of codes recognizing digital health and AI-enabled imaging pathways, while updates to Medicare’s coding policies have raised expectations for procedural specificity. Vendors and provider procurement teams must bake new coding scenarios into reimbursement models.
- Product cadence. Vendors continue to launch floor-mounted, mobile, and hybrid systems with tighter detector integration and wireless responsiveness — influencing upgrade cycles and trade-in behaviors across installed bases.
Competitive landscape — who matters and how they compete
The competitive map is populated by a mix of diversified healthcare giants, imaging-focused incumbents, component specialists, and regional equipment manufacturers. Market concentration remains relatively low, indicative of an unconsolidated field where specialization and channel strength matter as much as scale. Key strategic archetypes include:
Digital X-Ray Systems Market
- Platform OEMs: Large system manufacturers that bundle X-ray systems with hospital IT, installation services, and financing solutions. Examples include Siemens Healthineers and GE HealthCare — both presenting full-system portfolios and push into workflow and service differentiation.
- Detector specialists: Firms concentrating on flat panel detectors and imaging components, supplying to OEMs and aftermarket channels. Varex Imaging typifies this profile with a focus on high-resolution detector technology.
- Hybrid players: Companies that straddle equipment, detectors, and IT enablement — Canon Medical Systems, Konica Minolta, and Carestream are examples, offering combinations of wireless detectors, mobile solutions, and retrofit pathways for legacy rooms.
- Regional and niche innovators: Smaller vendors and regionally strong manufacturers provide tailored solutions and competitive pricing to specific markets; they can be acquisition targets or partners for larger OEMs.
Representative competitive signals observed in recent 24 months underline how players are positioning:
- GE HealthCare advanced its floor‑mounted Definium Pace Select ET system (commercial availability mid‑2025), emphasizing integrated wireless detectors and high throughput for general radiography environments.
- Carestream achieved EU CE Mark for new detectors and a mobile X‑ray system in early 2025, underscoring continued investment in mobile solutions and regulatory momentum for cross‑market rollouts.
- Canon Medical introduced a hybrid DR system into the U.S. in early 2025 that combines wireless detector options with multifunctional room configurations — a direct play for flexible procurement programs in ambulatory and hospital settings.
Strategic implications — five decision levers for 2026
Based on the market trajectory and competitive behaviors, PW Consulting highlights five levers that should be active in executive agendas this year:
- Prioritize retrofit and upgrade pathways: With installed bases still significant, vendors that offer low-friction CR-to-DR upgrades, detector trade-in programs, and room-preserving installation options will capture near-term spend.
- Design services-first offers: Hospitals favor predictable uptime and rapid service. Bundles that combine cloud-enabled monitoring, proactive parts replacement, and outcome-linked SLAs create stickiness and recurring revenue.
- Invest selectively in detector IP: High-performance detectors remain the core differentiator. Targeted investments or acquisitions in detector development can create step changes in image quality, dose optimization, and mobile robustness.
- Model reimbursement scenarios: Update pricing and procurement models to include the 2026 CPT and Medicare coding revisions. Scenario-tested ROI cases should be a precondition for any major commercial negotiation in 2026–2027.
- Explore targeted M&A and partnerships: Given low top-three concentration, consolidation around complementary capabilities (AI-enabled image triage, remote diagnostics, or regional sales networks) can rapidly shift market position.
What the PW Consulting report provides — actionable chapters
Our Digital X‑Ray Systems Market study is structured to be immediately usable by strategy, product, and commercial teams. Highlights include:
- Market sizing and scenario forecasts (2026–2032) calibrated to current adoption curves and policy shifts — including upside/downside cases under alternative reimbursement trajectories.
- Segmentation intelligence with decision-grade insights on product types, clinical applications, and regional demand patterns — presented without raw segmentation leakage in this preview but fully enumerated in the full report.
- Vendor dashboards profiling product portfolios, go‑to‑market vectors, recent strategic moves, and competitor reaction matrices for nine core companies and peripheral players.
- Procurement playbook for provider buyers covering specifications checklists, negotiation levers, total cost of ownership models, and supplier evaluation templates.
- Regulatory and reimbursement playbook that translates coding updates (including the 2026 CPT code set and recent Medicare coding manual revisions) into revenue-impact scenarios and compliance steps.
- M&A and partnership screen — a prioritized list of capability gaps, acquisition candidates, and potential JV partners, with financial and integration risk profiles.
- Technology roadmap and R&D opportunity map highlighting detector innovation, edge AI integration for image triage, and service automation that improves uptime economics.
Methodology and confidence considerations
The study synthesizes primary interviews with hospital procurement leads, OEM product managers, and component suppliers, alongside secondary data from regulatory filings, product launch releases, and PW Consulting’s proprietary adoption model. Base-year calibration uses 2025 as the fiscal pivot. We report a central CAGR of 4.5% for the 2026–2032 horizon and provide sensitivity testing around key variables (device replacement cycles, reimbursement shifts, and supply-chain constraints). Market concentration analysis indicates a relatively fragmented competitive field, meaning strategic moves can yield outsized returns for fast‑moving challengers.
How to use this briefing in boardroom decision making
- Scenario planning: Run three procurement scenarios (conservative, base, accelerated replacement) across your service regions to determine capex timing and financing needs.
- Product roadmap alignment: Use the technology roadmap to prioritize detector R&D vs. system integration efforts based on projected payback windows.
- M&A prioritization: Employ the acquisition screen to shortlist targets that close capability gaps in wireless detectors, mobile systems, or AI workflow tools.
- Commercial playbooks: Implement service-first pricing pilots for a select cohort of hospital clients to test annuity models and reduce cyclical revenue exposure.
Concluding note — what this preview intentionally withholds
This executive preview highlights the strategic signal without publishing the full quantitative breakdowns that are required for transaction-level decisions. Specific region-by-region shares, detailed application splits, and granular price decks are reserved for the full PW Consulting report and accompanying data appendices. That level of detail is essential if you are validating procurement bids, pricing a divestiture, or modeling integration synergies.
Next steps
For buyers, vendors, and private equity investors preparing 2026 capital and M&A plans, the full market study equips you with the datasets, playbooks, and vendor intelligence necessary to execute with confidence. Contact PW Consulting to access the complete report and dataset, including downloadable competitor dashboards, detailed segmentation matrices, and scenario-driven financial models tailored for immediate decision use.
For detailed analysis of this topic, please visit the official page: Digital X-Ray Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com