

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
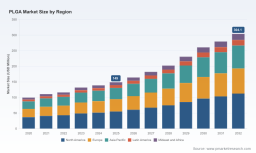
PLGA Market to Reach USD 304.1M by 2032 at 13.5% CAGR - PW Consulting

PLGA Market 2026: Strategic Imperatives for Decision-Makers
Executive snapshot
Poly(lactic-co-glycolic acid) (PLGA) is evolving from a niche biomedical polymer to a strategic raw material for drug delivery, implantables and regenerative medicine. PW Consulting’s 2026 PLGA Market study—anchored on a 2025 base year, with historical coverage from 2020–2025 and forward-looking forecasts through 2032—shows a market that has more than doubled in scale over the past decade and is projected to maintain robust expansion. Our model projects a compound annual growth rate (CAGR) of approximately 13.5% through 2032, with the global market expanding from the mid-hundreds of millions (USD, Million) in 2025 toward a broadly triple-digit figure by the end of the forecast horizon.
PLGA Market
Two high-level implications emerge immediately for corporate leaders planning in 2026: first, demand drivers are moving beyond simple cost competition—innovation in formulations and regulatory acceptance of long‑acting injectables are creating durable, higher-margin applications; second, supply‑side frictions (policy, feedstock pricing and manufacturing labor intensity) will determine which players capture the upside.
PLGA Market
Why this study matters for 2026 decisions
- Strategic sourcing and resilience: Recent tariff actions and elevated lactic‑acid inputs have reshaped cost curves and sourcing calculus. Procurement teams must plan for regional tariff overlays, alternative feedstocks and strategic inventory management.
- Product development prioritisation: PLGA remains a preferred polymer for controlled‑release drug products and resorbable devices. Developers need granular scenario models to decide when to invest in PLGA-based platforms versus complementary polymers or novel delivery systems.
- M&A and partnership timing: The market is fragmented—top-tier concentration remains modest—creating acquisition and partnership windows for mid‑sized specialty chemical manufacturers and contract development and manufacturing organizations (CDMOs).
- Regulatory strategy: Continued FDA approvals for PLGA-based long‑acting injectables, with no major recalls reported in 2025, lower regulatory risk but heighten the importance of documented manufacturing controls and GMP chain of custody for origin and traceability.
What the PW Consulting PLGA Market study delivers (practical content)
Our report combines quantitative models, supplier analysis and pragmatic playbooks tailored for commercial, technical and finance audiences. Key deliverables include:
PLGA Market
- Market sizing and validated historical time series (2020–2025) and base‑case and sensitivity forecasts (2026–2032) with scenario toggles for feedstock price shocks and policy shifts.
- End‑use demand mapping that links clinical pipeline trajectories and device approvals to polymer consumption profiles (note: granular regional and application splits and SKU‑level demand curves are presented in the full report and are intentionally not reproduced here).
- Supply‑chain blueprint showing incumbent producers, manufacturing footprints, and critical bottlenecks for GMP PLGA supply under high‑growth scenarios.
- Raw material and cost model that quantifies the pass‑through of lactic‑acid pricing, fermentation and purification yields, and labor intensity into finished PLGA pricing under multiple operating assumptions.
- Regulatory risk matrix and market access pathways for long‑acting injectables and resorbable implants, including dossier expectations, regulatory precedents and time‑to‑approval sensitivities.
- Commercial playbooks: supplier negotiation frameworks, vertical integration decision trees, and CDMO partnership templates including sample term sheets and technology transfer checklists.
- Supplier scorecards and capability heatmaps, curated vendor shortlists for strategic sourcing and co‑development, and M&A target screening criteria.
Competitive landscape: what the major players signal
The PLGA ecosystem comprises global specialty polymer manufacturers, research-scale suppliers and regional producers. The market remains fragmented—the top three suppliers control shares in the low twenties and the top five remain below thirty percent—creating fertile ground for strategic consolidation and selective partnerships.
- Corbion N.V. (Amsterdam) — With its PURASORB® GMP‑grade PLGA/PLA lines, Corbion is positioned as a go‑to supplier for controlled‑release excipients. Recent financial results indicate steady lactic‑acid demand supporting PLA production, a dynamic that underpins Corbion’s global procurement posture and provides them optionality in routing supply to PLGA customers.
- Evonik Industries AG (Essen) — Evonik’s RESOMER® and LACTEL® portfolios target parenteral and implantable applications. Strategic distribution partnerships (notably exclusive European arrangements announced in 2025) signal a channel‑led approach to expand reach into device OEMs and contract manufacturers.
- Akina, Inc. (West Lafayette, Indiana) — Akina’s PolySciTech®/PolyVivo® suite addresses the research and translational segments, providing flexibility for formulation development. Their product breadth supports early‑stage developers and academic collaborations, and they function as an important source of innovation for downstream commercial suppliers.
- Merck KGaA (Darmstadt) — Through Sigma‑Aldrich channels, Merck supplies both research‑grade and GMP‑compliant PLGA grades, bridging lab‑scale discovery and commercial production. Their strength lies in regulatory familiarity and integrated supply to pharmaceutical customers.
- Nomisma Healthcare Pvt. Ltd. (Pune) — A regional manufacturer supplying PLGA copolymers for pharmaceutical and biomedical applications, Nomisma illustrates the competitive pressure from cost‑competitive regional producers, particularly as companies seek diversified sourcing away from tariff‑impacted routes.
Collectively, these players demonstrate three strategic approaches: branded, GMP‑focused supply (scale + compliance); channel‑expanded distribution; and research‑to‑translation enablement. Each approach carries different margin structures and exposure to feedstock and policy risk.
Recent dynamics that will shape 2026 playbooks
- Tariff-driven sourcing shifts: Tariff increases on certain polymer imports implemented in early March 2025 have raised effective duties and prompted many buyers to diversify feedstock origins and to evaluate onshore capacity expansion. Procurement teams must model tariff pass‑through and consider strategic inventory or nearshoring.
- Input cost trends: Lactic‑acid feedstock pricing rose modestly through 2025, with market averages reflecting continuous demand from PLA and PLGA producers. Even slight increases in lactic‑acid cost can compress margins given the intensive fermentation and purification steps required for GMP‑grade material.
- Regulatory tailwind for PLGA applications: FDA approvals for PLGA‑based long‑acting injectables continued in 2025 with no new class recalls—this reduces regulatory uncertainty and improves commercial uptake probability for developers placing PLGA at the core of their delivery strategy.
- Distribution and channel moves: Recent distribution agreements underscore the importance of channel partners in penetrating medical device verticals and accelerating customer qualification.
Strategic playbook for 2026 — recommended actions
PW Consulting recommends the following actions, prioritized by time horizon and impact:
- Immediate (0–6 months): Conduct a supply‑chain stress test; run tariff and feedstock sensitivity scenarios against current procurement contracts. Secure contingent supply agreements with secondary manufacturers and negotiate escrowed pricing triggers tied to lactic‑acid indices.
- Short term (6–18 months): Lock in strategic distribution partnerships in markets where regulatory approval pathways are shortening. For polymer suppliers: invest in GMP capacity expansion tied to long‑acting injectable pipelines; for CDMOs: pre‑qualify multiple PLGA grades to offer formulators faster scale‑up.
- Medium term (18–36 months): Evaluate vertical integration or toll‑manufacturing models for critical PLGA grades. Consider bolt‑on acquisitions in regions providing tariff advantages or cost arbitrage to capture margin uplift as the market grows.
- Long term (36+ months): Build a differentiated product roadmap—specialty block copolymers, tailored degradation profiles, and regulatory dossiers—that moves value capture away from commodity pricing into formulation‑level IP and services.
How to use this introduction and where to find the data you need
This introduction is designed as a strategic “trailer”: it highlights the macro trajectory, commercial implications and decision frameworks that should be front‑of‑mind for corporate leadership in 2026. To operationalize the guidance above, the full PW Consulting PLGA Market report provides the granular intelligence you need—detailed regional and application segmentation, SKU‑level demand curves, supplier scorecards with capability matrices, scenario models with price and tariff toggles, and downloadable data tables.
If your 2026 strategy hinges on the next move in PLGA—whether sourcing, product development or M&A—the full dataset and our bespoke advisory services will allow you to convert the market’s growth potential (anchored at a 13.5% CAGR across the forecast period) into executable, risk‑aware plans. PW Consulting stands ready to run customized scenario analyses and due‑diligence deep dives that map directly to board‑level decision timelines.
Next steps
- Access the full report for the complete data room, supplier scorecards and scenario models.
- Engage PW Consulting for a tailored 8‑week rapid assessment to align your procurement, R&D and M&A strategies with the PLGA growth curve.
- Request a live briefing to walk through implications for your specific product portfolio and supply footprint.
PLGA is no longer a supporting ingredient; for many companies it is a strategic lever. The decisions made in 2026—about where to source, whom to partner with, and which technologies to prioritize—will determine who captures the bulk of value as the market scales in the decade ahead.
For detailed analysis of this topic, please visit the official page: PLGA Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com