

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Viscose Staple Fiber Market to grow at 6.98% CAGR (2026-2032)

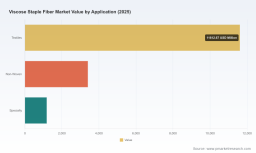
Viscose Staple Fiber Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
As the viscose staple fiber (VSF) market enters 2026, executives face a landscape shaped by steady demand recovery, raw-material volatility, and accelerating sustainability requirements. Our market model shows the global VSF market expanding from a base of USD 16,200 Million in 2025, growing at a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window and reaching roughly USD 25,900 Million by 2032. Historical momentum from 2020–2025 underpins this trajectory, but the shape of opportunity across product grades, geographies and end-use channels will be determined by a small set of strategic inflection points discussed below.
Viscose Staple Fiber Market
Why this report matters in 2026
-
Actionable foresight: The next 18–36 months will determine winners in a market where mid-cycle demand variation coexists with long-term structural growth. The report translates macro forecasts into near-term strategic choices—capacity timing, feedstock hedging, sustainability investments and portfolio shifts.
Viscose Staple Fiber Market -
De-risking CapEx: Capacity decisions are costly and lumpy. Our financial models and scenario runs let you test the impact of feedstock price swings and regulatory shocks on IRR, payback and utilization across alternative expansion timetables.
Viscose Staple Fiber Market -
Commercial differentiation: As sustainability-linked premiums and specialty applications gain traction, companies must choose between competing on cost, on integrated security of supply, or on differentiated fiber attributes (e.g., closed‑loop credentials, recycled feedstock, or specialty grades for hygiene and medical uses).
Practical contents of the PW Consulting VSF report
The research is built as a practitioner’s toolkit for 2026 decision-making. Key deliverables include:
-
Robust market sizing and a seven-year forecast (2026–2032) with demand scenarios tied to macro, apparel and non-woven end‑market trajectories.
-
Input-cost modelling for dissolving pulp and key chemical intermediates, with stress testing for price shocks and their pass-through to margins.
-
Regulatory and sustainability matrix profiling incentive regimes and compliance risk across major markets—highlighting which technologies and processes are rewarded under current and pending rules.
-
Competitive benchmarking with qualitative and quantitative scorecards (technology, feedstock integration, product portfolio, sustainability credentials and route-to-market strength).
-
Commercial playbooks for premiumization—how to price, certify and launch specialty fibers (e.g., recycled, bamboo blends, anti-microbial and flame-retardant grades) into textiles, medical and hygiene segments.
-
M&A and JV due‑diligence checklists and valuation sensitivity models tailored to VSF assets.
-
CapEx timing and phasing models that align greenfield or brownfield projects with expected demand windows and financing stress tests.
Market dynamics shaping 2026 decisions
-
Feedstock volatility: Dissolving‑pulp price swings remain the single biggest variable for VSF margins. Our scenarios show that a sustained commodity rally materially compresses unintegrated producers’ margins while advantaging players with captive or long-term pulp supply.
-
Regulatory divergence: North America and Europe are increasingly rewarding closed‑loop, low‑emission operations—creating a two‑tier market where certified low‑impact fibers command commercial preference and, in many cases, a price premium.
-
Product diversification: Adoption of specialty grades (medical, hygiene, flame-retardant, high‑wet‑modulus) continues to offset apparel cyclicality. Buyers in these segments prioritize consistency, traceability and certification.
-
Policy changes that matter: Recent regulatory shifts (e.g., the rescission of certain domestic licensing requirements in key markets) have immediate implications for market entry and competitive intensity—altering the cost and speed of capacity deployment for domestic and international players.
-
Upstream integration: New upstream capacity for polymer and pulp intermediates in regional hubs strengthens integrated value chains and gives vertically integrated producers a structural cost advantage in nearby markets.
Competitive landscape — what incumbents and challengers are doing
The market exhibits moderate concentration: the top three and top five producers together hold a meaningful share of global supply, creating room for scale players to influence pricing while leaving niches for differentiated suppliers.
-
Lenzing AG (Austria): Differentiates on closed‑loop, branded fibers under a premium label and pursues brand partnerships to secure offtake and downstream storytelling. Recent alliances with fashion brands underscore a strategic push to lock-in demand for certified fibers.
-
Birla Cellulose / Aditya Birla Group (India): Leverages upstream integration and scale to defend cost position. The group disclosed a major capacity expansion in late 2025 at a key facility—an explicit play for volume leadership and responsive supply into textile hubs.
-
Sateri (Singapore / China operations): Emphasizes modern mill footprint and branded eco‑offering to serve global account customers seeking reliable supply with sustainability attributes.
-
Chinese champions (multiple players): Several domestic producers pursue recycled-content lines, bamboo blends and next‑generation specialty fibers—including commercial launches of novel bamboo‑recycled blends and recycled‑content brands aimed at both domestic and export markets.
-
Smaller/Regional suppliers: Provide agility and niche specialty grades for local non‑woven and medical customers; these players are attractive consolidation targets for strategic buyers seeking immediate access to specialty channels.
Notable recent developments (strategic consequences)
-
New specialty launches: A notable player brought a bamboo‑recycled staple fiber to commercial scale in mid‑2025—an important example of how feedstock innovation can be commercialized quickly when paired with supply‑chain commitment.
-
Capacity additions: Late‑2025 announcements of large capacity increases by a global integrated producer indicate that supply growth will be back‑loaded into the second half of the decade—changing the supply/demand balance and pressing other producers to justify their own expansion plans.
-
Sustainability initiatives: Major groups have committed to substantial water‑reduction targets and partnerships with brands—signalling that environmental performance is now a baseline commercial requirement in many buyer relationships.
-
Regulatory removals and regional integration: Policy changes that relax domestic licensing in important manufacturing countries, alongside new upstream PTA and polymer integration projects, are reshaping competitive economics for regional producers.
Strategic choices for 2026 and near-term imperatives
Executives can use three pragmatic lenses to prioritize action in 2026:
-
Protect profitability: Lock in feedstock via long‑term contracts, explore captive pulp options, and deploy hedging strategies tied to dissolving‑pulp and intermediate chemical indices.
-
Differentiate commercially: Invest selectively in specialty and certified lines where margins and buyer stickiness are demonstrably higher. Use brand partnerships and traceability tools as commercial leverage.
-
De-risk growth: Phase capacity expansions with off‑taker commitments or JV structures. Where policy changes lower market entry barriers, prioritize brownfield additions or acquisitions over greenfield builds to accelerate time‑to‑market.
How PW Consulting supports your 2026 playbook
Our VSF study is designed to be immediately operational for strategy teams and CFOs. Deliverables include downloadable financial models you can re-run with your own assumptions, a regulatory compliance matrix that maps to likely market access costs, a supplier‑selection framework for pulp and chemical partners, and a staged CapEx implementation roadmap with gating milestones tied to market and policy triggers.
Conclusion — the critical decision horizon
2026 will be a year of choices: will your organization compete on scale, on integrated feedstock security, or on differentiated sustainable products? The market’s projected CAGR and the multi‑year demand expansion create opportunities for incumbents and new entrants alike—but timing, feedstock strategy and sustainability positioning will determine who captures value. For boardrooms and executive teams preparing budgets and capital plans this year, the difference between a well‑timed investment and a stranded asset will be informed by the granular segment and plant‑level detail that sits behind this executive overview.
Next steps
For the full intelligence suite—detailed plant and product‑level forecasts, segmented demand tables, company scorecards and the interactive financial models—review the full PW Consulting Viscose Staple Fiber Market report. That is where the segment-level matrices and company-level capacity maps live; the summary above intentionally frames the strategic imperatives while preserving the proprietary, transaction‑level detail available in the full report.
For detailed analysis of this topic, please visit the official page: Viscose Staple Fiber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com