

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Dyno Market at USD 2,000M in 2025, poised for 5.21% CAGR to 2032

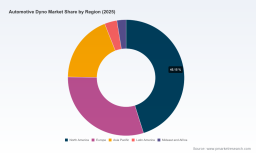
Automotive Dyno Market — 2026 Strategic Preview
PW Consulting presents a strategic introduction to our comprehensive Automotive Dyno Market study. This preview is written for executives, product leaders, and corporate strategists who must make capital, sourcing, and technology decisions in 2026. It demonstrates the analytical depth and operational focus of the full report while preserving the proprietary segment-level detail that is available in the complete research package.
Automotive Dyno Market
Why this study matters for 2026 decisions
The dyno market sits at the intersection of powertrain innovation, regulatory enforcement, and performance-driven aftermarket demand. Between 2020 and 2025 the global Automotive Dyno market expanded from an estimated USD 1,400 Million to USD 2,000 Million (base year 2025), reflecting robust investment in both legacy powertrain testing and an accelerating pivot toward electrified vehicle validation. Our modeled compound annual growth rate for the forecast window is 5.21%, and scenarios through 2032 show continued market expansion driven by EV/hybrid validation, automated test cells, and higher per-vehicle testing intensity in regulated markets. By 2032 the market trajectory points to a materially larger installed base and service ecosystem, underscoring why 2026 is a critical inflection year for strategic moves.
Automotive Dyno Market
Market dynamics and structural drivers
-
Electrification and powertrain complexity — The growth cadence is being reshaped by EV and hybrid test requirements. Dyno platforms are evolving from purely mechanical load devices into integrated electro-mechanical systems with high-fidelity e-motor test stands, bidirectional power handling, and battery-system interfaces.
Automotive Dyno Market -
Regulatory intensity and cycle acceleration — Emissions and safety test cycles are driving higher repeat-test frequencies and tighter traceability. Vendors are responding with modular platforms that support compliance workflows and long-duration road-load simulation.
-
Automation and software integration — Automated test cells and standards-compliant test sequences are transitioning from premium to table-stakes. Integration with test orchestration frameworks (e.g., RDE/STARS workflows) is already a differentiator among suppliers.
-
Performance and aftermarket demand — High-performance eddy-current and water-brake dynos remain critical for vehicle development and aftermarket tuning, preserving a steady demand niche parallel to OEM validation growth.
-
Supply chain and materials — Component sourcing for braking systems and high-power electronics introduces new procurement complexity; for example, some high-durability braking components rely on specialty alloys (nickel bronze family), which implies concentrational supplier risk and potential lead times for 2026 deployments.
What the full report delivers (practical, decision-ready content)
-
Actionable market sizing and trend models — multi-scenario forecasts from 2026–2032, with sensitivity to EV penetration, regulatory tightening, and OEM test-capacity utilization.
-
Procurement and CapEx playbook — TCO templates, depreciation models, and financing alternatives tailored for lab upgrades, new test cells, and large-scale simulation platforms.
-
Vendor scorecards and technology maps — independent assessment of supplier capabilities across performance, modularity, automation, software, service footprint, and standards compliance.
-
Operational readiness checklists — test-lab layout, utility and power requirements, calibration and traceability programs, and staffing/skillset profiles.
-
Regulatory and compliance matrix — mapping of global test-standard trajectories to required dyno capabilities and recommended validation roadmaps.
-
M&A and partnership screening — an evidence-based framework for identifying bolt-on acquisitions, JV targets, or strategic supply relationships that accelerate capability delivery.
Competitive landscape — positioning and recent moves
The market displays a moderate level of concentration: leading suppliers are sizable and specialized, but mid-market vendors and regional specialists retain meaningful niches. Top-three vendors account for a significant share of industry revenues, with the top-five widening the lead through technology breadth and service footprint.
-
AVL List GmbH (Graz, Austria) — recognized for high-precision electric and hybrid dyno systems and modular powertrain validation platforms. AVL’s modularity plays to OEMs seeking future-proof test benches that can adapt to EV/hybrid cycles and evolving standards.
-
HORIBA Ltd. (Kyoto, Japan) — a strong presence in both chassis and engine dyno systems, with high-throughput platforms capable of extensive annual simulated mileage. HORIBA’s portfolio is aimed at both emissions compliance and high-volume OEM test programs.
-
Mustang Dynamometer (Twinsburg, OH, USA) — focused on eddy-current chassis dynos for performance and AWD applications; recent catalog refreshes underline continued innovation for high-hp durability applications.
-
SuperFlow & Power Test — providers of water-brake and eddy-current dynos with integrated automation for heavy-duty and performance testing. Power Test’s 2025 facility investment and subsequent brand integration activity signal capacity expansion and consolidation moves in the North American supply base.
-
Rototest (Sweden) — leader in hub-coupled electric chassis dynos offering high-power road-load simulation for 4WD and EV validation — a capability increasingly requested by OEM R&D labs focused on drivetrain electrification.
-
Meidensha, MAHA, Dynojet, Taylor, Dyno One — collectively these players cover specialized niches from permanent-magnet dynos and inspection-integration hardware to tuning-centric solutions for powersports and performance segments. Some firms emphasize lab automation and standards compliance, while others dominate the aftermarket support channel.
Recent publicly reported activities provide strategic signals for 2026 planning. Examples include factory expansion and capacity investments, new product catalog releases focused on AWD and performance testing, and brand integrations that consolidate service networks. Taken together these moves suggest suppliers are preparing for a multi-year demand uplift while rationalizing service and production footprints.
Strategic implications and recommendations for 2026
-
Prioritize modularity and upgrade paths. Purchase decisions made in 2026 should emphasize platforms that provide electrical power-handling, bidirectional capabilities, and modular software stacks. These choices reduce mid-cycle replacement risk as validation requirements evolve.
-
Time CapEx to regulatory and program calendars. Test-lab expansions should be scheduled to align with OEM product milestones and known regulatory enforcement windows—accelerated procurement without a validated integration plan increases cost and downtime risk.
-
Embed automation and data-first operations. Suppliers with native tools for automated cycles, standardized diagnostics, and cloud-ready data stacks deliver outsized value by reducing per-test labor and improving traceability.
-
Hedge supply of specialty components. Locking multi-year supply contracts for critical alloys and power-electronics modules reduces execution risk for labs planning large fleet deployments in 2026–2028.
-
Expand service and calibration networks. As test architectures diversify, local service capability becomes a competitive differentiator; consider vendor agreements that include guaranteed response SLAs and calibration exchange programs.
-
Evaluate M&A for capability acceleration. For organizations seeking rapid entry into high-power hub-dyno testing or automation-led test cells, targeted acquisitions of regional specialists or software providers can close capability gaps faster than organic build.
How to use this preview and next steps
This document highlights the strategic contours of the dyno market and outlines where the full PW Consulting Automotive Dyno Market report delivers tangible decision support for 2026. Use the study to:
-
Inform board-level CapEx discussions with scenario-backed forecasts and TCO metrics;
-
Structure procurement RFPs with technology and service KPIs that reflect future-state needs;
-
Prioritize R&D and lab investments that maximize reuse and modular upgrades;
-
Screen M&A or partnership candidates with an evidence-based framework;
-
Calibrate field-service and spare-parts strategies to minimize downtime risk.
Closing — where PW Consulting adds value
Our full research package combines rigorous market modeling, vendor benchmarking, and operational playbooks designed to convert insight into action. For 2026, the key decisions are not merely about buying a dyno: they are about buying optionality, securing service delivery, and aligning test capacity with fast-shifting regulatory and technology cycles. PW Consulting’s market study equips you to make those trade-offs with confidence.
To access the detailed segment-level data, vendor scorecards, and acquisition screens referenced here, consult the full Automotive Dyno Market report and supporting Excel models available from PW Consulting. The granular figures and supplier-level metrics are intentionally held in the full analysis to preserve the integrity of our primary research and to support client-level advisory engagements.
For detailed analysis of this topic, please visit the official page: Automotive Dyno Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com